
Reports
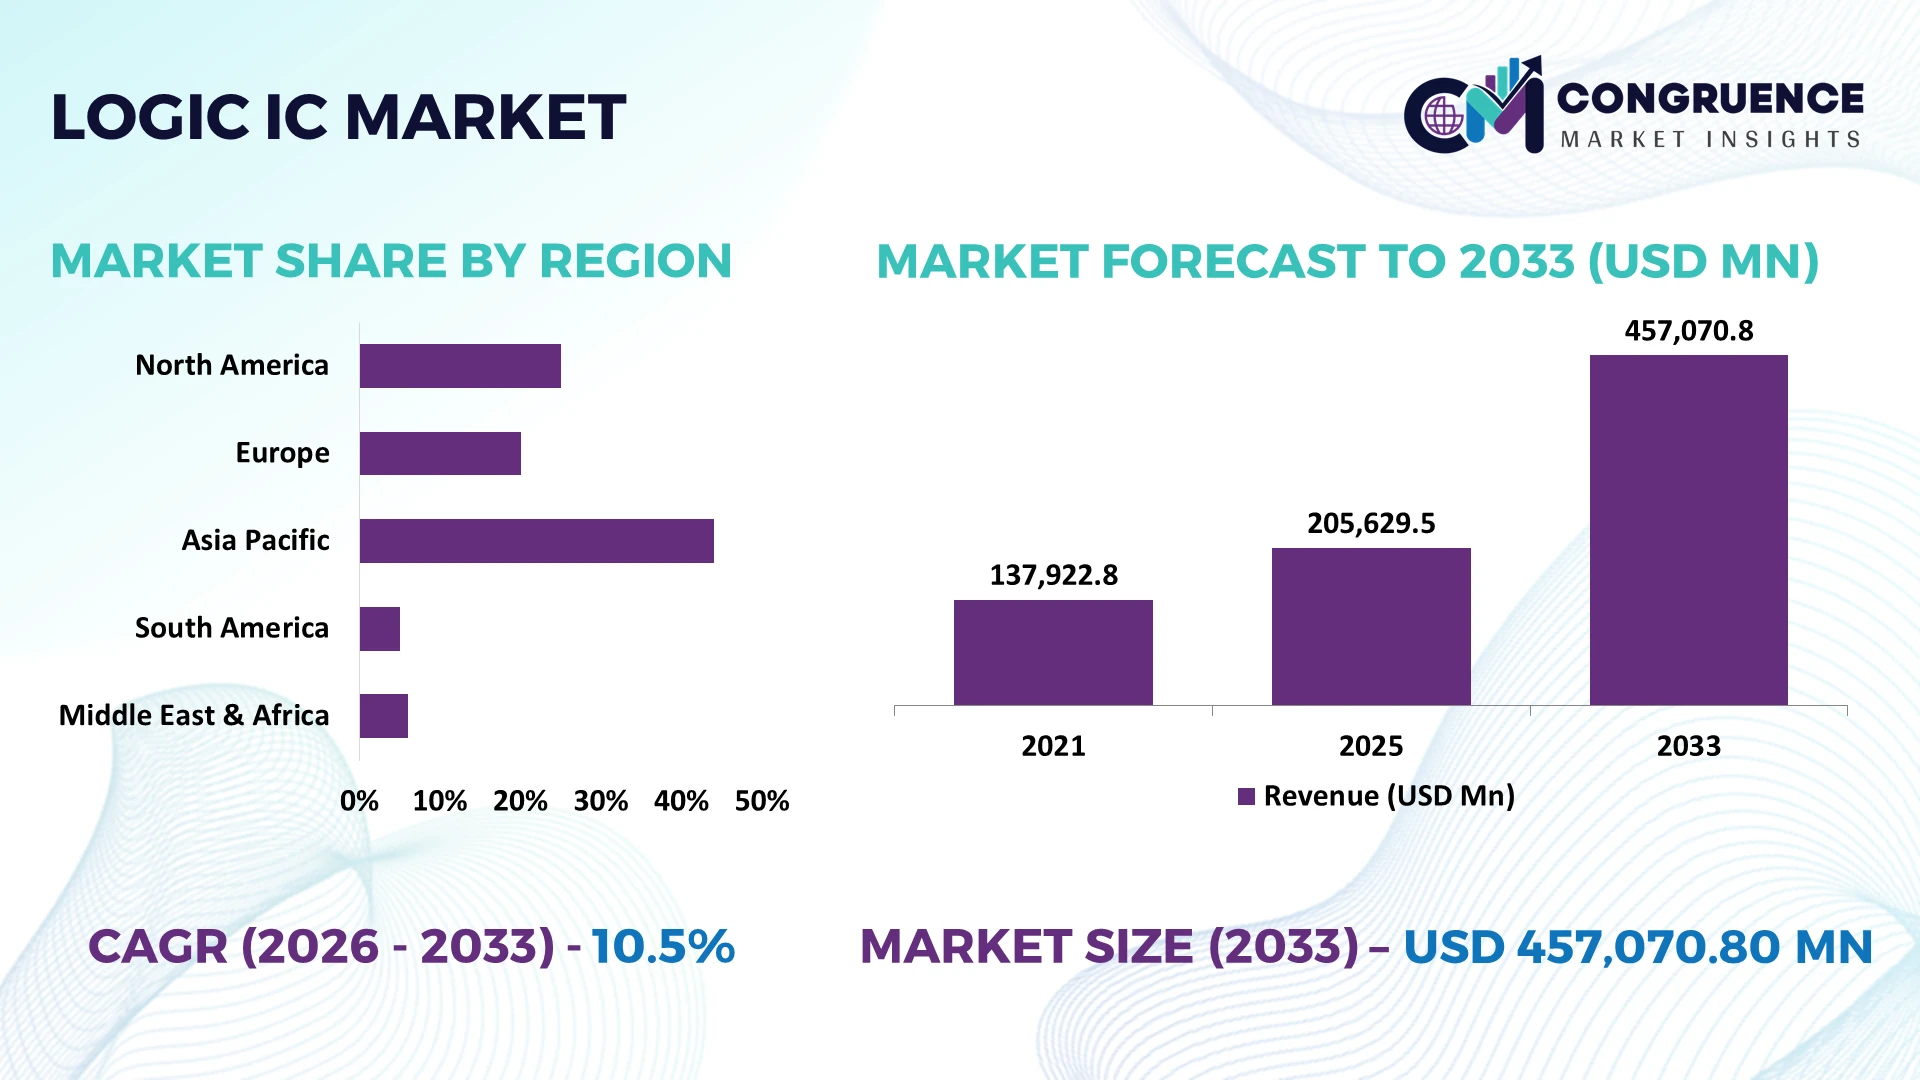
The Global Logic IC Market was valued at USD 205629.45 Million in 2025 and is anticipated to reach a value of USD 457070.8 Million by 2033 expanding at a CAGR of 10.5% between 2026 and 2033. Growth is driven by rising AI accelerator deployment, advanced smartphone and automotive computing architectures, and demand for energy-efficient logic processors manufactured on advanced semiconductor nodes.
Taiwan holds a pivotal position in advanced logic IC manufacturing, supported by TSMC’s leading-edge foundry capabilities and concentrated investment in sub-7-nanometer production. South Korea strengthens the competitive landscape through Samsung’s logic foundry operations and its broader semiconductor ecosystem, while the United States leads in chip design, processor architecture, and AI accelerator development. Geopolitical restrictions on advanced chip exports and efforts to diversify manufacturing under initiatives such as the U.S. CHIPS and Science Act are reshaping capacity investment and supply-chain strategies. For buyers, geographic diversification and access to leading-edge fabrication are critical to managing production continuity and technology roadmaps.
Strategic priority should center on securing advanced-node manufacturing capacity, qualifying alternative supply routes, and aligning chip design investments with AI, automotive, and data-center requirements.
Market Size & Growth: USD 205.63 billion in 2025 to USD 457.07 billion by 2033, at 10.5% CAGR, driven by AI computing and advanced-node integration.
Top Growth Drivers: AI accelerator adoption, advanced automotive computing, and high-performance data centers lead demand; a defensible market-wide driver percentage breakdown is unavailable.
Short-Term Forecast: By 2028, advanced-node capacity qualification and chiplet integration will remain key competitive priorities; no verified market-wide cost-reduction percentage is established.
Emerging Technologies: 2-nanometer fabrication, chiplet architectures, and advanced packaging strengthen computing density, power efficiency, and processor performance.
Regional Leaders: Asia-Pacific leads manufacturing, North America benefits from AI chip design, and Europe prioritizes automotive and industrial logic; comparable regional revenue forecasts aligned with the stated global valuation are unavailable.
Consumer/End-User Trends: AI servers and smartphones are major advanced-logic applications; high-performance computing accounted for 58% of TSMC's 2025 revenue by platform.
Pilot/Case Example: In 2025, TSMC increased wafer shipments to 15 million 12-inch-equivalent wafers from 12.9 million in 2024, reflecting higher manufacturing throughput.
Competitive Landscape: TSMC represented 40% of the Foundry 2.0 industry in 2025; key competitors include Samsung, Intel, GlobalFoundries, and SMIC.
Regulatory & ESG Impact: The U.S. CHIPS and Science Act supports domestic semiconductor manufacturing, while TSMC targets 100% renewable electricity by 2040.
Investment & Funding: TSMC announced USD 165 billion in planned U.S. manufacturing investment in 2025, reflecting the strategic shift toward geographic supply-chain diversification.
Innovation & Future Outlook: 2-nanometer chips, heterogeneous integration, and AI-specific processors will intensify competition around performance per watt, yield, and manufacturing scale.
The global logic IC market is increasingly shaped by AI accelerators, smartphone application processors, automotive control systems, and industrial automation. Advanced-node manufacturing and chiplet-based designs are becoming important for balancing computing performance, power consumption, and production costs. TSMC reported that technologies at 7 nanometers and below accounted for 74% of its wafer revenue in 2025, demonstrating the commercial importance of advanced process capabilities. Meanwhile, U.S. manufacturing incentives and Japan's investment in next-generation fabrication are reshaping capacity planning. These shifts make technology qualification, supplier diversification, and long-term fabrication agreements central to strategic investment decisions.
Logic ICs are becoming strategic assets because processor architecture determines computing performance, energy efficiency, and product differentiation across artificial intelligence, automotive electronics, telecommunications, and industrial automation. Semiconductor supply chains are being restructured as governments prioritize domestic fabrication and companies reduce dependence on concentrated manufacturing hubs. The U.S. CHIPS and Science Act allocated USD 52.7 billion for semiconductor manufacturing, research, and workforce development, reinforcing the shift toward geographically diversified production. This policy environment is changing capital allocation and supplier-selection strategies.
Taiwan maintains a leading position in advanced foundry manufacturing, while the United States combines chip design expertise with expanding domestic fabrication. South Korea benefits from integrated semiconductor capabilities, whereas Japan is strengthening its manufacturing ecosystem. For buyers, these differences affect access to advanced processes, production flexibility, and qualification timelines. Mature-node logic ICs remain commercially important for automotive controllers and industrial equipment, where reliability and cost often outweigh maximum transistor density.
Over the next two to three years, 2-nanometer fabrication, chiplet architectures, and advanced packaging will shape product development priorities. Chiplets allow companies to combine specialized dies manufactured using different process nodes, improving design flexibility without placing every function on the most expensive technology. AI processor developers are strengthening partnerships with foundries and packaging providers to secure production capacity. Competitive advantage will depend on balancing performance, manufacturability, supply resilience, and investment discipline.
AI model training, inference, and high-performance computing are increasing demand for specialized logic ICs that deliver greater throughput within strict power limits. According to the International Energy Agency, data centers consumed approximately 415 TWh of electricity globally in 2024, highlighting the infrastructure pressure behind more efficient computing architectures. This demand encourages hyperscalers to develop custom processors that reduce dependence on general-purpose chips and optimize workloads. Advanced packaging and high-bandwidth memory integration further improve system-level performance. U.S. technology companies are expanding custom silicon programs, while foundries are prioritizing advanced-node capacity and packaging investments. For manufacturers, the opportunity extends beyond wafer production to design collaboration, platform optimization, and long-term supply agreements. The strongest competitive position comes from aligning processor architecture with measurable workload efficiency rather than transistor scaling alone.
Advanced logic fabrication requires expensive lithography systems, stringent process control, and extensive yield optimization, creating high entry barriers for new manufacturers. ASML's high-numerical-aperture EUV systems carry prices reported at approximately EUR 350 million per unit, illustrating the scale of investment associated with next-generation production. Equipment procurement, facility construction, and process qualification also extend the time required to establish commercially competitive capacity. Meanwhile, dependence on a limited number of advanced foundries restricts buyers' ability to switch suppliers quickly. These conditions raise financing requirements and increase exposure to production disruptions. Companies are mitigating risk through multiyear capacity reservations, diversified supplier portfolios, and selective use of mature-node processes. The critical commercial decision is determining which products justify leading-edge manufacturing costs and which can maintain acceptable performance on established nodes.
Chiplet architectures create opportunities to combine specialized computing, connectivity, and control dies within a single package, allowing manufacturers to optimize individual functions independently. The automotive sector offers a particularly important application as software-defined vehicles integrate advanced driver assistance, infotainment, power management, and centralized computing. The European Union's revised vehicle-safety framework, including requirements introduced under its General Safety Regulation, strengthens the role of electronic control and driver-assistance systems in new vehicle platforms. Companies can capture value through automotive-grade logic, reusable chiplet intellectual property, and advanced packaging capabilities. India also offers opportunities in semiconductor design, electronics manufacturing, and automotive supply chains as domestic production capabilities expand. Strategic investment in functional safety, thermal management, and long-term component support can help suppliers secure design wins that extend across multiple vehicle generations.
Increasing logic complexity creates execution challenges across verification, cybersecurity, thermal management, and software integration. Modern processors can contain billions of transistors, making exhaustive validation impractical and increasing dependence on simulation, formal verification, and automated testing. Heterogeneous chiplet systems add further complexity because dies must communicate reliably despite differences in process technology, power characteristics, and interconnect behavior. Automotive and industrial applications impose additional requirements for functional safety, extended operating life, and predictable failure responses. These demands lengthen development cycles and increase the cost of late-stage design changes. Companies must strengthen electronic design automation capabilities, invest in hardware-security verification, and establish closer collaboration between silicon designers, foundries, packaging providers, and system integrators. Sustainable competitiveness depends on repeatable validation and dependable field performance, not simply faster processors or smaller manufacturing nodes.
Application-Specific ICs (ASICs) are a leading logic IC category, with one industry estimate placing their share at 72.1% in 2024. Their dominance reflects workload-specific architectures that improve integration, reduce unnecessary circuitry, and optimize power consumption in smartphones, networking equipment, and AI accelerators. However, ASICs require substantial upfront design investment, making production scale and predictable workloads important to commercial returns. Microprocessors remain essential for general-purpose computing, while microcontrollers support embedded control in automotive and industrial systems. Digital Signal Processors retain relevance in communications and real-time signal processing, whereas System-on-Chips consolidate computing, connectivity, and control functions to reduce board complexity.
Programmable Logic Devices offer post-deployment flexibility, while Logic Gates continue serving basic digital control functions. The fastest-growing category cannot be established reliably across these seven classifications because published market studies use different segment definitions. Nevertheless, AI-specific processing and integrated SoC architectures are attracting investment as manufacturers prioritize performance per watt. Companies are balancing customized designs against reusable platforms to manage development costs and accelerate product qualification.
Consumer Electronics represents a major application for logic ICs because smartphones, televisions, connected devices, and personal electronics require processors, controllers, and integrated digital functions at substantial production volumes. Application-specific designs and SoCs help manufacturers consolidate functionality, improve power management, and reduce component count. Computing also remains fundamental, spanning personal computers, servers, and high-performance processing systems. Automotive Electronics is gaining strategic importance as electric vehicles and advanced driver-assistance systems require more sophisticated control and computing architectures. Industrial Automation depends on reliable logic for robotics, programmable controllers, and machine vision, while Telecommunications and Networking Equipment require switching, routing, and signal-processing capabilities.
Data Centers are an increasingly important application because AI workloads require specialized accelerators and high-throughput processing. The International Energy Agency estimated that data centers consumed approximately 415 TWh of electricity in 2024, equivalent to around 1.5% of global electricity consumption. This pressure is accelerating investment in power-efficient computing architectures. Although consumer electronics provides established volume demand, automotive and data-center applications increasingly reward suppliers with specialized designs, rigorous validation, and long-term product support. Manufacturers are adapting portfolios to balance high-volume devices with technically demanding applications.
Consumer Electronics manufacturers represent a major end-user group because smartphones, home entertainment systems, connected appliances, and personal devices require logic ICs across multiple processing and control functions. Their purchasing decisions emphasize unit cost, integration, energy consumption, and product launch schedules. IT & Telecom companies require processors and networking logic for cloud infrastructure, communications, and enterprise computing, while Industrial Manufacturing buyers prioritize deterministic control, equipment reliability, and extended product availability. Automotive buyers increasingly require application-specific processors, microcontrollers, and integrated control systems that satisfy stringent safety and validation requirements.
Automotive and IT & Telecom buyers are shifting toward more specialized computing architectures as vehicle electrification, connected systems, and AI infrastructure expand. Healthcare uses logic ICs in diagnostic equipment, imaging systems, and patient monitoring, while Aerospace & Defense requires specialized reliability and, in certain applications, radiation tolerance. Government procurement supports secure computing, communications, and defense electronics. These smaller specialized markets often impose greater qualification requirements than high-volume consumer products. Manufacturers are responding with application-specific portfolios, automotive-grade components, dedicated customer engineering, and longer-term supply agreements. The strategic priority is to match design complexity and qualification expenditure to each buyer's lifetime demand and reliability requirements.
Asia-Pacific accounted for the largest market share at an estimated 65% in 2025, while North America is positioned for faster growth as AI infrastructure, domestic semiconductor manufacturing, and advanced processor development accelerate through 2033. These regional figures are directional estimates for the broader logic IC ecosystem rather than a verified, consistently defined market-share series.
Advanced AI Computing and Domestic Fabrication Expansion
North America benefits from concentrated semiconductor design expertise, hyperscale data-center investment, and expanding fabrication capacity. The United States anchors demand through AI accelerators, cloud processors, networking silicon, and advanced automotive computing, while Canada contributes through semiconductor design and specialized electronics. The region's strategic advantage lies in translating software and workload requirements into custom silicon, although leading-edge manufacturing still depends on a globally interconnected equipment and foundry ecosystem. U.S. export controls on advanced computing chips have also increased the importance of product classification, customer screening, and supply-chain planning. Companies are strengthening domestic production while retaining overseas manufacturing partnerships to manage cost, process maturity, and capacity constraints. Competitive advantage increasingly depends on integrating chip design, packaging, and system-level optimization rather than relying on fabrication location alone.
United States Market Outlook: The United States leads in processor architecture, AI chip development, and semiconductor research. The CHIPS and Science Act allocated USD 52.7 billion for semiconductor manufacturing incentives, research, and workforce initiatives. Intel, NVIDIA, AMD, and major cloud companies are shaping demand through processor development, foundry investment, and custom silicon programs. For buyers, domestic capacity improves supply-chain options, but advanced packaging, specialized equipment, and experienced manufacturing personnel remain critical constraints.
Automotive Electronics and Industrial Semiconductor Specialization
Europe's logic IC market is shaped by automotive engineering, industrial automation, aerospace systems, and demand for dependable embedded computing. Germany anchors automotive semiconductor applications, while France, the Netherlands, and Italy contribute through chip design, equipment, and specialized manufacturing. The European Chips Act aims to mobilize more than EUR 43 billion in policy-driven public and private investment, strengthening the region's semiconductor ecosystem. However, Europe's position is stronger in automotive-grade components, power electronics integration, and industrial applications than in leading-edge logic fabrication at scale. Automotive electrification and software-defined vehicle development are increasing requirements for microcontrollers, domain controllers, and safety-certified processors. Manufacturers are prioritizing resilient sourcing, energy-efficient production, and collaboration between chipmakers and automotive OEMs. The strongest opportunity lies in securing long-term design wins where reliability and qualification matter more than the lowest unit price.
Germany Market Outlook: Germany benefits from its automotive manufacturing base, industrial automation expertise, and established electronics supply chains. Semiconductor demand is supported by vehicle control systems, factory robotics, and industrial computing. The German government's support for semiconductor investment, including the planned ESMC fabrication facility in Dresden, strengthens domestic production capabilities. Suppliers that align product roadmaps with automotive functional safety, long product lifecycles, and industrial reliability requirements are well positioned to secure strategic customer relationships.
Manufacturing Scale and Advanced-Node Capacity Expansion
Asia-Pacific leads logic IC manufacturing through Taiwan's foundry ecosystem, South Korea's integrated semiconductor capabilities, China's extensive electronics production, and Japan's materials and equipment expertise. Taiwan remains central to advanced logic fabrication, while China sustains demand through smartphones, industrial electronics, and domestic semiconductor substitution. South Korea strengthens competition through memory integration and logic foundry investment. This manufacturing concentration gives regional suppliers advantages in ecosystem depth, customer proximity, and production scale, but also exposes buyers to geopolitical restrictions and cross-border logistics risks. Japan's semiconductor initiatives and expanding cooperation with international chipmakers are strengthening supply-chain diversification. Companies are investing in advanced packaging, process development, and domestic design capabilities to capture more value beyond wafer fabrication. For purchasers, manufacturing scale must be evaluated alongside export-control exposure, technology access, and the ability to qualify alternative suppliers.
Taiwan Market Outlook: Taiwan is the region's most strategically important advanced logic manufacturing hub, supported by TSMC's process technology, supplier network, and established customer relationships. TSMC announced plans in 2025 to invest an additional USD 100 billion in U.S. semiconductor manufacturing, bringing its announced U.S. commitment to USD 165 billion. Taiwan's long-term advantage rests on process expertise, yield optimization, and dense integration between foundries, packaging providers, and equipment suppliers.
Electronics Localization and Industrial Modernization
South America's logic IC demand is concentrated in Brazil, where automotive manufacturing, telecommunications, consumer electronics, and industrial equipment create recurring requirements for processors and embedded controllers. The region relies substantially on imported advanced chips, making exchange-rate movements, import costs, and international supply availability important procurement variables. Brazil's semiconductor policy initiatives and electronics manufacturing incentives support local assembly, design capabilities, and selected stages of the semiconductor value chain. However, limited leading-edge fabrication infrastructure prevents the region from matching the production scale of established Asian hubs. Companies therefore find stronger near-term opportunities in application-specific design, electronics integration, testing, and locally adapted industrial solutions than in capital-intensive advanced-node fabrication. Investment decisions should prioritize customer access, import resilience, and partnerships with established international suppliers. Local value creation is most realistic where semiconductor expertise connects directly to automotive, telecommunications, and industrial demand.
Brazil Market Outlook: Brazil offers the region's broadest electronics manufacturing base and a substantial automotive and telecommunications customer ecosystem. Its semiconductor strategy, including support for domestic design and production capabilities, creates opportunities for embedded logic, microcontrollers, and electronic system integration. Suppliers that establish partnerships with local manufacturers can improve customer responsiveness and navigate import-related constraints. However, advanced fabrication investment requires sustained demand, skilled personnel, and dependable access to specialized equipment.
Digital Infrastructure Investment and Semiconductor Demand Diversification
The Middle East and Africa market is shaped by data-center construction, telecommunications modernization, smart-city projects, industrial digitization, and government technology programs. Saudi Arabia and the United Arab Emirates are investing in AI infrastructure and cloud services, increasing demand for server processors, networking logic, and specialized computing systems. South Africa contributes through telecommunications, mining automation, and industrial electronics, while other African markets are expanding connectivity and digital services from a smaller infrastructure base. The region remains dependent on imported logic ICs, making equipment availability, procurement costs, and technical support important considerations. Large AI infrastructure projects also create demand for reliable power management, cooling, and network capacity alongside processors. Suppliers are pursuing enterprise partnerships, regional distribution, and system integration rather than relying on local chip fabrication. Commercial success depends on matching computing deployments to electricity availability, connectivity, and practical operating costs.
Saudi Arabia Market Outlook: Saudi Arabia is emerging as a strategic buyer of AI computing infrastructure, supported by national digital transformation programs and investment in data centers. The country's National Strategy for Data and AI targets a leading international position in AI by 2030. Logic IC suppliers can benefit from partnerships with cloud operators, telecommunications companies, and infrastructure developers. However, project economics depend on power availability, cooling efficiency, cybersecurity requirements, and access to specialized technical expertise.
The Logic IC market combines fabless designers, integrated device manufacturers, and contract foundries competing for control over architecture, manufacturing access, and customer relationships. NVIDIA, AMD, Qualcomm, and Broadcom compete through specialized processors, connectivity silicon, and application-specific designs, while Intel and Samsung pursue differentiated strategies spanning chip design and manufacturing. TSMC competes primarily through foundry technology, production yields, and customer capacity commitments.
Competition remains fragmented across product categories, and a reliable combined market-share figure for the five largest players is unavailable because company portfolios and market definitions overlap. Performance per watt, fabrication access, and design customization increasingly determine purchasing decisions. Advanced-node chips command premium engineering resources, while mature-node products compete more heavily on cost and reliability. AI accelerator demand is redirecting investment toward advanced packaging, chiplet integration, and high-bandwidth memory partnerships. Export controls and geographic diversification are also reshaping manufacturing decisions. High capital requirements, intellectual-property barriers, and specialized engineering expertise constrain new entrants. Winning requires differentiated architectures, dependable manufacturing access, strong ecosystem partnerships, and commercially sustainable product performance.
Intel Corporation
NVIDIA Corporation
Advanced Micro Devices, Inc. (AMD)
Qualcomm Incorporated
Broadcom Inc.
MediaTek Inc.
Samsung Electronics Co., Ltd.
Taiwan Semiconductor Manufacturing Company (TSMC)
Micron Technology, Inc.
Texas Instruments Incorporated
Renesas Electronics Corporation
STMicroelectronics N.V.
Infineon Technologies AG
Advanced-node fabrication, chiplet integration, and AI-specific architectures are reshaping logic IC performance. Two-nanometer gate-all-around transistors improve electrostatic control compared with established FinFET designs, supporting higher performance or lower power at comparable operating conditions. TSMC's N2 technology entered volume production in late 2025, strengthening access to next-generation processors. Actual efficiency gains depend on workload, design, and process implementation. Manufacturers are prioritizing design-technology co-optimization to improve yield and reduce costly redesign cycles.
Advanced packaging combines computing dies, high-bandwidth memory, and interconnects within compact systems. Compared with conventional monolithic designs, chiplets can improve design flexibility and reuse, although packaging complexity and testing costs remain important constraints. Adoption is strongest in high-performance computing and AI accelerators, where memory bandwidth and system throughput influence deployment economics. NVIDIA, AMD, and leading foundries benefit from integrating processor architecture with packaging expertise, while suppliers invest in thermal management and multi-die validation.
From 2026 to 2028, 2-nanometer production, backside power delivery, and advanced chiplet interconnects will influence competitive differentiation. These technologies target improved power delivery, computing density, and energy efficiency, with gains varying by implementation. Automated electronic design tools and AI-assisted verification also shorten selected engineering workflows. Companies should prioritize technologies against measurable performance-per-watt targets, qualification schedules, and manufacturing yields rather than node labels alone. Early ecosystem partnerships will improve capacity access and accelerate product readiness.
- March 2025 — TSMC announced an additional USD 100 billion in planned U.S. semiconductor investment, bringing its intended commitment to USD 165 billion, including three fabrication plants, two advanced packaging facilities, and an R&D center to strengthen geographically diversified AI chip manufacturing. Source: TSMC
- March 2025 — NVIDIA unveiled Blackwell Ultra, advancing AI accelerator performance through the GB300 NVL72 platform and 800 Gb/s networking per GPU. The launch strengthens demand for high-performance logic, integrated systems, and specialized infrastructure across enterprise AI deployments. Source: NVIDIA
- March 2025 — Reuters reported that NVIDIA and Broadcom were testing chips using Intel’s 18A manufacturing process. The evaluations indicated potential foundry customer interest, creating an opportunity for Intel to attract external manufacturing contracts and strengthen competition in advanced logic fabrication. Source: Reuters
- April 2026 — Broadcom expanded its partnership with Meta to support multi-gigawatt deployments of custom AI accelerators, with an initial commitment exceeding 1 GW. The collaboration strengthens demand for customized logic, advanced packaging, and integrated AI networking infrastructure. Source: Broadcom
The Logic IC Market Report examines market structure, technology transitions, competitive positioning, and investment priorities across Microprocessors, Microcontrollers, Digital Signal Processors, Application-Specific ICs, System-on-Chips, Logic Gates, and Programmable Logic Devices. Application coverage includes Computing, Consumer Electronics, Automotive Electronics, Industrial Automation, Telecommunications, Data Centers, and Networking Equipment. End-user analysis evaluates Consumer Electronics, Automotive, IT & Telecom, Industrial Manufacturing, Healthcare, Aerospace & Defense, and Government.
Regional coverage spans North America, Europe, Asia-Pacific, South America, and the Middle East & Africa, with country-level analysis of manufacturing capabilities, deployment patterns, infrastructure investment, and supply-chain dependencies. Technology assessment addresses advanced-node fabrication, chiplet architectures, heterogeneous integration, advanced packaging, and power-efficient processor design. Competitive analysis examines major manufacturers, foundries, differentiation strategies, and capacity expansion. The report supports investment planning, market-entry decisions, supplier diversification, product development, and competitive positioning through 2033, emphasizing operational efficiency, manufacturing access, and emerging application opportunities.
| Report Attribute/Metric | Report Details |
|---|---|
Market Revenue in 2025 | USD 205629.45 Million |
Market Revenue in 2033 | USD 457070.8 Million |
CAGR (2026 - 2033) | 10.5% |
Base Year | 2025 |
Forecast Period | 2026 - 2033 |
Historic Period | 2021 - 2025 |
Segments Covered | By Type
By Application
By End-User
|
Key Report Deliverable | Revenue Forecast, Growth Trends, Market Dynamics, Segmental Overview, Regional and Country-wise Analysis, Competition Landscape |
Region Covered | North America, Europe, Asia-Pacific, South America, Middle East, Africa |
Key Players Analyzed | Intel Corporation, NVIDIA Corporation, Advanced Micro Devices, Inc. (AMD), Qualcomm Incorporated, Broadcom Inc., MediaTek Inc., Samsung Electronics Co., Ltd., Taiwan Semiconductor Manufacturing Company (TSMC), Micron Technology, Inc., Texas Instruments Incorporated, Renesas Electronics Corporation, STMicroelectronics N.V., Infineon Technologies AG |
Customization & Pricing | Available on Request (10% Customization is Free) |




