
Reports
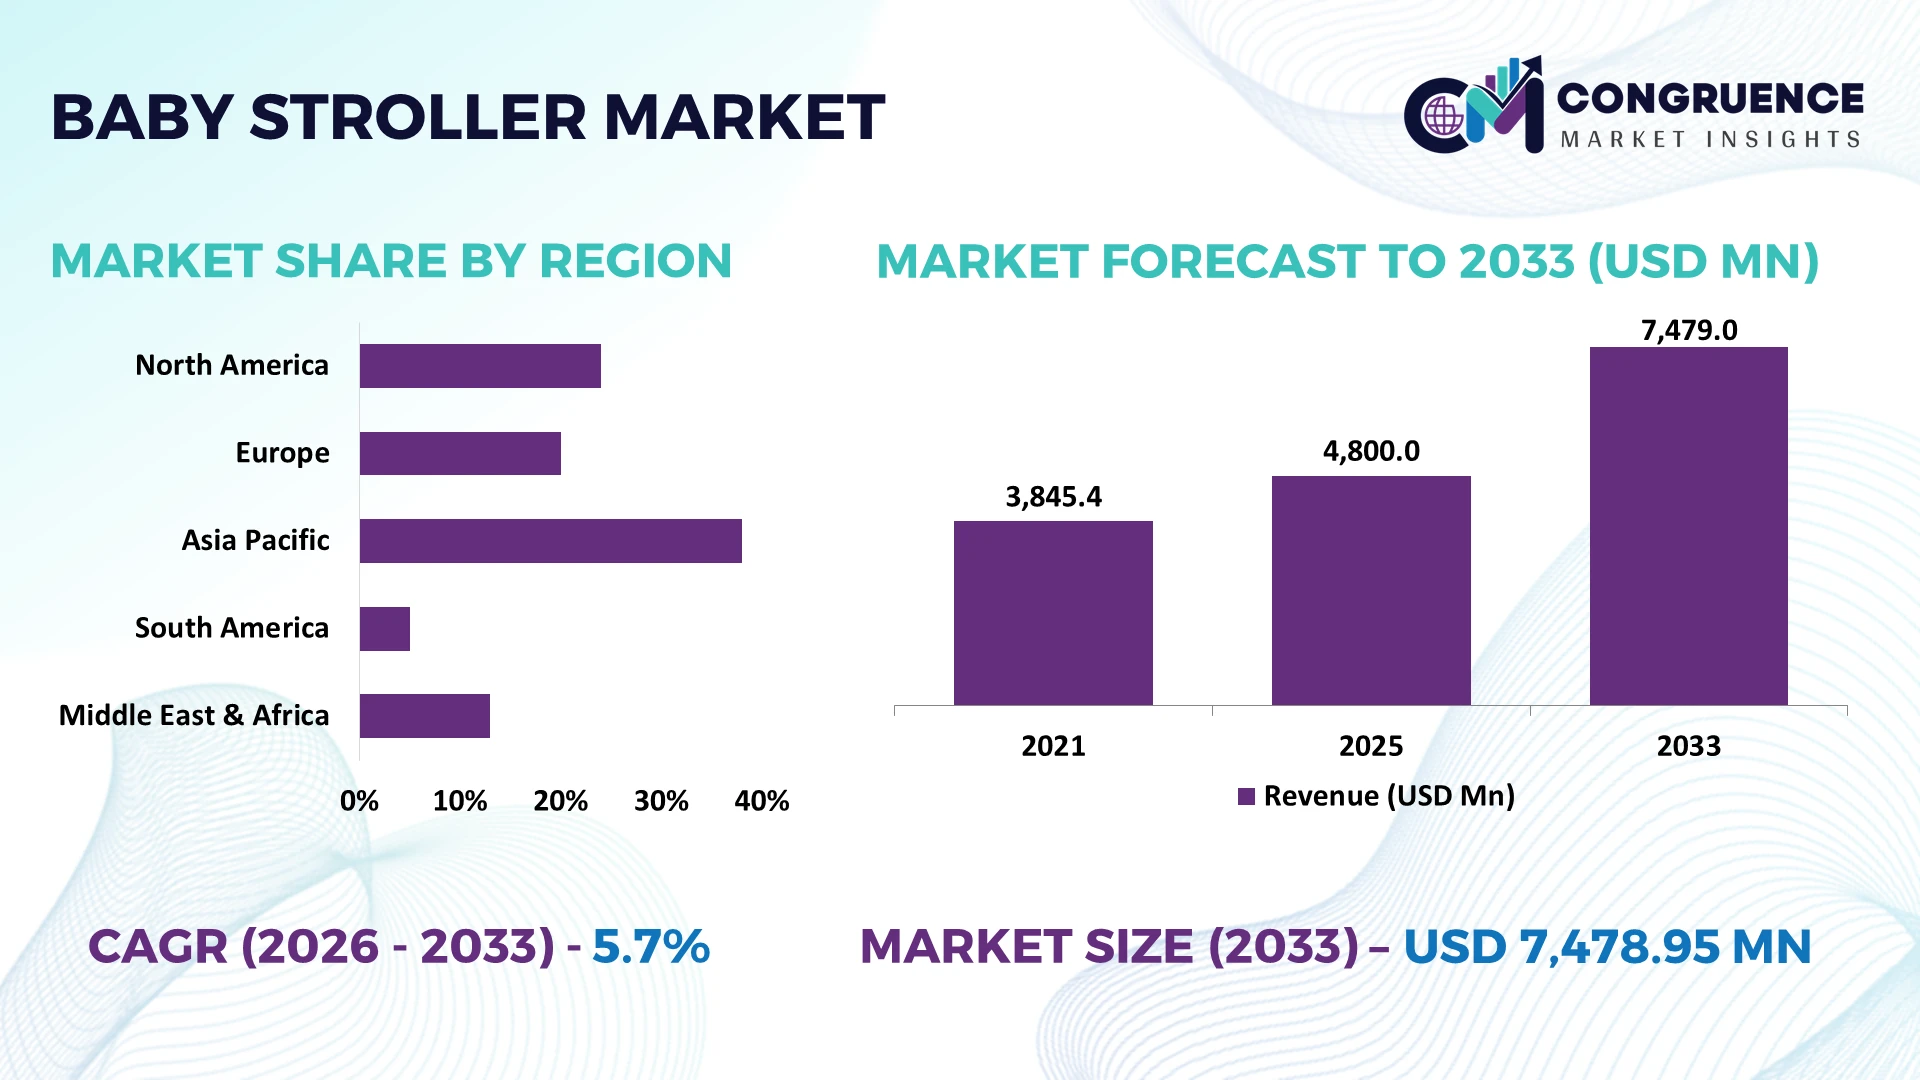
The Global Baby Stroller Market was valued at USD 4800 Million in 2025 and is anticipated to reach a value of USD 7478.95 Million by 2033 expanding at a CAGR of 5.7% between 2026 and 2033. Premium modular travel systems, lightweight folding architectures, car-seat integration, urban mobility needs, and stricter child-safety engineering are shifting purchases toward higher-specification strollers.
China represents an estimated 24–27% of global baby stroller demand while maintaining a substantially larger manufacturing footprint through Guangdong, Zhejiang, and Jiangsu juvenile-product clusters. China recorded 9.54 million births in 2024, supporting domestic replacement and first-time purchases, while integrated aluminum fabrication, textiles, plastics, and OEM assembly strengthen export capacity. Compact one-hand folding and sub-10 kg designs increasingly define premium urban products. The United States represents approximately 20–22% of global demand versus China’s 24–27%, but U.S. buyers show stronger premium travel-system penetration. China’s manufacturing scale remains decisive, while U.S.–China tariff exposure and Red Sea freight disruptions are pushing global brands toward supplier diversification and Southeast Asian final assembly.
Baby stroller manufacturers combining Chinese manufacturing depth with diversified sourcing, certified safety engineering, and compact modular platforms are positioned to capture the strongest premium and urban-mobility opportunities.
Market Size & Growth: USD 4,800 million in 2025 reaches USD 7,478.95 million by 2033 at 5.7% CAGR, driven by modular travel systems, compact folding, and premium safety engineering.
Top Growth Drivers: Premiumization contributes approximately 30%, urban compact-mobility needs 25%, and car-seat-compatible travel systems 20% of modeled incremental demand.
Short-Term Forecast: By 2027, advanced folding architectures will reduce folded stroller volume by approximately 20–30%, strengthening adoption among apartment households, travelers, and compact-vehicle owners.
Emerging Technologies: Sensor-assisted braking, electric propulsion, and advanced lightweight frames are expanding, with premium carbon-fiber structures reducing frame weight by approximately 20–30% versus conventional aluminum configurations.
Regional Leaders: Asia-Pacific approaches USD 3.0 billion, North America USD 1.7 billion, and Europe USD 1.6 billion by 2033, with compact urban travel systems gaining adoption across all three.
Consumer/End-User Trends: One-child households increasingly prioritize multifunctionality; premium systems now combine 3–5 configurations spanning carrycot, infant car seat, parent-facing, forward-facing, and toddler operation.
Pilot/Case Example: In 2025, CYBEX expanded its e-Priam platform using hill and uneven-surface assistance, with powered support designed for gradients reaching approximately 25%.
Competitive Landscape: Goodbaby leads manufacturing scale with an estimated 12–15% global share, competing with Newell Brands, Artsana, UPPAbaby, Bugaboo, and premium specialist CYBEX.
Regulatory & ESG Impact: EU product-safety modernization strengthens traceability and online-marketplace accountability, while recycled textiles and aluminum structures can reduce virgin-material requirements by approximately 20–40% in redesigned components.
Investment & Funding: China’s 9.54 million births in 2024 sustain juvenile-product manufacturing investment, while global brands increasingly allocate sourcing across 2–3 countries to reduce tariff and freight concentration.
Innovation & Future Outlook: Sub-10 kg platforms, electric assistance, modular 3-in-1 architectures, and recycled fabrics are shifting competition toward mobility ecosystems combining portability, safety, durability, and accessory interoperability.
The Baby Stroller Market is increasingly shaped by compact urban mobility, modular travel systems, premium safety features, and lightweight materials. One-hand folding designs can reduce stored volume by 20–30%, improving usability for apartments and travel. Meanwhile, tariff exposure and freight disruptions are accelerating supplier diversification beyond China, positioning adaptable manufacturing and integrated stroller-car-seat ecosystems at the center of strategic competition.
The Baby Stroller Market is becoming strategically important as competition shifts from basic wheeled transport toward integrated mobility systems combining compact folding, car-seat compatibility, lightweight materials, assisted propulsion, and connected controls. Supply-chain restructuring is reinforcing this transition: global brands are diversifying final assembly beyond China while retaining access to established aluminum, textile, wheel, plastics, and component ecosystems concentrated across Guangdong and Zhejiang.
Modern ultra-compact strollers weighing about 7.3 kg can fold in roughly one second and occupy substantially less storage space than conventional full-size platforms, improving airport, apartment, and vehicle usability. Electrically assisted models support gradients near 25% and assistance speeds up to 6 km/h, reducing pushing effort on hills. China leads production scale, while Germany, the Netherlands, and the United States remain stronger in premium engineering, modularity, and connected mobility adoption.
Through 2026–2028, investment will concentrate on lightweight frames, one-hand folding, recycled materials, electronic assistance, and stroller-car-seat ecosystems. A practical example is app-connected hill support and automated rocking in premium e-strollers. Manufacturers are expanding modular platforms, component partnerships, and localized distribution. Competitive advantage will increasingly depend on combining safety certification, portability, ecosystem compatibility, and resilient sourcing within one scalable stroller architecture.
Urban mobility is the strongest structural driver as parents increasingly need strollers compatible with apartments, public transport, compact vehicles, and air travel. Advanced travel strollers now weigh approximately 7–8 kg, support child loads near 22 kg, and fold within one second on leading platforms. These specifications materially improve portability compared with heavier conventional systems and increase willingness to purchase secondary travel strollers. Rising airline travel and dense-city living in the United States, United Kingdom, Japan, and South Korea reinforce the shift. Manufacturers are responding with cabin-compatible dimensions, one-hand folding, modular car-seat adapters, larger under-seat storage, and lightweight suspension systems. The strategic insight is that compactness no longer defines a niche travel category; it is becoming a core design requirement influencing mainstream stroller architecture and replacement cycles.
Baby stroller manufacturers face structural pressure from stringent safety testing, concentrated component sourcing, and rising compliance costs. Premium models increasingly require multi-point harnesses, braking systems, structural fatigue validation, chemical compliance, and load testing up to approximately 22 kg. China remains the dominant manufacturing ecosystem, creating exposure to tariffs, freight disruption, and supplier concentration for aluminum tubing, fabrics, wheels, and molded components. Diversifying assembly can raise landed manufacturing costs by roughly 8–15% during early localization phases because new suppliers lack equivalent scale and tooling efficiency. Regulatory changes in Europe also strengthen traceability and online-marketplace accountability. Companies are reducing exposure through dual sourcing, regional warehousing, standardized components, and longer supplier contracts. The operational constraint is balancing compliance, cost, and sourcing resilience without making mid-priced strollers commercially uncompetitive.
Electrification creates a premium mobility opportunity beyond traditional mechanical stroller design. Advanced e-strollers already provide hill assistance on gradients approaching 25%, powered support up to 6 km/h, automated rocking, Bluetooth connectivity, battery monitoring, and selectable operating modes. These capabilities target parents navigating steep cities, long walking routes, airports, and mixed urban terrain. Adoption remains concentrated in premium markets, leaving substantial whitespace for lower-cost assisted platforms during 2026–2028. Manufacturers are investing in compact motors, battery management, regenerative control, app integration, and modular electronic frames. Another opportunity lies in software-enabled functionality: firmware updates and configurable assistance allow brands to improve product capability after purchase. Companies that create interoperable stroller, car-seat, accessory, and digital ecosystems can increase customer retention while reducing reliance on standalone stroller replacement purchases.
The long-term challenge is scaling electronic assistance without compromising mechanical safety, weather resistance, battery reliability, or certification consistency. Powered strollers combine motors, sensors, batteries, braking systems, firmware, and conventional folding hardware, expanding validation complexity by approximately 20–30% compared with fully mechanical products. Systems must maintain controlled assistance around 6 km/h, respond safely on gradients approaching 25%, and continue functioning predictably when batteries are depleted or connectivity fails. Germany and other highly regulated markets raise the qualification threshold for electronic mobility products, while tropical markets add heat, humidity, and water-ingress stress. Manufacturers must invest in redundant braking logic, battery testing, firmware validation, ingress protection, and specialized service networks. The decisive execution issue is lifecycle reliability: premium electronic functionality creates competitive differentiation only when serviceability and mechanical fallback remain dependable throughout years of daily use.
Travel Systems Gain Configuration Depth: Manufacturers are expanding stroller platforms around interchangeable carrycots, infant seats, and car-seat adapters rather than single-purpose frames. A 2025 parent survey found 63% selected travel systems versus 24% choosing newborn-only pushchairs. Brands are standardizing attachment points and expanding 3-in-1 bundles, improving customer retention while reducing separate-product purchasing and simplifying transitions between vehicle and pedestrian mobility.
Air-Travel Portability Drives Redesign: Cabin-oriented strollers increasingly combine one-hand folding, sub-8 kg weight, and compact storage footprints. Leading travel platforms weigh roughly 6–7.5 kg and support children up to approximately 22 kg. Rising international travel is pushing manufacturers toward smaller wheel assemblies, folding hinges, and transport bags. The less-obvious benefit is reduced carton volume, which improves warehouse utilization and lowers e-commerce fulfillment space requirements.
Safety Compliance Reshapes Procurement: Regulatory scrutiny is increasing traceability, testing, and marketplace accountability across juvenile products. U.S. stroller suppliers are simultaneously managing tariff pressure on Chinese imports, where manufacturing remains heavily concentrated. Companies are dual-sourcing fabrics, aluminum components, and molded parts while increasing batch-level documentation. Certification and supplier audit costs are rising, but established brands gain an advantage because compliant product development creates a higher qualification threshold for low-cost entrants.
Circular Materials Enter Premium Platforms: Recycled textiles, solution-dyed fabrics, repairable components, and lower-impact aluminum are moving into premium stroller specifications. Selected manufacturers now use fabrics containing 100% recycled PET in individual components, while modular replacement parts can extend usable product life beyond one child. Brands are redesigning textiles and packaging while strengthening spare-parts programs, turning durability into both a sustainability metric and a mechanism for protecting premium positioning.
Full-Size Strollers account for an estimated 31–34% of type demand, supported by superior storage, suspension, seat adjustability, weather protection, and compatibility with everyday family routines. Their mature installed base keeps replacement volumes high, particularly in the United States and Europe. Lightweight Strollers represent approximately 22–25%, gaining relevance among urban households requiring easier public-transport, apartment, and vehicle storage. Jogging Strollers remain performance-focused, with larger wheels and reinforced suspension supporting active-use requirements.
Travel Systems are the fastest-growing type as parents consolidate stroller and infant car-seat purchasing around interoperable platforms. A 2025 survey of more than 600 parents found 63% selected a travel system, demonstrating strong preference for integrated mobility. Double Strollers remain strategically important for twins and closely spaced siblings despite lower volumes. Manufacturers are responding through universal adapters, one-hand folding mechanisms, lighter frames, and modular seat configurations. Investment is shifting toward common chassis platforms that support multiple configurations, improving manufacturing scale while increasing accessory and replacement-component opportunities.
Daily Travel represents approximately 40–43% of application demand because routine walking, childcare trips, commuting, and neighborhood mobility generate the highest stroller utilization frequency. Shopping accounts for roughly 20–23%, favoring full-size platforms with larger baskets and maneuverable wheel systems. Jogging remains specialized around three-wheel architectures, suspension, and higher-speed stability, while Outdoor Activities support all-terrain wheels, weather protection, and stronger frames for parks, trails, and mixed surfaces.
Travel & Tourism is the fastest-growing application as compact folding and lower stroller weights reduce airport and vehicle handling friction. Modern travel platforms commonly weigh 6–8 kg while supporting approximately 22 kg, narrowing the capability gap with heavier everyday strollers. Manufacturers are adapting through cabin-oriented folding systems, carrying straps, protective transport bags, and smaller folded footprints. Business demand is consequently shifting toward dual-purpose designs capable of handling daily urban use and occasional travel. Common chassis and accessory platforms also reduce SKU complexity while allowing brands to differentiate products through wheels, storage, canopies, and travel-specific attachments.
Parents represent approximately 55–60% of end-user demand because they directly determine stroller configuration, safety features, portability, storage, and accessory requirements. Infants account for the largest age-linked usage base, supporting bassinets, lie-flat seating, and travel-system compatibility during early mobility. Toddlers sustain longer product utilization through seats rated near 22 kg, while Retail Consumers increasingly influence channel economics through online comparison, reviews, promotional purchasing, and bundled travel-system selection.
Retail Consumers are the fastest-changing end-user group as digital purchasing increases specification transparency and price competition. Childcare Centers remain smaller institutional buyers but require durable frames, easy-clean fabrics, multi-child functionality, and dependable braking systems. Manufacturers are responding with parent-focused modular bundles, extended warranties, retailer-exclusive configurations, and replacement accessories. Declining births in mature markets are also increasing the commercial importance of premiumization: fewer births intensify competition for each household purchase, encouraging suppliers to capture more value through accessories, car-seat interoperability, and products that remain usable from infancy into toddlerhood.
Asia-Pacific accounted for the largest market share at 35% in 2025 however, Middle East & Africa is expected to register the fastest growth, expanding at a CAGR of 7.1% between 2026 and 2033.
Premium Travel Systems Reshape Purchasing
North America accounts for approximately 27% of global Baby Stroller demand, with the United States concentrating premium travel-system, lightweight, jogging, and modular stroller purchases. Parents increasingly prioritize infant-car-seat interoperability, one-hand folding, suspension, storage, and products supporting children up to approximately 22 kg. Premium platforms are extending usable life from newborn stages through toddlerhood, improving value per household as U.S. births remain near 3.6 million annually. Safety compliance is also reshaping product development through mandatory structural, restraint, parking-brake, and stability requirements. Brands including UPPAbaby, Nuna, Graco, and Britax compete through modular ecosystems and retailer distribution rather than standalone stroller specifications. Import exposure remains significant, encouraging dual sourcing and inventory diversification. Product investment is moving toward common frames supporting carrycots, car seats, toddler seats, and accessory upgrades.
United States Market Outlook: The United States dominates North American deployment through extensive specialty retail, e-commerce, automobile ownership, and professional child-safety infrastructure. Approximately 3.6 million annual births sustain a substantial replacement and first-purchase base despite demographic moderation. Suppliers increasingly differentiate through certified travel systems, compact vehicle storage, extended warranties, crash-tested compatible car seats, and retailer-exclusive configurations that increase household ecosystem capture.
Urban Mobility Meets Circular Design
Europe represents approximately 24% of global demand, with Germany, the United Kingdom, France, Italy, and the Netherlands supporting strong premium and compact-stroller penetration. Dense cities, public transport, smaller vehicles, and apartment living favor folding platforms weighing approximately 6–9 kg, while mature walking infrastructure supports frequent stroller utilization. The EU General Product Safety Regulation strengthens traceability, recall management, and online-marketplace accountability, raising compliance requirements for imported juvenile products. Sustainability is simultaneously entering premium specifications through recycled fabrics, replaceable wheels, repair programs, and durable modular frames. European brands are expanding refurbishment and spare-parts services to extend product lifecycles rather than competing solely through new-model launches. Electrically assisted platforms also have stronger visibility in hilly and walking-oriented cities, pushing engineering investment toward controlled propulsion, braking redundancy, battery management, and weather-resistant electronics.
Germany Market Outlook: Germany combines strict product-safety expectations with high purchasing power, extensive pedestrian infrastructure, and strong engineering capability. Premium electronic strollers supporting gradients near 25% illustrate the country’s role in assisted-mobility development. German consumers also favor durable, repairable systems, encouraging manufacturers to invest in modular components, replaceable textiles, service infrastructure, and longer-life stroller architectures rather than disposable product cycles.
Manufacturing Scale Supports Product Diversification
Asia-Pacific holds approximately 35% of global demand and dominates stroller manufacturing through China’s integrated juvenile-product supply chain. Guangdong, Zhejiang, Jiangsu, and neighboring clusters combine aluminum fabrication, plastic injection molding, textile production, wheels, tooling, and final assembly, allowing rapid movement from design to scaled output. China recorded 9.54 million births in 2024, while India added a substantially larger annual birth cohort, sustaining broad entry-level and mid-market requirements. Japan, South Korea, Singapore, and Australia concentrate stronger demand for lightweight, compact, and premium travel platforms. Tariff exposure and geopolitical supply-chain restructuring are directing selected final assembly toward Vietnam and other Southeast Asian locations, although Chinese component ecosystems remain difficult to replicate. Manufacturers are responding with automated frame production, common chassis architectures, localized e-commerce portfolios, and export-focused safety certification.
China Market Outlook: China remains the region’s decisive manufacturing hub, combining a 9.54-million-birth domestic base with global OEM and ODM capabilities. Guangdong’s juvenile-products ecosystem gives manufacturers access to integrated metalworking, fabrics, molded components, wheels, and packaging. This supplier density supports shorter development cycles and allows international brands to customize frames, canopies, folding systems, and accessories without establishing vertically integrated factories.
Urban Retail Expands Modular Adoption
South America accounts for approximately 8% of global Baby Stroller demand, led by Brazil, Argentina, Chile, and Colombia. Brazil provides the largest deployment base through dense metropolitan populations, shopping-center retail, marketplaces, and a sizable domestic juvenile-products industry. Urban consumers increasingly favor travel systems and lightweight strollers that fit compact vehicles and apartment storage, while price sensitivity maintains strong demand for durable full-size platforms. Import duties and currency volatility raise landed costs for European and U.S. premium brands, creating opportunities for Brazilian manufacturers and regional distributors. Localized assembly can reduce exposure to imported finished-product tariffs while retaining selected Asian components. Companies are expanding marketplace distribution, installment-payment options, car-seat bundles, and retailer partnerships. Infrastructure variation outside major cities keeps all-terrain wheels, durable frames, and larger suspension systems relevant alongside compact urban configurations.
Brazil Market Outlook: Brazil anchors regional demand through more than 2.3 million annual births and a substantial domestic baby-products retail network. Local manufacturers benefit from established plastics, textiles, and metalworking capabilities, while São Paulo provides the strongest premium distribution concentration. Suppliers balancing localized production with imported safety components can compete more effectively against fully imported systems exposed to currency and duty volatility.
Urban Development Expands Mobility Demand
Middle East & Africa represents approximately 6% of global demand, with Saudi Arabia, the United Arab Emirates, South Africa, Egypt, and high-birth African economies creating distinctly different purchasing environments. Gulf markets favor premium travel systems, compact folding platforms, and high-specification imported brands, supported by malls, airports, hospitality infrastructure, and automobile-dependent households. Saudi Arabia’s tourism and urban-development programs are expanding pedestrian destinations and family-oriented infrastructure, while the UAE provides a premium retail gateway. African markets remain more price-sensitive and fragmented, making durability, wheel strength, repairability, and distributor coverage decisive. Import dependence creates freight and currency exposure, encouraging suppliers to establish regional warehouses and local distribution partnerships. Brands are also adapting fabrics, ventilation, and canopy protection for hot climates while differentiating products through larger storage and all-terrain functionality.
Saudi Arabia Market Outlook: Saudi Arabia offers the strongest transformation-led opportunity through large urban projects, expanding tourism infrastructure, and a young family demographic. The country targets 150 million annual visitors by 2030, supporting investments in pedestrian destinations, airports, retail centers, and hospitality environments. Premium stroller suppliers are strengthening distributor relationships and climate-adapted product portfolios suited to automobile-to-destination family mobility.
Goodbaby, Newell Brands, Artsana, UPPAbaby, and Bugaboo compete across mass, premium, and travel-system segments, while CYBEX-led technology platforms pressure conventional mechanical designs. The top five groups control approximately 38–43% of global demand. Goodbaby leverages manufacturing scale, while UPPAbaby and Bugaboo emphasize modularity, design, and premium ecosystems; mass-market suppliers compete through distribution and pricing. Lightweight architectures reduce stroller weight by 20–30%, compact folds cut storage volume by roughly 25%, and integrated travel systems extend usable configurations from 2 to 5 stages. Players are expanding car-seat interoperability, direct retail, electronic assistance, recycled materials, and regional sourcing. Competition is shifting from standalone strollers toward configurable mobility ecosystems with accessories and replacement components. Safety certification, tooling, liability exposure, dealer access, and reliable folding mechanisms create substantial entry pressure. Winning requires certified safety, scalable manufacturing, differentiated portability, modular compatibility, dependable after-sales support, and channel-specific pricing without sacrificing durability or ergonomic performance.
Goodbaby International
Newell Brands
Artsana Group
UPPAbaby
Bugaboo
Britax Römer
Dorel Juvenile
Silver Cross
Stokke
Peg Perego
Nuna
Thule Group
Baby Jogger
Joolz
Current stroller technology centers on lightweight aluminum frames, one-hand folding, modular travel systems, suspension tuning, magnetic harnesses, and car-seat interoperability. Modern compact platforms globally weighing 6–8 kg improve carrying efficiency by roughly 20–30% versus traditional full-size designs, while modular chassis supporting three or more configurations reduce separate-product purchasing. Adoption is strongest across premium urban and travel categories, giving ecosystem-focused brands stronger accessory retention.
Emerging systems integrate electric propulsion, hill assistance, automated rocking, Bluetooth connectivity, battery monitoring, and sensor-managed braking. Electrically assisted platforms can support gradients near 25%, reducing pushing effort on steep terrain by approximately 20–25%. Compared with legacy mechanical strollers, app-connected systems add software-controlled functions without changing core seating architecture. Premium brands, technology specialists, and urban-focused manufacturers benefit most because differentiation shifts from styling toward measurable mobility performance.
From 2026–2028, disruptive development will concentrate on lighter composite structures, smarter braking, predictive terrain sensing, recyclable textiles, and interoperable stroller-car-seat ecosystems. Automated frame welding, digital quality inspection, and standardized modular components can improve manufacturing consistency by 5–10% while reducing SKU complexity. Companies investing now in electronics validation, battery safety, repairable architectures, and common chassis platforms will gain operational advantages as portability, assisted mobility, sustainability, and lifecycle serviceability become decisive purchasing criteria.
September 2024 — UPPAbaby announced Vista V3 rollout, offering more than 30 customization configurations and capacity for up to three children across stages. The modular platform strengthened lifecycle positioning while de-bundling accessories improved purchase flexibility and configuration choice.
March 2025 — Bugaboo released Fox 5 Renew, a 12.4-kg all-terrain travel system with a 10-kg storage basket and one-hand adjustments. The redesign combined premium mobility with more sustainable materials, strengthening Bugaboo’s positioning in durable, high-specification stroller platforms. Source: which.co.uk
September 2025 — UPPAbaby cut Vista V3 pricing from $1,199.99 to $999.99 after tariff-driven increases, a 16.7% reduction. Supply-chain adjustments enabled the company to restore affordability without changing product quality, directly countering tariff pressure in premium baby gear. Source: uppababy.com
June 2026 — Joolz recalled about 3,840 Aer2 car-seat adapters after attachment failures created fall hazards. The U.S. safety action exposed interoperability risk in modular travel systems and increased pressure for stronger adapter validation, traceability, and post-market controls. Source: cpsc.gov
The Baby Stroller Market report covers Full-Size Strollers, Lightweight Strollers, Jogging Strollers, Travel Systems, and Double Strollers across Daily Travel, Shopping, Jogging, Travel & Tourism, and Outdoor Activities. End-user analysis spans Infants, Toddlers, Parents, Childcare Centers, and Retail Consumers, with parents representing approximately 55–60% of demand. Technology coverage includes one-hand folding, lightweight frames, modular car-seat integration, electric assistance, connected controls, and advanced braking systems.
Regional assessment covers North America, Europe, Asia-Pacific, South America, and Middle East & Africa, including country-level manufacturing, safety regulation, retail distribution, and mobility patterns. The report also evaluates compact travel platforms, assisted strollers, recyclable materials, and interoperable accessory ecosystems. The 2026–2033 framework supports investment planning, supplier diversification, product positioning, geographic expansion, partnership strategy, and competitive benchmarking as manufacturers prioritize portability, safety validation, modularity, and lifecycle serviceability.
| Report Attribute/Metric | Report Details |
|---|---|
Market Revenue in 2025 | USD 4800 Million |
Market Revenue in 2033 | USD 7478.95 Million |
CAGR (2026 - 2033) | 5.7% |
Base Year | 2025 |
Forecast Period | 2026 - 2033 |
Historic Period | 2021 - 2025 |
Segments Covered | By Type
By Application
By End-User
|
Key Report Deliverable | Revenue Forecast, Growth Trends, Market Dynamics, Segmental Overview, Regional and Country-wise Analysis, Competition Landscape |
Region Covered | North America, Europe, Asia-Pacific, South America, Middle East, Africa |
Key Players Analyzed | Goodbaby International, Newell Brands, Artsana Group, UPPAbaby, Bugaboo, Britax Römer, Dorel Juvenile, Silver Cross, Stokke, Peg Perego, Nuna, Thule Group, Baby Jogger, Joolz |
Customization & Pricing | Available on Request (10% Customization is Free) |




