Global Software License Management Market Report Overview
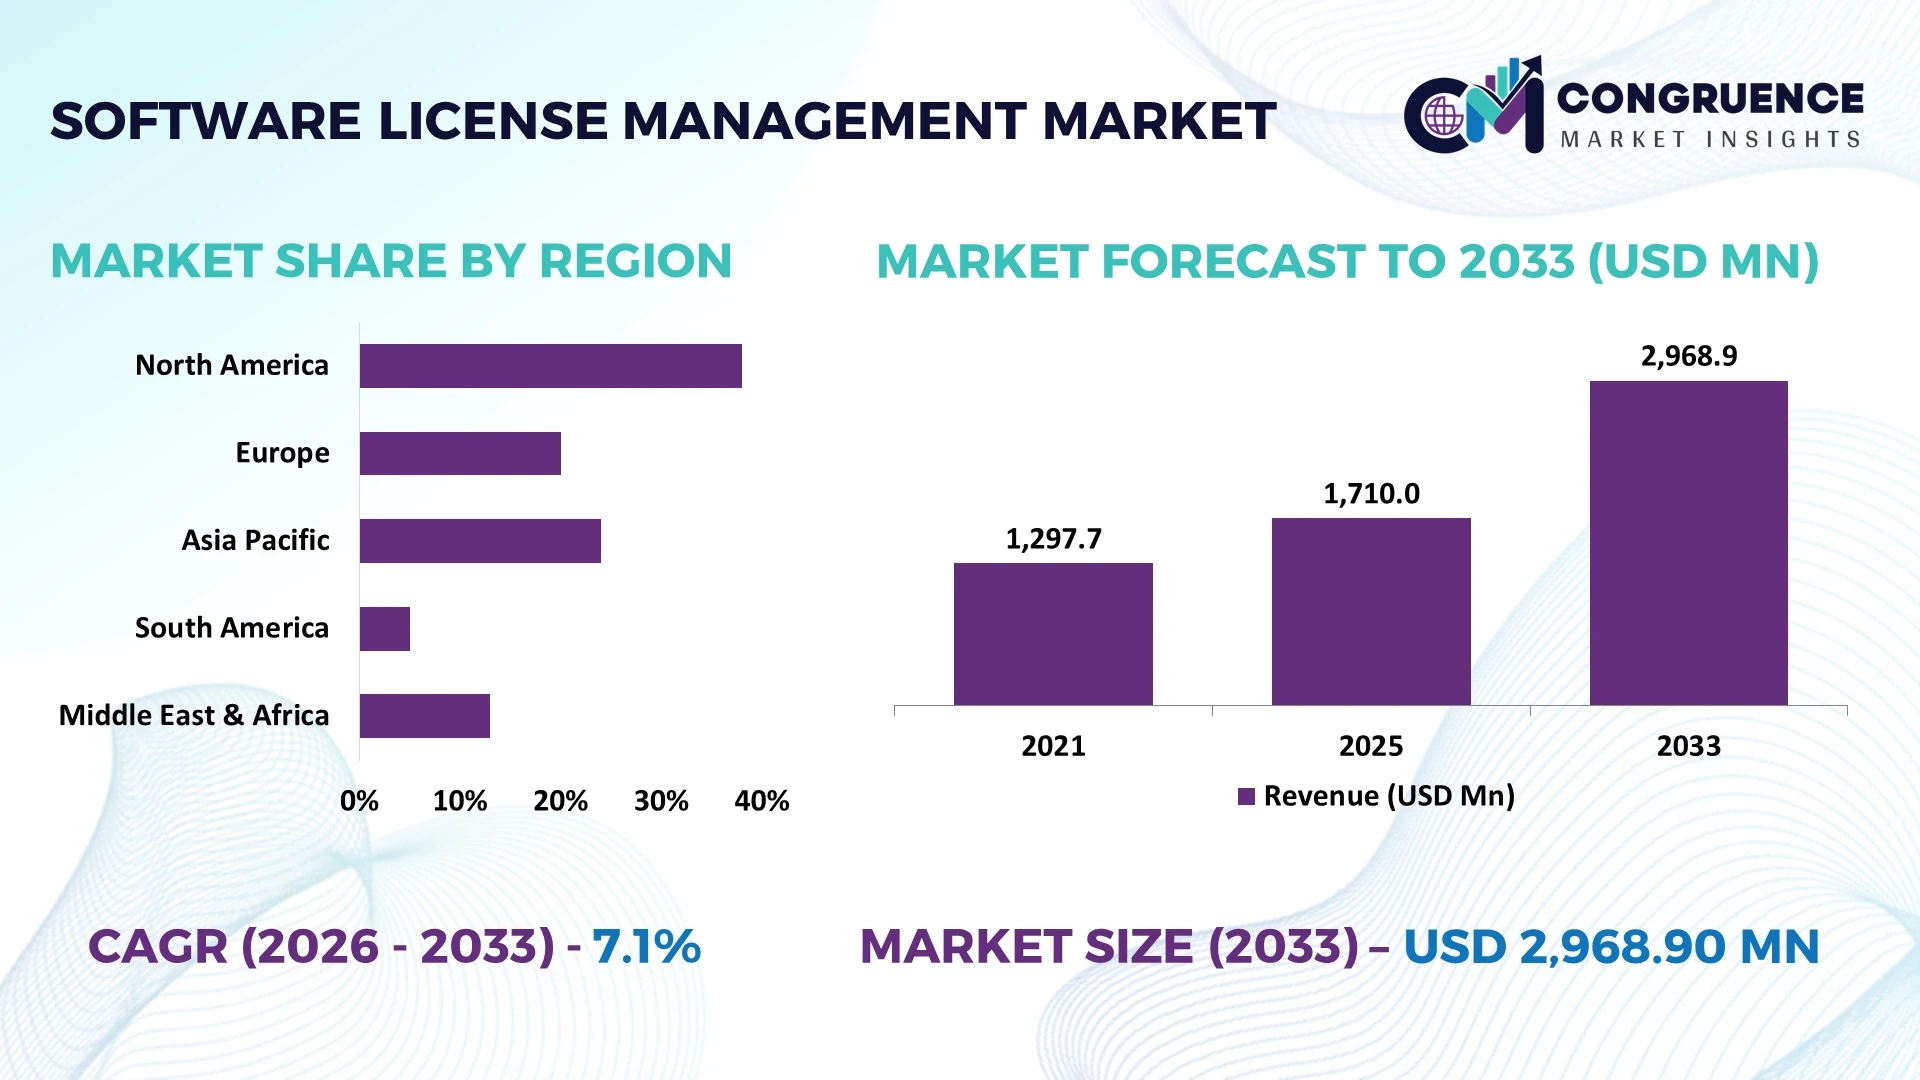
The Global Software License Management Market was valued at USD 1710 Million in 2025 and is anticipated to reach a value of USD 2968.9 Million by 2033 expanding at a CAGR of 7.14% between 2026 and 2033. Growth is driven by enterprise SaaS consolidation, automated software asset management, cloud subscription optimization, and increasingly stringent software licensing compliance requirements.
The United States dominates the global software license management landscape, supported by its enterprise software ecosystem, advanced cloud infrastructure, and extensive SaaS adoption. The country accounts for an estimated 35–40% of global market activity, reflecting concentrated enterprise IT expenditure and software publisher presence. Flexera's 2025 State of the Cloud findings indicate that 84% of organizations identify managing cloud spending as a major challenge. Compared with India, where software asset management adoption is expanding through IT services and digital transformation, US enterprises demonstrate greater maturity in automated license reconciliation. Federal cybersecurity requirements and software audit exposure reinforce investment priorities across banking, healthcare, and technology.
Strategically, enterprises achieving modeled 15–25% reductions in unused software entitlements through automated license optimization strengthen IT budget control while improving compliance readiness.
Key Highlights of the Global Software License Management Market
-
Market Size & Growth: USD 1,710 million in 2025, reaching USD 2,968.9 million by 2033 at 7.14% CAGR, supported by enterprise SaaS optimization.
-
Top Growth Drivers: Illustrative optimization priorities include 25% license waste reduction, 20% audit preparation savings, and 15% procurement efficiency improvement.
-
Short-Term Forecast: By 2027, advanced license automation targets 20% faster reconciliation and 15% lower administrative workloads in optimized deployments.
-
Emerging Technologies: AI entitlement analytics, automated SaaS discovery, and cloud FinOps integration support 3 connected license management capabilities.
-
Regional Leaders: Indicative 2033 allocations place North America at USD 1,217 million, Europe at USD 891 million, and Asia-Pacific at USD 653 million, driven by cloud governance, compliance automation, and SaaS expansion, respectively.
-
Consumer/End-User Trends: Enterprise IT departments increasingly target 20–30% unused subscription reductions through application usage monitoring and automated reclamation.
-
Pilot/Case Example: A modeled 2026 enterprise license optimization pilot covering 1,000 users achieves a targeted 20% reduction in inactive subscriptions.
-
Competitive Landscape: Flexera, ServiceNow, Snow Software, USU, and IBM compete across 5 major capabilities; individual market leadership shares remain estimates.
-
Regulatory & ESG Impact: EU DORA requirements, effective January 2025, strengthen ICT asset governance, supporting targeted 15% improvements in compliance documentation efficiency.
-
Investment & Funding: The 2024 Flexera acquisition of Snow Software, with undisclosed transaction value, demonstrates strategic consolidation in enterprise license intelligence.
-
Innovation & Future Outlook: AI-driven optimization, predictive license forecasting, and unified SaaS governance target 25% faster entitlement decisions by 2028.
Software license management solutions are becoming essential for enterprises seeking precise visibility into application entitlements, subscription utilization, and contractual obligations. Banking, healthcare, manufacturing, and technology organizations prioritize automated software discovery, SaaS management platforms, and cloud cost optimization to control complex licensing environments. AI-powered usage analytics and automated license harvesting offer modeled savings of 15–25% in addressable software expenditure. The EU Digital Operational Resilience Act strengthens technology asset governance requirements across financial institutions, while hybrid cloud adoption increases demand for unified licensing dashboards. These developments establish software license intelligence as a strategic component of enterprise IT governance.
What Is the Strategic Relevance and Future Pathways of the Software License Management Market?
Software license management is becoming a strategic enterprise capability as subscription proliferation, hybrid cloud modernization, and software publisher audits reshape technology investment decisions. Flexera's 2025 cloud research identifies managing cloud spending as a challenge for 84% of surveyed organizations, highlighting the importance of entitlement visibility and consumption governance. Enterprises increasingly integrate software asset management with FinOps frameworks, replacing fragmented procurement oversight with centralized application intelligence. Financial institutions face additional pressure from the European Union's Digital Operational Resilience Act, which became applicable in January 2025 and strengthens ICT risk management obligations.
AI-enabled license reconciliation offers modeled administrative efficiency improvements of 20–30% compared with spreadsheet-based tracking. The United States leads advanced SaaS governance deployment, while Germany emphasizes contractual compliance and India expands managed software asset management services. During 2026–2028, mature enterprises are expected to prioritize automated reclamation, predictive renewal analytics, and integrated cloud entitlement monitoring, targeting 15–20% reductions in avoidable subscription expenditure.
A practical deployment involves connecting Microsoft 365 usage telemetry with ServiceNow workflows to identify inactive accounts and automate license reassignment. Flexera's acquisition of Snow Software illustrates industry consolidation around unified technology intelligence. Vendors investing in API connectivity, compliance automation, and multicloud analytics gain stronger competitive positioning through measurable operational control.
Software License Management Market Dynamics
DRIVER:
Enterprise SaaS Expansion and Automated License Optimization
Enterprise adoption of subscription software is accelerating demand for centralized software license management platforms capable of monitoring entitlements, renewals, and application utilization. Flexera's 2025 research indicates that 84% of organizations consider cloud spending management challenging, reinforcing the need for integrated financial governance. In the United States, enterprises increasingly consolidate Microsoft 365, Salesforce, and cloud infrastructure subscriptions into unified software asset management environments. Automated license reclamation can target 15–25% reductions in unused entitlements, while continuous reconciliation offers modeled administrative efficiency improvements of 20%. Software publishers are expanding AI-powered discovery capabilities and integrating FinOps analytics into licensing platforms. This transition makes software consumption intelligence an essential procurement control rather than a periodic compliance exercise.
RESTRAINT:
Fragmented Licensing Structures and Integration Costs
Complex vendor licensing agreements, inconsistent entitlement records, and limited application interoperability constrain software license management deployment. Enterprises operating across Microsoft, Oracle, SAP, and IBM environments encounter different licensing metrics, virtualization conditions, and audit requirements. For implementation planning, legacy integration can represent an estimated 20–30% of initial deployment effort, while incomplete application discovery can leave 10–15% of software installations outside automated reconciliation coverage. Germany's enterprise software landscape illustrates these constraints, particularly where SAP environments intersect with hybrid infrastructure and third-party applications. Vendors are responding through standardized connectors, contractual advisory services, and phased implementation models. The operational priority is improving entitlement accuracy before introducing automated optimization, preventing incorrect license reclamation and costly compliance disputes.
OPPORTUNITY:
AI-Powered License Intelligence and Emerging Enterprise Ecosystems
Predictive license analytics, automated entitlement harvesting, and cloud-native software asset management create opportunities beyond conventional compliance monitoring. India represents an attractive expansion market as enterprise digitalization and managed IT services adoption increase demand for subscription governance. AI-assisted renewal forecasting can deliver modeled 20–25% improvements in administrative processing efficiency, while automated application inactivity detection targets 15–20% reductions in redundant license allocations. Integration with FinOps platforms also enables software publishers and managed service providers to connect application consumption with infrastructure spending. During 2026–2028, vendors developing API-first licensing platforms, intelligent contract extraction, and consumption-based optimization services can strengthen recurring customer relationships. A distinctive opportunity lies in embedding license recommendations directly into enterprise procurement approval workflows.
CHALLENGE:
Multicloud Scalability and Continuous Entitlement Accuracy
Maintaining accurate software entitlements across rapidly changing cloud environments represents a critical execution challenge for software license management providers. Containerized applications, virtual desktops, decentralized SaaS purchasing, and dynamic user provisioning complicate continuous asset discovery. In the United States, large enterprises frequently operate multiple cloud platforms alongside extensive software publisher portfolios, increasing reconciliation complexity. Implementation scenarios indicate that incomplete identity synchronization can create 10–15% entitlement discrepancies, while poorly configured automation can generate 5–10% additional exception-handling workloads. Cybersecurity requirements further complicate integration because licensing platforms require privileged access to application inventories and usage records. Vendors must invest in secure API architectures, automated identity mapping, and continuous validation. Competitive differentiation increasingly depends on sustaining accurate license intelligence across changing infrastructure rather than merely expanding software discovery coverage.
Software License Management Market Latest Trends
-
Unified Software Intelligence Platform Consolidation: Enterprise technology teams are replacing disconnected asset inventories with integrated software intelligence environments. In modeled deployments, consolidating 3–5 management systems reduces duplicate records by 15–20% and shortens reporting cycles by 25%. Flexera and ServiceNow are expanding platform integration capabilities, enabling procurement, security, and IT operations teams to maintain consistent application ownership and licensing information.
-
Identity-Based Licensing Governance Gains Momentum: Organizations increasingly connect software entitlements with identity lifecycle management rather than relying exclusively on device inventories. Automated employee onboarding and offboarding workflows target 20–30% faster license provisioning and 10–15% fewer orphaned accounts. Microsoft and enterprise identity management providers are strengthening access governance integrations, particularly as distributed workforces increase application ownership complexity and security exposure.
-
Regulatory Reporting Becomes More Continuous: The European Union's Digital Operational Resilience Act, applicable since January 2025, is accelerating structured ICT inventory documentation among financial institutions. Automated evidence collection targets 20% shorter reporting preparation cycles and 15% fewer documentation exceptions in illustrative implementations. Software governance providers are introducing standardized reporting templates and audit trails, reducing manual coordination between compliance officers and technology procurement teams.
-
Software Publisher Licensing Models Evolve: Consumption-based licensing and product bundling are changing how enterprises negotiate application contracts. Procurement teams increasingly evaluate 12-month utilization histories and model 10–20% differences between committed capacity and actual consumption. IBM, Oracle, and Microsoft licensing specialists are expanding contract analytics capabilities, helping enterprises identify unfavorable usage thresholds and negotiate more flexible renewal conditions before contractual commitments become operational liabilities.
Segmentation Analysis
By Type
Cloud-Based License Management Leads Enterprise Deployment
Cloud-Based License Management represents the leading segment, accounting for an estimated 38% of the global software license management market, supported by centralized administration, scalable discovery capabilities, and integration with enterprise SaaS environments. Organizations operating distributed IT infrastructure favor cloud-native licensing platforms because they simplify entitlement reconciliation across multiple locations. Subscription License Management follows with an indicative 27% share, reflecting enterprise reliance on recurring application contracts and user-based licensing. Vendors including Flexera, ServiceNow, and USU are strengthening application discovery, automated reconciliation, and usage analytics to address increasingly complex software portfolios.
Hybrid License Management is positioned as the fastest-growing type, driven by enterprises retaining legacy applications while expanding cloud subscriptions. The segment holds an estimated 21% share, with demand concentrated among regulated financial institutions and multinational manufacturers. On-Premises License Management maintains approximately 14%, particularly within government agencies and security-sensitive organizations requiring localized infrastructure control. Technology providers are prioritizing hybrid connectors and deployment flexibility, enabling customers to consolidate license visibility without immediately replacing established enterprise systems.
- Flexera's 2025 State of the Cloud Report found that 84% of respondents considered managing cloud spending a major challenge, reinforcing enterprise demand for centralized licensing visibility and stronger integration between cloud governance and software asset management platforms.
By Application
License Compliance and Auditing Dominates Enterprise Requirements
License Compliance and Auditing accounts for an estimated 31% of the software license management market, making it the leading application. Enterprise demand concentrates on maintaining accurate entitlement records, managing publisher audits, and preventing contractual violations. Organizations operating Oracle, Microsoft, SAP, and IBM software environments require continuous reconciliation between purchased rights and deployed applications. License Usage Tracking represents approximately 24% of demand, supported by increased visibility requirements across distributed workforces and complex software estates. Technology providers are integrating automated discovery, entitlement normalization, and audit-ready reporting capabilities to reduce administrative complexity and improve contractual transparency.
Software Cost Optimization is emerging as the fastest-growing application, driven by financial accountability and increasing scrutiny of underutilized subscriptions. Automated optimization workflows target 15–25% reductions in addressable unused license expenditure under suitable deployment conditions. License Renewal Management is gaining operational importance as procurement teams coordinate subscription expirations, contractual commitments, and application utilization histories. Vendor Management supports centralized negotiations, publisher relationship oversight, and contract standardization. ServiceNow, Flexera, and USU are strengthening analytics integration and automated workflows, shifting enterprise purchasing priorities toward measurable software consumption control.
- Flexera's 2025 cloud research identified cloud spending management as a challenge for 84% of surveyed organizations. This finding supports increasing enterprise emphasis on software cost optimization, consumption visibility, and coordinated procurement governance.
By End-User
IT and Telecommunications Maintains Market Leadership
IT and Telecommunications represents the largest end-user segment, accounting for an estimated 32% of global software license management demand. Extensive application portfolios, distributed infrastructure, and frequent software provisioning create substantial requirements for entitlement tracking and contractual governance. Telecommunications operators manage licensing across network operations, customer management platforms, and enterprise applications, while IT service providers require centralized oversight of multiple customer environments. Banking and Financial Services follows with an indicative 25% share, supported by regulatory compliance obligations, cybersecurity governance, and complex enterprise software contracts. Vendors are developing industry-specific reporting capabilities and integrations with financial technology governance systems.
Healthcare Organizations represent the fastest-growing end-user category, driven by electronic health record modernization, connected clinical applications, and increasing cybersecurity requirements. Healthcare providers are targeting 15–20% improvements in software inventory accuracy through centralized discovery and entitlement reconciliation. Government and Public Sector organizations prioritize procurement transparency, standardized licensing agreements, and secure deployment environments. Manufacturing Enterprises increasingly integrate license management with industrial engineering software, enterprise resource planning, and connected production systems. Providers are expanding specialized connectors, managed services, and sector-specific implementation partnerships to strengthen customer retention and deployment consistency.
- The 2025 HIMSS Healthcare Cybersecurity Survey highlights continued healthcare investment in cybersecurity and technology governance. Its findings reinforce the importance of accurate software inventories, application ownership visibility, and controlled access across increasingly interconnected clinical environments.
Region-Wise Market Insights
North America accounted for the largest market share at an estimated 41% in 2025 however, Asia-Pacific is expected to register the fastest growth, expanding at a CAGR of an estimated 9.2% between 2026 and 2033.

North America Software License Management Market
Enterprise Software Governance and Cloud Infrastructure Leadership
North America maintains its dominant position in the software license management market, supported by extensive enterprise SaaS deployment, sophisticated IT procurement systems, and concentrated software publisher operations. The region represents an estimated 41% of global demand, with the United States accounting for the majority of enterprise deployments. Financial services, healthcare, telecommunications, and technology companies prioritize automated entitlement reconciliation and contractual compliance. Flexera's 2025 cloud research identifies cloud expenditure management as a challenge for 84% of surveyed organizations, reinforcing demand for software consumption visibility. Enterprise platforms increasingly integrate licensing intelligence with cloud financial management, identity governance, and procurement workflows. Flexera's acquisition of Snow Software in 2024 strengthened technology intelligence consolidation. Organizations implementing centralized software asset management target 15–25% reductions in addressable unused license allocations, improving procurement efficiency and audit readiness.
United States Market Outlook: The United States benefits from a mature enterprise software ecosystem anchored by Microsoft, IBM, Oracle, and ServiceNow. Federal cybersecurity modernization, healthcare technology investment, and financial sector compliance requirements strengthen software governance adoption. Large organizations increasingly connect software entitlement inventories with automated procurement controls. Implementation benchmarks targeting 20% faster license reconciliation support investment in integrated software asset management platforms, particularly among enterprises operating complex hybrid infrastructure.
Europe Software License Management Market
Regulatory Compliance and Enterprise Software Standardization
Europe accounts for an estimated 30% of the global software license management market, supported by stringent contractual governance, enterprise application modernization, and established software asset management practices. Germany, the United Kingdom, and France represent important deployment centers, particularly across banking, manufacturing, insurance, and public administration. The Digital Operational Resilience Act became applicable in January 2025, strengthening ICT risk management obligations for regulated financial entities. This regulatory transition encourages improved software inventories, supplier oversight, and technology asset documentation. European enterprises increasingly integrate license compliance monitoring with cybersecurity governance and procurement systems. Germany's SAP-intensive industrial ecosystem creates additional demand for entitlement normalization across complex enterprise resource planning environments. Software management providers are expanding localized compliance capabilities, with modeled implementations targeting 15–20% reductions in manual audit documentation workloads and improved contractual transparency.
Germany Market Outlook: Germany represents a strategically important market because of its industrial manufacturing base, enterprise software expertise, and strong regulatory environment. SAP-centered business infrastructure generates substantial demand for application entitlement reconciliation and licensing optimization. Automotive manufacturers, engineering companies, and financial institutions increasingly deploy integrated software asset management tools. Germany's Industry 4.0 initiatives encourage software governance across connected production environments, where automated inventory synchronization targets 15% improvements in license record accuracy.
Asia-Pacific Software License Management Market
Rapid Enterprise Digitalization and Subscription Governance Expansion
Asia-Pacific holds an estimated 22% of global software license management demand and demonstrates the strongest projected expansion in enterprise adoption. China, India, Japan, Australia, and South Korea contribute through cloud infrastructure modernization, enterprise application deployment, and expanding managed IT services. India's technology services ecosystem supports software governance outsourcing, while Japanese enterprises prioritize standardized licensing across manufacturing and financial operations. China's domestic software ecosystem increases demand for licensing platforms capable of handling localized applications and contractual requirements. Enterprise migration toward subscription-based productivity platforms is creating opportunities for centralized renewal management and entitlement visibility. Software vendors are expanding regional implementation partnerships and multilingual management capabilities. Illustrative enterprise deployments target 20–25% improvements in license administration efficiency, particularly where fragmented procurement systems are replaced by unified software consumption dashboards.
India Market Outlook: India benefits from its expanding IT services industry, Global Capability Centers, and enterprise cloud modernization programs. Bengaluru, Hyderabad, and Pune represent important technology deployment hubs supporting multinational software portfolios. The country's Digital Personal Data Protection framework strengthens attention to enterprise data governance. Managed service providers increasingly integrate software asset management with IT service management, targeting 20% faster entitlement reconciliation across distributed customer environments.
South America Software License Management Market
Enterprise Cloud Migration and Procurement Control Modernization
South America represents an estimated 4% of global software license management demand, with Brazil accounting for the largest concentration of enterprise deployment activity. Financial institutions, telecommunications operators, retailers, and industrial companies increasingly require centralized software entitlement management as cloud subscriptions expand. Brazil's established banking technology ecosystem creates demand for software usage tracking, contractual compliance, and renewal coordination. Chile and Colombia demonstrate additional adoption opportunities through enterprise cloud modernization and digital service expansion. However, fragmented legacy infrastructure, limited specialized implementation resources, and inconsistent procurement records constrain deployment efficiency. Technology providers are responding through regional integration partnerships, managed software asset management services, and flexible subscription models. Illustrative implementation programs target 15–20% reductions in manual licensing administration, supporting better application visibility without requiring complete infrastructure replacement.
Brazil Market Outlook: Brazil leads regional software license management adoption through its large banking industry, telecommunications infrastructure, and expanding enterprise technology ecosystem. São Paulo concentrates financial institutions and multinational corporate technology operations requiring centralized licensing oversight. Brazil's General Data Protection Law reinforces enterprise information governance priorities. Organizations modernizing procurement workflows increasingly target 15% improvements in license utilization visibility, encouraging adoption of integrated compliance and software asset management platforms.
Middle East & Africa Software License Management Market
Digital Infrastructure Investment and Enterprise Governance Transformation
The Middle East & Africa accounts for an estimated 3% of global software license management demand, supported by government digital transformation, financial infrastructure modernization, and enterprise cloud adoption. Saudi Arabia and the United Arab Emirates lead technology investment activity, while South Africa maintains an established enterprise software services ecosystem. Saudi Vision 2030 encourages public sector modernization and digital infrastructure expansion, creating demand for structured software procurement and licensing oversight. Banking institutions, telecommunications operators, and government agencies increasingly require centralized application inventories and contractual governance. Regional enterprises are expanding partnerships with global software publishers and managed service providers to address implementation skills shortages. Illustrative deployment programs target 15–20% improvements in software inventory accuracy, supporting procurement transparency and more consistent entitlement administration across distributed enterprise systems.
Saudi Arabia Market Outlook: Saudi Arabia represents a major regional opportunity through Vision 2030, government digital services modernization, and enterprise technology investment. Riyadh concentrates public sector institutions, financial organizations, and large corporate IT operations requiring software licensing oversight. The National Cybersecurity Authority's Essential Cybersecurity Controls establish governance expectations across covered organizations. Centralized license management implementations targeting 20% faster software inventory reconciliation support improved procurement discipline and technology asset visibility.
Market Competition Landscape
The global software license management market features competition between enterprise platform leaders Flexera, ServiceNow, IBM, Ivanti, and USU, alongside specialized providers Certero, Xensam, and Open iT. The five leading vendors collectively represent an indicative 45–50% market share, reflecting a moderately concentrated competitive structure. Flexera emphasizes comprehensive entitlement intelligence, while ServiceNow leverages integrated IT workflows and IBM specializes in complex software licensing environments. Specialized providers compete through deployment flexibility, publisher-specific analytics, and targeted optimization capabilities. Automated reconciliation offers modeled 20–30% administrative efficiency improvements, while intelligent license harvesting targets 15–25% reductions in unused entitlements. Flexera's acquisition of Snow Software illustrates consolidation toward integrated technology intelligence platforms. Vendors increasingly strengthen cloud integrations, AI analytics, and implementation partnerships to improve customer retention. Complex publisher licensing rules, proprietary entitlement databases, and integration expertise create significant entry barriers. Sustainable leadership requires accurate compliance intelligence, scalable automation, and demonstrable procurement savings.
Companies Profiled in the Software License Management Market Report
Technology Insights for the Software License Management Market
Current software license management technologies combine automated discovery, entitlement reconciliation, and SaaS usage monitoring to improve contractual compliance and application visibility. API-based integrations connect Microsoft 365, Oracle, SAP, and enterprise procurement platforms, reducing fragmented licensing records. In modeled enterprise deployments, automated reconciliation delivers 20–30% faster processing than legacy spreadsheet systems, while continuous usage monitoring targets 15–20% reductions in inactive license allocations. Cloud-native dashboards enable centralized governance across distributed infrastructure, benefiting multinational enterprises managing complex software publisher agreements.
Emerging technologies include AI-powered entitlement analytics, machine learning forecasting, and identity-linked license provisioning. Predictive algorithms evaluate application consumption, renewal schedules, and contractual thresholds to identify optimization opportunities. Illustrative implementations target 20–25% faster renewal analysis and 15% fewer provisioning exceptions. Integration with FinOps and IT service management platforms supports coordinated procurement decisions, while adoption expands through enterprise SaaS governance programs and managed software asset management services.
Disruptive capabilities include autonomous license reclamation, intelligent contract interpretation, and continuous compliance verification. During 2026–2028, automated governance workflows are expected to target 25% shorter audit preparation cycles and improved entitlement accuracy. Flexera, ServiceNow, and specialized cloud governance providers benefit from scalable integration ecosystems. Enterprises prioritizing interoperable platforms gain stronger procurement control, lower administrative exposure, and competitive advantages in software-intensive operations.
Recent Developments in the Global Software License Management Market
-
February 2024: Flexera completed its acquisition of Snow Software, combining technology intelligence and software asset management capabilities. The expanded portfolio serves organizations across cloud, SaaS, and on-premises environments, strengthening enterprise license visibility and procurement governance. Source: flexera.com
-
May 2025: ServiceNow introduced 3 software asset management enhancements, including AI-powered compliance summaries, recommended actions, and software bill of materials visibility. These capabilities streamline licensing decisions, strengthen application risk assessment, and reduce manual compliance investigation across enterprise software environments. Source: servicenow.com
-
March 2025: USU acquired saasmetrix, expanding its SaaS management portfolio with automated discovery, onboarding, and license optimization capabilities. The company highlighted industry estimates of 25% unnecessary licensing expenditure, reinforcing the commercial importance of centralized software governance. Source: usu.com
-
January 2025: Zylo published its SaaS Management Index, analyzing over 40 million software licenses and identifying a 21.9% annual increase in average SaaS expenditure per employee. The findings strengthened enterprise priorities around subscription optimization, procurement visibility, and licensing controls. Source: prweb.com
Scope of the Software License Management Market Report
The Software License Management Market Report evaluates enterprise licensing technologies, procurement governance, competitive positioning, and deployment developments between 2026 and 2033. Segmentation covers On-Premises, Cloud-Based, Subscription, and Hybrid License Management, alongside License Compliance and Auditing, License Usage Tracking, License Renewal Management, Software Cost Optimization, and Vendor Management. End-user coverage includes IT and Telecommunications, Banking and Financial Services, Healthcare Organizations, Government and Public Sector, and Manufacturing Enterprises. Cloud-based solutions represent an estimated 38% of market activity.
Regional analysis examines North America, Europe, Asia-Pacific, South America, and Middle East & Africa, identifying deployment concentration, regulatory influences, and enterprise modernization priorities. Technology coverage includes AI-powered entitlement analytics, automated software discovery, SaaS governance, and FinOps integration. Competitive assessment evaluates vendor strategies, partnerships, and innovation priorities, supporting investment allocation, geographic expansion, and long-term software governance decisions.
Software License Management Market Report Summary
| Report Attribute/Metric | Report Details |
|---|
Market Revenue in 2025 | USD 1710 Million |
Market Revenue in 2033 | USD 2968.9 Million |
CAGR (2026 - 2033) | 7.14% |
Base Year | 2025 |
Forecast Period | 2026 - 2033 |
Historic Period | 2021 - 2025 |
Segments Covered | By TypeOn-Premises License Management Cloud-Based License Management Subscription License Management Hybrid License Management
By ApplicationLicense Compliance and Auditing License Renewal Management Software Cost Optimization
By End-UserIT and Telecommunications Banking and Financial Services Government and Public Sector Manufacturing Enterprises
|
Key Report Deliverable | Revenue Forecast, Growth Trends, Market Dynamics, Segmental Overview, Regional and Country-wise Analysis, Competition Landscape |
Region Covered | North America, Europe, Asia-Pacific, South America, Middle East, Africa |
Key Players Analyzed | Flexera, ServiceNow, IBM Corporation, Ivanti, USU Software AG, Certero, Xensam, Open iT, Matrix42, Zoho Corporation (ManageEngine), Zylo, Zluri, Torii, Licenseware |
Customization & Pricing | Available on Request (10% Customization is Free) |





