
Reports
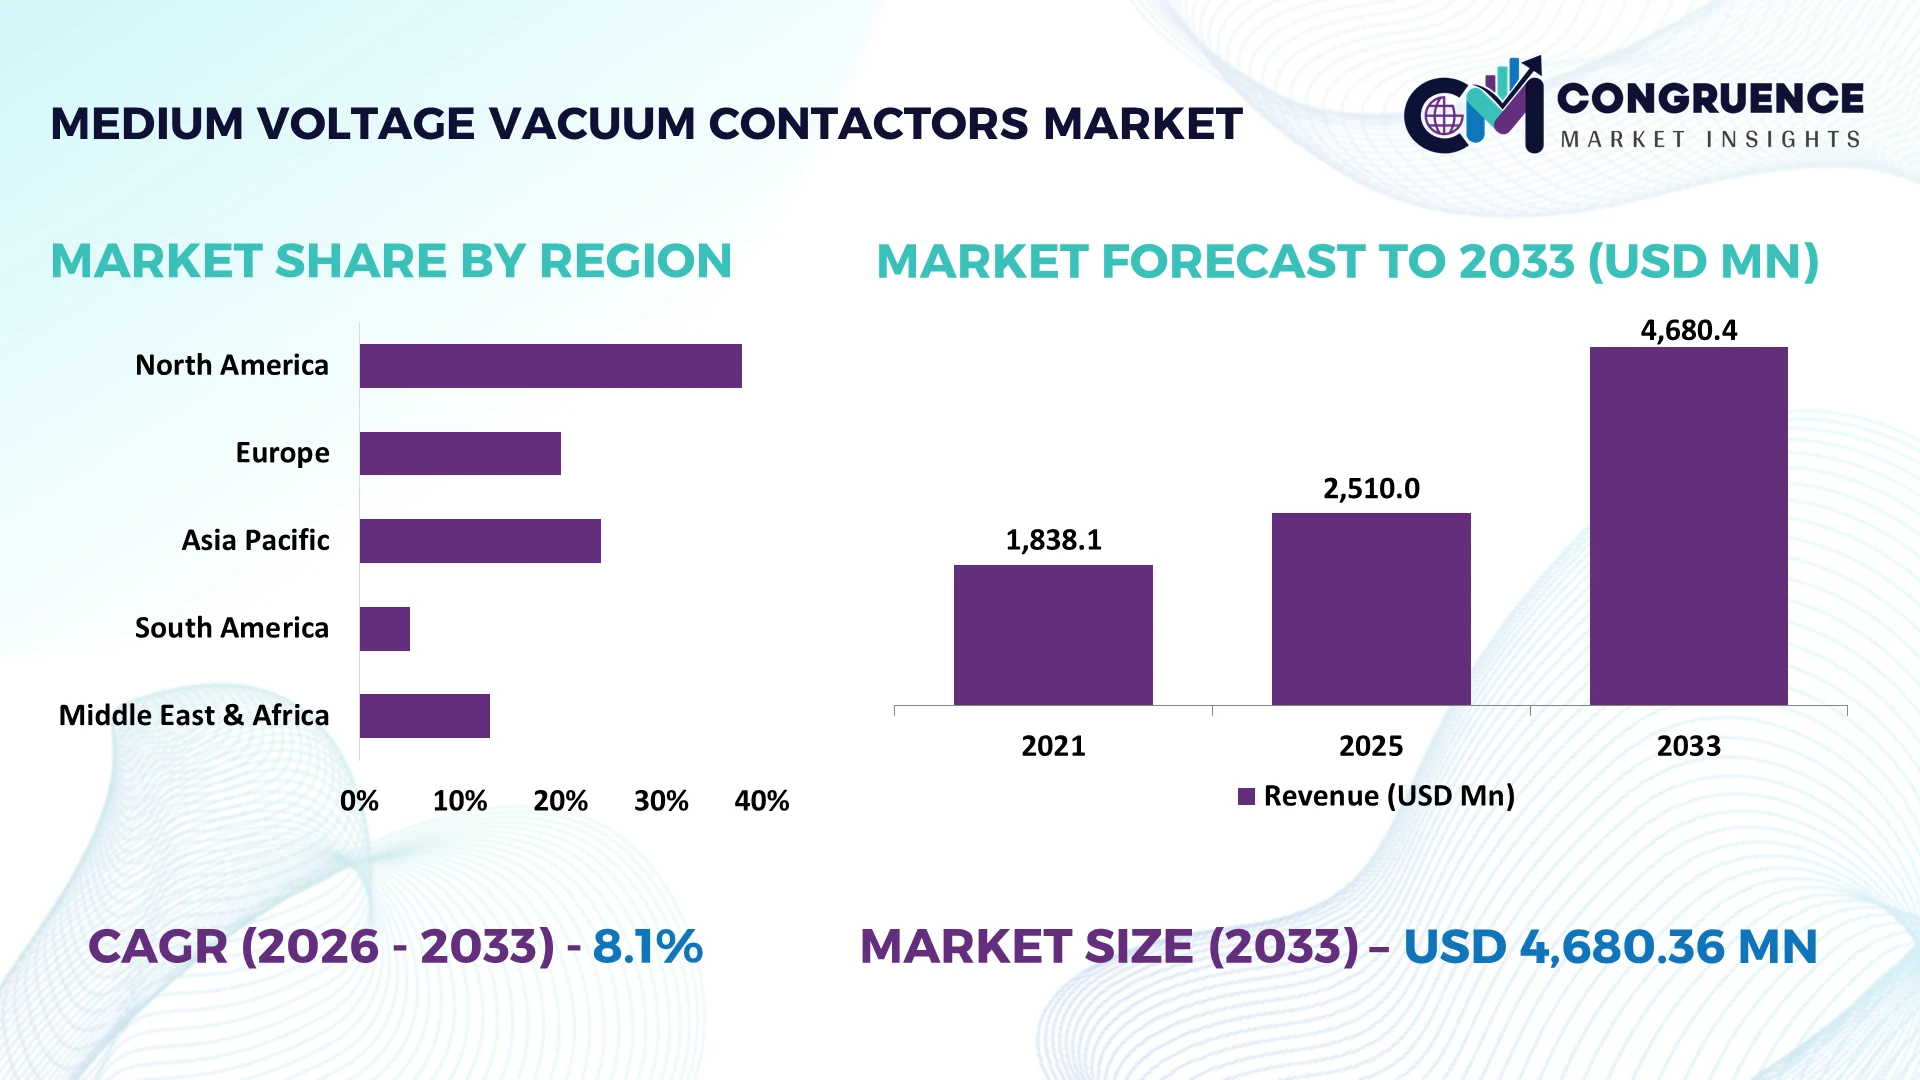
The Global Medium Voltage Vacuum Contactors Market was valued at USD 2510 Million in 2025 and is anticipated to reach a value of USD 4680.36 Million by 2033 expanding at a CAGR of 8.1% between 2026 and 2033. Growth is driven by industrial motor control modernization, mining electrification, automated medium-voltage switchgear deployment, and replacement of conventional switching equipment with maintenance-free vacuum technology.
China represents a major demand center for medium voltage vacuum contactors, supported by extensive electrical equipment manufacturing, industrial automation, and power distribution infrastructure. Chinese electricity consumption reached 10.37 trillion kWh in 2025, increasing 5%, compared with India's approximately 1.7 trillion kWh of electricity generation during FY2024–25. China's industrial sector accounted for 64% of national electricity consumption, highlighting substantial requirements for motor switching and protection equipment. Under its industrial modernization initiatives, manufacturers are integrating vacuum interrupters, intelligent control systems, and automated switchgear assemblies.
Suppliers with localized vacuum interrupter manufacturing, certified switching performance, and integrated motor control solutions are best positioned to capture industrial electrification investments.
Market Size & Growth: Valued at USD 2510 Million in 2025, projected to USD 4680.36 Million by 2033 at 8.1% CAGR, driven by industrial electrification and grid modernization .
Top Growth Drivers: Medium-voltage segment commanding 52.6% of vacuum contactor market share, motors representing largest application segment, and grid modernization replacing aging SF6 infrastructure .
Short-Term Forecast: By 2027, intelligent switching systems with digital monitoring and remote diagnostics expand adoption as industrial operators prioritize predictive maintenance over reactive replacement .
Emerging Technologies: Solid-embedded pole technology with V-0 flame retardancy, electromagnetic operating mechanisms with 1 million mechanical life, and smart monitoring solutions enabling condition-based maintenance .
Regional Leaders: Asia-Pacific at 34–38% share with China leading production, North America fastest-growing through grid resilience investment, and Europe driven by Germany and utility modernization programs .
Consumer/End-User Trends: Industrial end-users command dominant application share through motor control, transformers, and capacitor bank switching; utility substations represent fastest-growing deployment segment .
Pilot/Case Example: Schneider Electric TeSys CVX medium voltage vacuum contactor achieves 1 million mechanical operations, 1200 operations per hour, and 630A rated current with V-0 flame retardant solid-embedded poles .
Competitive Landscape: Schneider Electric, ABB, Siemens, Eaton, and Mitsubishi Electric lead; Tavrida Electric, Larsen & Toubro, and Chinese manufacturers compete on regional supply and cost efficiency .
Regulatory & ESG Impact: SF6 phase-out mandates drive vacuum contactor adoption as replacement technology; RoHS and REACH compliance govern material specifications for European and export markets .
Investment & Funding: Grid modernization programs and industrial automation investments drive demand; manufacturers investing in intelligent monitoring capabilities and compact solid-embedded pole designs .
Innovation & Future Outlook: Intelligent switching systems with remote diagnostics, compact solid-embedded architectures, and higher voltage capability expansion reshape product portfolios toward digital, connected solutions .
The global medium voltage vacuum contactors industry supports high-frequency electrical switching across mining operations, petrochemical facilities, water treatment plants, steel manufacturing, and renewable energy installations. Modern magnetic actuators, compact vacuum interrupters, and electronically controlled operating mechanisms improve switching reliability while reducing routine servicing requirements. Siemens' 3TM contactor portfolio supports rated voltages up to 15 kV and operating currents up to 450 A, demonstrating the technical capabilities of industrial-grade equipment. India's localized electrical manufacturing expansion and stricter equipment qualification requirements are strengthening supplier integration. These developments make lifecycle performance, application compatibility, and manufacturing localization increasingly important strategic considerations.
The medium voltage vacuum contactors market is becoming strategically important as industrial operators modernize motor control infrastructure, electrify production systems, and prioritize switching reliability. China's industrial electricity consumption increased 3.7% in 2025, reinforcing demand for dependable medium-voltage distribution equipment across manufacturing facilities. India's electrical equipment localization initiatives are restructuring component supply chains, with ABB manufacturing approximately 85% of its domestically sold products and solutions within the country. Manufacturers are expanding vacuum interrupter production and integrating electronic control mechanisms to strengthen equipment availability and reduce procurement dependency.
Advanced vacuum contactors offer significant operational advantages over conventional air-break contactors through sealed interruption chambers and reduced contact maintenance. Siemens' 3TM technology supports up to one million maintenance-free switching operations, eliminating routine contact servicing associated with legacy designs. Asia-Pacific emphasizes manufacturing scale and industrial electrification, while European suppliers prioritize compact switching equipment, digital diagnostics, and regulatory compliance. Industrial pumping and conveyor installations demonstrate the advantages of frequent switching without extensive mechanical servicing.
Between 2026 and 2028, integrated condition monitoring, magnetic actuation, and modular contactor-fuse assemblies will influence replacement investments. Suppliers combining localized manufacturing with application-specific engineering will secure stronger equipment partnerships and long-term maintenance advantages.
Industrial electrification is accelerating medium voltage vacuum contactor deployment across manufacturing, mining, water infrastructure, and process industries. China's electricity demand increased 5.1% in 2025, while industrial consumption expanded 3.7%, strengthening requirements for dependable switching and motor protection equipment. Globally, emerging economies accounted for approximately 80% of additional electricity demand, concentrating infrastructure investment in rapidly developing industrial markets. India's Make in India manufacturing initiatives are encouraging domestic production of vacuum interrupters and medium-voltage control assemblies. ABB is expanding manufacturing and testing capabilities in Nashik, while Siemens continues developing compact, maintenance-free vacuum switching platforms. Increasing automation intensity favors contactors capable of frequent operations, enabling manufacturers to secure equipment orders through reliability, application compatibility, and localized technical support.
Medium voltage vacuum contactor procurement remains constrained by specialized component manufacturing, equipment qualification requirements, and incompatible legacy switchgear configurations. India's electrical equipment localization illustrates the supply-chain challenge: ABB manufactures approximately 85% of its domestically sold products locally, leaving 15% outside that manufacturing base. Meanwhile, China's industrial electricity demand increased 3.7% in 2025, compared with 5.1% in 2024, reflecting uneven industrial investment conditions. Existing switchgear installations frequently require customized mounting arrangements, control voltage matching, and coordination with protective fuses before contactor replacement. These requirements increase engineering expenditure and installation downtime. Manufacturers are addressing procurement complexity through localized vacuum interrupter production, standardized retrofit assemblies, regional component sourcing, and extended equipment service agreements.
Digitally integrated vacuum contactors offer opportunities to modernize industrial motor control without replacing entire electrical distribution networks. Electric motor-driven systems account for more than 40% of global electricity consumption, while optimized motor systems offer approximately 20–30% energy-saving potential through combined efficiency improvements and adjustable-speed control. These savings originate from complete motor systems rather than contactor replacement alone. Siemens' 3TM4 platform integrates vacuum switching with 50 kA current-limiting fuse protection, supporting coordinated industrial equipment upgrades. India's projected 6.4% annual electricity demand growth through 2030 strengthens the infrastructure investment outlook. During 2026–2028, manufacturers can develop intelligent control assemblies combining switching diagnostics, predictive maintenance interfaces, and motor protection integration, targeting brownfield factories seeking improved operational visibility.
Maintaining switching consistency across demanding industrial environments presents significant engineering and deployment challenges. Siemens' 3TM contactors support up to one million maintenance-free operations, while selected configurations operate at rated voltages of 15 kV and currents reaching 450 A. However, integrating electronic controls with existing protection relays, programmable logic controllers, and supervisory monitoring networks requires detailed coordination. India's industrial electricity demand is projected to contribute approximately one-third of national consumption growth through 2030, increasing pressure to modernize industrial distribution equipment. Frequent motor starts, voltage disturbances, and harsh operating conditions complicate commissioning and long-term reliability management. Manufacturers must strengthen interoperability testing, electromagnetic compatibility engineering, cybersecurity protection for connected monitoring systems, and workforce training to deliver dependable installations across diverse industrial environments.
Plug-and-Socket Assembly Simplifies Panel Manufacturing: ABB's ConVac architecture reduces wiring time by up to 40% and accessory customization time by up to 80% through standardized electrical connections. Its 7.2 kV and 12 kV platforms share mounting arrangements, allowing panel builders to reduce engineering variations. Manufacturers are standardizing assembly workflows and component inventories to shorten delivery schedules and improve production flexibility.
High-Endurance Switching Extends Service Intervals: Siemens' 3TM contactors support up to one million maintenance-free switching operations, with rated voltages reaching 15 kV and currents of 450 A. Equipment operators are shifting procurement evaluations toward switching endurance and lifecycle servicing requirements. Suppliers are emphasizing durable actuators, sealed vacuum interrupters, and application-specific maintenance documentation to reduce operational interruptions across intensive switching installations.
Factory-Assembled Protection Packages Gain Traction: Siemens' 3TM4 integrates contactors with current-limiting fuses rated for fault protection up to 50 kA on systems reaching 12 kV. Preassembled withdrawable configurations simplify protection coordination and reduce installation complexity. Switchgear manufacturers are incorporating standardized contactor-fuse assemblies into new panels, improving commissioning consistency and reducing separately sourced protection components.
Harsh-Environment Specifications Influence Equipment Selection: ABB's ConVac operates across temperatures from −30°C to 55°C, while Siemens' 3TM supports installations at altitudes reaching 5,000 meters. These operating capabilities are influencing equipment selection for remote industrial facilities. Manufacturers are strengthening environmental qualification, vibration-resistant construction, and application engineering to improve switching reliability where conventional maintenance access is difficult.
Fixed-Mount Contactors represent a leading established product configuration in the medium voltage vacuum contactors market, supported by straightforward panel installation, reduced mechanical complexity, and compatibility with standardized motor control assemblies. ABB's ConVac platform supports fixed configurations at 7.2 kV and 12 kV, with rated currents reaching 400 A under IEC specifications. Electrically Held Contactors remain important for installations requiring automatic opening following auxiliary power interruption, supporting motor protection and emergency shutdown arrangements. Their electromagnetic holding mechanisms suit frequent switching applications across industrial installations.
Withdrawable Contactors are positioned for accelerated adoption as industrial operators emphasize faster equipment isolation, maintenance accessibility, and modular switchgear replacement. Siemens' withdrawable 3TM4 contactor-fuse assemblies combine switching functionality with fault protection reaching 50 kA, supporting compact equipment integration. Mechanically Latched Contactors serve applications requiring maintained contact closure without continuous holding-coil energization, while Reversing Contactors accommodate motor direction control through appropriately interlocked switching arrangements. Manufacturers are expanding modular product portfolios and interchangeable accessories to simplify configuration. Investment priorities increasingly favor installation compatibility, component standardization, and predictable service procedures rather than switching capability alone.
Motor Control represents the principal application for medium voltage vacuum contactors, supported by frequent switching requirements across industrial production systems and electrical motor control centers. Industrial motor-driven systems account for approximately 60% of worldwide industrial electricity demand, demonstrating the operational significance of dependable motor switching infrastructure. Siemens' 3TM equipment supports AC-1 through AC-4 switching categories, enabling applications involving motor starting, stopping, and demanding duty cycles. Transformer Switching represents another established application, where controlled interruption and contact durability help protect electrical distribution equipment.
Pump and Compressor Control is positioned for strong adoption as water infrastructure, petrochemical operations, and industrial processing facilities modernize automated pumping installations. Capacitor Bank Switching supports reactive power compensation and electrical network stability, requiring appropriate switching characteristics to manage transient conditions. Industrial Heating applications depend on reliable operation of furnaces and process equipment, while Mining Equipment Control emphasizes high-frequency switching under vibration and demanding environmental conditions. Equipment suppliers are developing specialized contactor assemblies, integrating motor protection components, and strengthening application engineering partnerships to reduce commissioning complexity and improve lifecycle reliability.
Manufacturing represents a major established end-user category for medium voltage vacuum contactors, supported by extensive motor installations across steel processing, cement production, chemical manufacturing, and heavy machinery operations. Industrial electric motor electricity demand increased approximately 60% globally between 2005 and 2023, with China recording around 190% growth over the same period. These operating conditions favor high-endurance vacuum switching equipment capable of repeated motor starts and production-line switching. Power Utilities constitute another important purchasing category, particularly for electrical distribution, transformer control, and auxiliary equipment operation. Oil and Gas operators emphasize dependable switching within compressor stations, pumping installations, and processing facilities.
Water and Wastewater is emerging as a strategically important modernization category as pumping infrastructure incorporates centralized automation and intelligent motor control systems. Mining operators require ruggedized equipment for conveyors, crushers, and ventilation systems, while Transportation applications prioritize compact switching configurations. Commercial Infrastructure increasingly requires reliable electrical control for large mechanical installations. Manufacturers are tailoring equipment portfolios through modular protection assemblies, environmental qualification, and technical service agreements. Competitive positioning increasingly depends on application-specific performance rather than standardized equipment supply.
Asia-Pacific accounted for the largest market share at approximately 38.2% in 2025 however, Asia-Pacific is expected to register the fastest growth, expanding at a CAGR of approximately 9.0% between 2026 and 2033.
Domestic Electrical Manufacturing Expansion and Industrial Switchgear Modernization
North America represents a major market for medium voltage vacuum contactors, supported by industrial equipment modernization, electrical infrastructure investment, and increasing demand for dependable motor control systems. The United States leads regional procurement through manufacturing facilities, oil and gas operations, water infrastructure, and large electrical installations. Schneider Electric announced manufacturing investments exceeding USD 700 million through 2027, including expansion of medium-voltage equipment production in Tennessee. The company also achieved NEMA domestic-content certification across more than 20 American supply-chain facilities in 2026. Industrial operators increasingly specify vacuum contactors compatible with UL 347 requirements, integrated protection assemblies, and standardized control systems. Regional manufacturers are strengthening domestic component availability, factory automation, and engineering support to reduce equipment delivery times. Replacement demand remains concentrated in established industrial facilities requiring reliable switching without extensive electrical infrastructure reconstruction.
United States Market Outlook: The United States maintains a strong competitive position through established electrical equipment manufacturers, advanced testing infrastructure, and industrial automation capabilities. Siemens announced USD 165 million in American manufacturing investment during 2026, strengthening electrical equipment production supporting industrial and infrastructure applications. Rockwell Automation and Eaton maintain extensive motor control and power distribution portfolios. Industrial facilities increasingly prioritize withdrawable contactor assemblies, coordinated fuse protection, and serviceable medium-voltage equipment to reduce production interruptions and maintenance complexity.
Advanced Switching Technology and Electrification Equipment Localization
Europe's medium voltage vacuum contactors market is shaped by industrial electrical modernization, stringent equipment qualification requirements, and investment in advanced switchgear production. Germany, France, Italy, and the United Kingdom maintain established electrical engineering industries serving automated manufacturing, transportation, and utility infrastructure. Siemens announced a EUR 300 million investment in July 2026 to expand electrical distribution equipment manufacturing in Frankfurt and establish additional supplier facilities in Offenbach. The program includes the potential creation of 700 jobs by 2030, strengthening production capacity and specialized engineering capabilities. European manufacturers emphasize compact vacuum switching devices, modular protection coordination, and compliance with IEC 62271-106 requirements. The EU's evolving restrictions on fluorinated gases in certain switchgear categories are also influencing complete equipment architectures. Suppliers are prioritizing factory digitization, component standardization, and advanced manufacturing processes to improve delivery reliability and product competitiveness.
Germany Market Outlook: Germany remains a major technology and manufacturing center for medium-voltage electrical equipment. Siemens' 3TM vacuum contactor portfolio supports rated voltages up to 15 kV and maintenance-free mechanical endurance reaching one million operations. German engineering expertise in vacuum interruption, switching diagnostics, and modular switchgear strengthens its position in demanding industrial applications. Manufacturers are integrating automated production systems and specialized testing facilities to support international equipment standards and export-oriented electrical component manufacturing.
Industrial Electrification Scale and Vacuum Interrupter Manufacturing Expansion
Asia-Pacific dominates the global medium voltage vacuum contactors market through large-scale industrial electricity consumption, expanding electrical manufacturing infrastructure, and concentrated equipment production. China, India, Japan, and South Korea maintain substantial industrial motor installations across automotive manufacturing, metals processing, chemicals, and heavy engineering. China's installed power generation capacity exceeded 3.8 billion kW in 2025, strengthening the requirement for industrial auxiliary equipment and electrical distribution modernization. India is developing domestic vacuum interrupter manufacturing capabilities alongside investments in electrical protection technologies. ABB announced approximately USD 75 million in manufacturing and research investments across Indian facilities during 2026, including expansion of its Nashik vacuum interrupter factory. Japanese manufacturers emphasize compact equipment design and precise electromechanical operation, while Chinese suppliers benefit from extensive component manufacturing networks. Regional competitiveness increasingly depends on localized production, equipment certification, and integration with automated industrial control infrastructure.
China Market Outlook: China represents the region's largest industrial electrical equipment demand center, supported by extensive motor-driven manufacturing and established vacuum switching component production. National electricity consumption reached approximately 10.37 trillion kWh in 2025, with secondary industries accounting for the majority of consumption. Domestic manufacturers including CHINT and other electrical equipment suppliers serve industrial distribution and automation applications. Investments in automated assembly, vacuum interrupter production, and component testing support competitive manufacturing costs and dependable equipment availability.
Mining Electrification and High-Capacity Motor Control Upgrades
South America's medium voltage vacuum contactors market is closely associated with mining equipment modernization, industrial processing, and electrical distribution infrastructure. Chile, Brazil, Peru, and Argentina account for important industrial demand centers, particularly where large motors operate crushers, conveyors, compressors, and mineral processing equipment. Chile's copper mining industry consumed approximately 199,452 terajoules of energy in 2024, including 102,307 terajoules of electricity, highlighting the scale of electrically operated mining infrastructure. Increasing mineral processing intensity is encouraging equipment operators to improve switching endurance, protection coordination, and maintenance accessibility. Brazil's industrial manufacturing sector also supports replacement demand for medium-voltage motor control assemblies. Manufacturers are strengthening regional distribution partnerships and technical service capabilities, although imported component dependency and specialized maintenance requirements continue to influence procurement. Local availability of replacement assemblies remains strategically important for minimizing industrial downtime.
Chile Market Outlook: Chile represents a strategically important market for medium-voltage switching equipment because of its extensive copper mining and mineral concentration infrastructure. The Chilean Copper Commission projects mining electricity consumption increasing from 27.6 TWh in 2025 to 33.2 TWh by 2034, an approximately 20.2% increase. Concentrator operations and seawater pumping installations require dependable motor starting and switching equipment. Suppliers specializing in ruggedized vacuum contactors, integrated protection, and remote maintenance support are positioned to address demanding mining operations.
Power Infrastructure Modernization and Industrial Automation Deployment
The Middle East & Africa medium voltage vacuum contactors market is influenced by electricity distribution expansion, industrial diversification, and investments in energy-intensive manufacturing infrastructure. Saudi Arabia, the United Arab Emirates, and South Africa represent important equipment procurement markets across power utilities, petrochemicals, mining, and industrial facilities. Saudi Electricity Company expanded its transmission network to approximately 104,628 circuit kilometers by September 2025, representing 5% annual growth. During the first nine months, the utility energized 45 new transmission substations, increasing demand for associated electrical distribution and auxiliary control equipment. In South Africa, electricity infrastructure modernization is encouraging replacement of aging electrical control assemblies and improvements in industrial equipment reliability. International manufacturers are developing regional service networks, engineering partnerships, and project-specific equipment configurations. Local testing capabilities and dependable technical support remain essential for securing large industrial and infrastructure contracts.
Saudi Arabia Market Outlook: Saudi Arabia leads several major electrical infrastructure development programs under Vision 2030, supported by industrial expansion and utility network modernization. Saudi Electricity Company's distribution substation automation rate reached approximately 39.29% during the first nine months of 2025, demonstrating increased integration of electrical monitoring and control technologies. Petrochemical facilities in Jubail and Yanbu require dependable medium-voltage motor switching for compressors, pumps, and processing systems. Equipment suppliers are emphasizing industrial-grade protection, localized servicing, and integration with automated plant control networks.
Schneider Electric, ABB, Siemens, Eaton, and Mitsubishi Electric anchor the medium voltage vacuum contactor market, with the top five players commanding approximately 55–60% of global revenue through established utility relationships and comprehensive motor control portfolios. Competition bifurcates between global electrical equipment leaders competing on intelligent switching integration and IEC/IEEE certification depth, and regional specialists including Tavrida Electric, Larsen & Toubro, and Chinese manufacturers competing on price and localized supply. The basis of competition is shifting from switching durability toward digital capability: intelligent contactors with remote diagnostics and condition monitoring capture 8–12% price premiums as industrial operators prioritize predictive maintenance. Players compete through utility framework agreements, industrial automation ecosystem integration, and vertical integration into vacuum interrupter production. The competitive shift is toward solid-embedded pole architectures enabling compact designs and higher switching frequency, while SF6 phase-out mandates accelerate vacuum technology adoption across European utilities. Entry barriers center on utility qualification timelines and vacuum interrupter manufacturing expertise.
Schneider Electric
ABB
Siemens
Eaton
Mitsubishi Electric
Tavrida Electric
Larsen & Toubro
Fuji Electric
Toshiba Infrastructure Systems
Rockwell Automation
Yueqing Liyond Electric
Kunshan GuoLi Electronic Technology
Shaanxi Joyelectric International
Zhiyu Electric
Modern medium voltage vacuum contactors integrate sealed interrupters, electronic coil control, and modular mounting systems to improve switching reliability. ABB's ConVac design reduces wiring time by up to 40%, customization time by 80%, and equipment footprint by 20% compared with conventional arrangements. Siemens' 3TM platform supports one million maintenance-free operations, while 7.2–15 kV configurations address industrial motor switching requirements. These technologies benefit switchgear manufacturers through simplified assembly, reduced servicing, and standardized component integration.
Emerging technologies include magnetic actuation, intelligent switching diagnostics, and digitally coordinated contactor-fuse protection. Siemens' 3TM4 integrates 50 kA current-limiting fuse protection with vacuum switching, supporting coordinated protection in compact assemblies. Compared with legacy separately configured protection arrangements, integrated systems reduce engineering interfaces and simplify equipment qualification. Toshiba's electronically controlled operating coils and advanced vacuum interrupter materials further support switching consistency. Industrial automation suppliers gain competitive advantages by combining contactor functionality with motor protection and supervisory monitoring infrastructure.
During 2026–2028, integrated condition monitoring, predictive maintenance interfaces, and modular retrofit engineering will shape procurement decisions. ABB's manufacturing localization investments support component availability, while OEMs increasingly prioritize application-specific configuration. Suppliers delivering documented switching endurance, interoperability, and installation efficiency will strengthen industrial contracts and reduce customer maintenance exposure.
March 2026: ABB announced a $75 million Indian manufacturing expansion, including vacuum interrupter production at Nashik. The investment strengthens localized component availability, supports medium-voltage switching equipment supply, and increases engineering capacity for industrial electrification projects and domestic manufacturing operations. Source: abb.com.
April 2026: Eaton announced a new 370,000-square-foot Nebraska facility for medium-voltage switchgear manufacturing, targeting production in 2027. The expansion addresses electrical infrastructure supply constraints and supports faster equipment availability for data centers, utilities, and industrial power distribution customers. Source: eaton.com.
May 2025: Siemens appointed Teck Global as its Australian medium-voltage portfolio reseller after collaborating on two major Western Australian battery projects. The partnership expands regional engineering and distribution support for switching equipment used in industrial and electrical infrastructure. Source: siemens.com.
May 2026: ABB outlined European medium-voltage manufacturing expansion, with Reuters reporting planned production capacity increases of 50%–300% depending on product line. The program strengthens vacuum interrupter and switchgear supply, reducing procurement bottlenecks for major electrical infrastructure modernization projects. Source: reuters.com.
The Medium Voltage Vacuum Contactors Market Report examines industrial switching technologies, equipment procurement, competitive positioning, and deployment developments between 2026 and 2033. Type segmentation covers Fixed-Mount, Withdrawable, Electrically Held, Mechanically Latched, and Reversing Contactors. Application analysis includes Motor Control, Transformer Switching, Capacitor Bank Switching, Pump and Compressor Control, Industrial Heating, and Mining Equipment Control. End-user assessment addresses Power Utilities, Oil and Gas, Mining, Manufacturing, Water and Wastewater, Transportation, and Commercial Infrastructure.
Geographical coverage spans North America, Europe, Asia-Pacific, South America, and the Middle East & Africa, emphasizing country-level manufacturing and deployment patterns. Technology analysis examines 7.2–15 kV switching platforms, digital diagnostics, magnetic actuation, and modular protection integration. The report supports manufacturing localization, supplier selection, investment planning, product differentiation, and strategic expansion decisions across industrial electrification markets.
| Report Attribute/Metric | Report Details |
|---|---|
Market Revenue in 2025 | USD 2510 Million |
Market Revenue in 2033 | USD 4680.36 Million |
CAGR (2026 - 2033) | 8.1% |
Base Year | 2025 |
Forecast Period | 2026 - 2033 |
Historic Period | 2021 - 2025 |
Segments Covered | By Type
By Application
By End-User
|
Key Report Deliverable | Revenue Forecast, Growth Trends, Market Dynamics, Segmental Overview, Regional and Country-wise Analysis, Competition Landscape |
Region Covered | North America, Europe, Asia-Pacific, South America, Middle East, Africa |
Key Players Analyzed | Schneider Electric, ABB, Siemens, Eaton, Mitsubishi Electric, Tavrida Electric, Larsen & Toubro, Fuji Electric, Toshiba Infrastructure Systems, Rockwell Automation, Yueqing Liyond Electric, Kunshan GuoLi Electronic Technology, Shaanxi Joyelectric International, Zhiyu Electric |
Customization & Pricing | Available on Request (10% Customization is Free) |




