
Reports
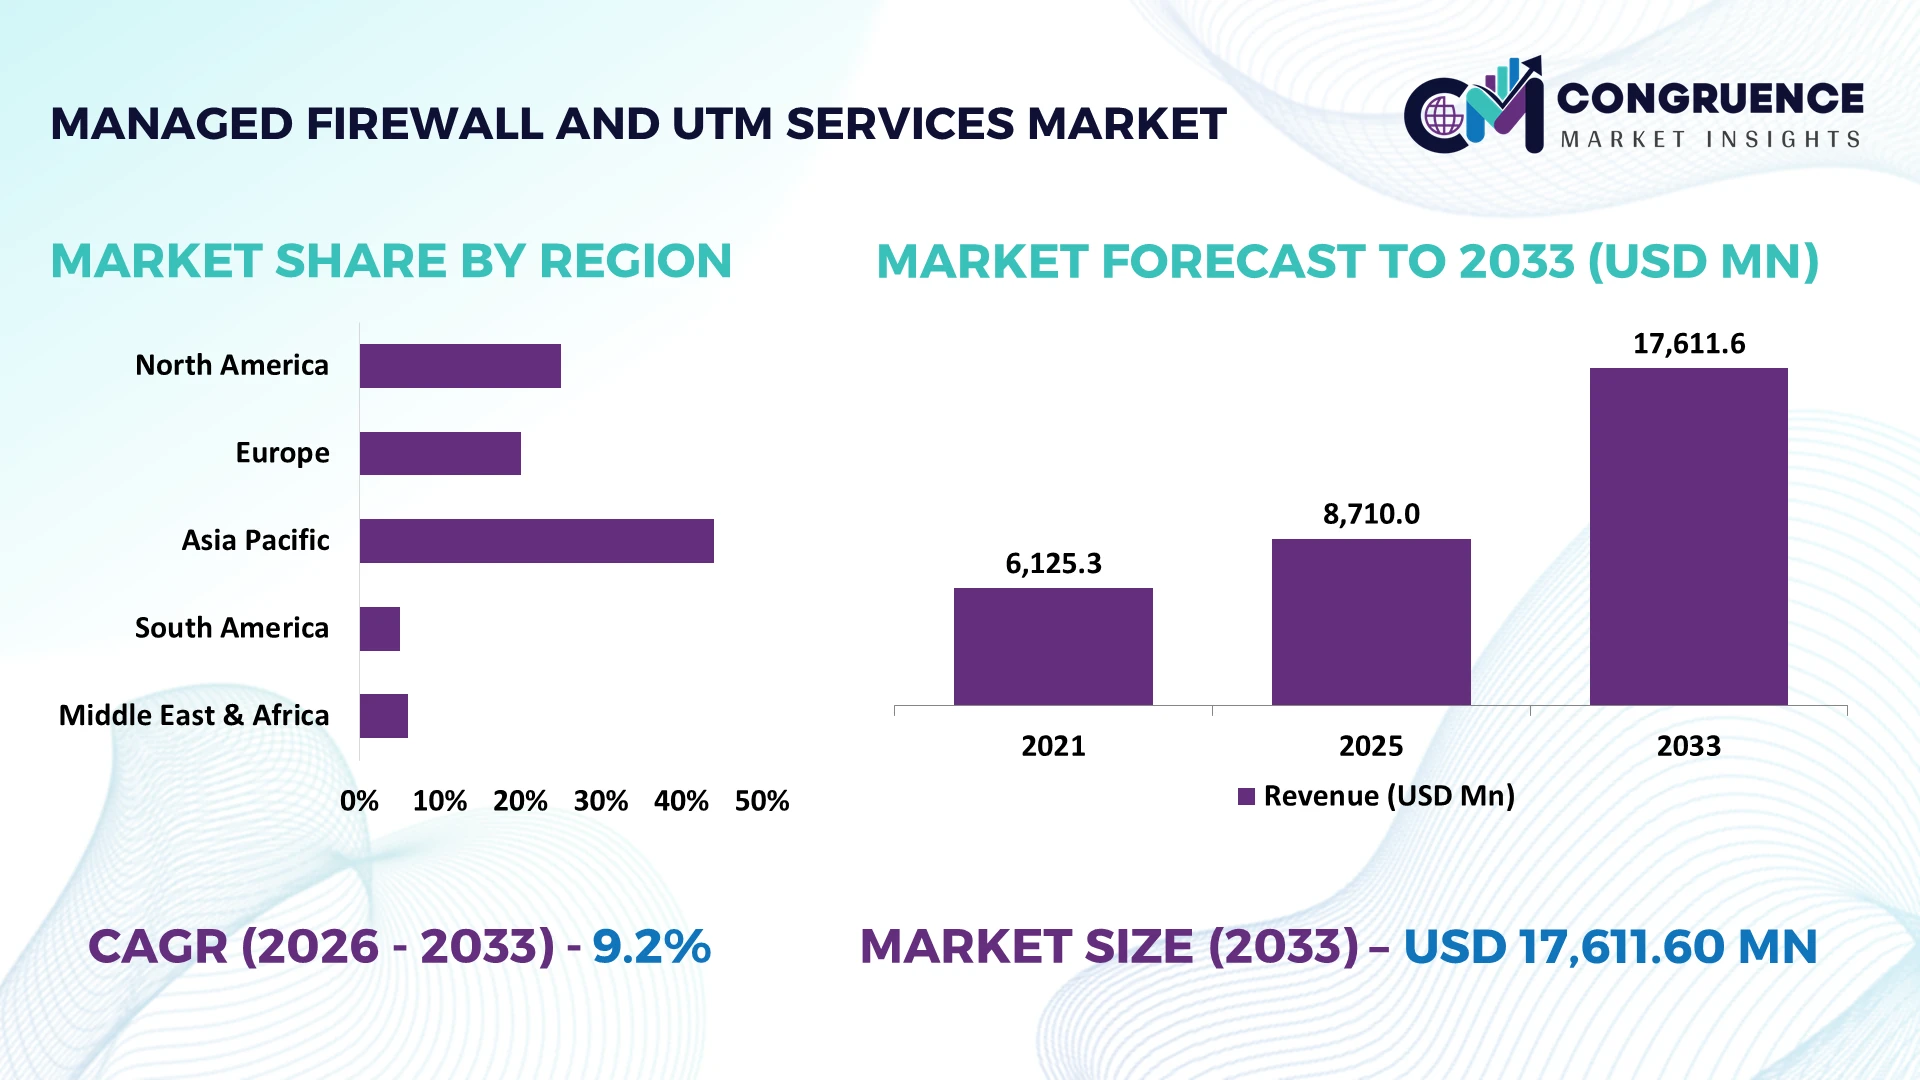
The Global Managed Firewall and UTM Services Market was valued at USD 8710 Million in 2025 and is anticipated to reach a value of USD 17611.6 Million by 2033 expanding at a CAGR of 9.2% between 2026 and 2033. Growth is driven by increasing exploitation of internet-facing vulnerabilities, hybrid cloud security requirements, and enterprise outsourcing of next-generation firewall management, intrusion prevention, and unified threat management operations.
The United States dominates the managed firewall and UTM services landscape through extensive enterprise cybersecurity infrastructure, major security technology vendors, and established managed service providers. Verizon's 2025 investigations identified vulnerability exploitation in 20% of breaches, a 34% annual increase, reinforcing demand for advanced perimeter protection. Financial institutions, healthcare providers, government agencies, and technology companies are major customers. Compared with India, where outsourcing emphasizes cost-efficient security operations, American enterprises prioritize zero-trust integration, cloud firewall orchestration, and compliance with federal cybersecurity modernization requirements.
Strategically, providers combining centralized firewall policy management, automated threat prevention, and scalable multicloud security services are positioned to strengthen enterprise contracts.
Market Size & Growth: USD 8,710 million in 2025, reaching USD 17,611.6 million by 2033 at 9.2% CAGR, driven by managed next-generation firewall adoption.
Top Growth Drivers: Vulnerability exploitation increased 34%, third-party breach involvement reached 30%, and ransomware appeared in 44% of investigated breaches.
Short-Term Forecast: By 2028, automated firewall operations will prioritize reducing breach containment lifecycles; extensive security AI adoption already demonstrates approximately 34% lower breach costs.
Emerging Technologies: Three technologies reshape managed security: AI-driven firewall policy optimization, secure access service edge, and cloud-native intrusion prevention.
Regional Leaders: North America leads advanced managed firewall deployment, Europe emphasizes regulated network protection, and Asia-Pacific expands outsourced security operations across 3 major enterprise environments.
Consumer/End-User Trends: Approximately 30% of breaches involved third parties in 2025, strengthening enterprise demand for vendor-access segmentation and managed firewall monitoring.
Pilot/Case Example: IBM's 2025 security research identified approximately 80 fewer breach lifecycle days among organizations extensively deploying security AI and automation.
Competitive Landscape: Fortinet, Palo Alto Networks, Cisco, Check Point, and Sophos compete through 3 capabilities: integrated threat prevention, centralized management, and managed security delivery.
Regulatory & ESG Impact: Europe's NIS2 framework extends cybersecurity obligations across 18 critical sectors, strengthening demand for auditable network security controls.
Investment & Funding: Enterprise security investment prioritizes 3 areas: cloud firewall infrastructure, automated security operations, and managed service partnerships.
Innovation & Future Outlook: By 2033, advanced firewall services will integrate 3 capabilities: identity-aware access enforcement, automated threat intelligence, and distributed cloud security management.
The Managed Firewall and UTM Services Market is evolving as enterprises replace fragmented perimeter appliances with centrally managed network security architectures. Financial institutions, telecommunications operators, healthcare networks, and manufacturing enterprises require continuous intrusion prevention, secure remote access, and consistent firewall policy enforcement. Vulnerability exploitation accounted for approximately 20% of investigated breaches in 2025, highlighting the importance of protecting internet-facing infrastructure. Cloud-delivered firewall services, AI-assisted rule optimization, and integrated security monitoring are transforming managed service offerings. Europe's NIS2 requirements further reinforce demand for documented network protection, establishing the foundation for evaluating competitive strategies and long-term investment priorities.
Managed firewall and unified threat management services are becoming strategic infrastructure investments as enterprises replace fragmented perimeter security with centrally governed, continuously monitored protection. Hybrid cloud adoption, distributed workforces, and interconnected supplier networks require consistent policy enforcement across physical and virtual environments. Third-party involvement in security breaches reached 30% in 2025, reinforcing demand for managed network segmentation and external access controls. Europe's NIS2 framework is further restructuring procurement around documented security governance, incident reporting, and operational accountability.
Cloud-managed next-generation firewalls offer advantages over legacy manually administered appliances through centralized policy deployment, automated configuration validation, and integrated threat intelligence. Organizations extensively adopting security AI and automation have recorded approximately 34% lower breach costs than those without these capabilities. The United States leads advanced firewall orchestration and security platform integration, while India emphasizes scalable managed security delivery through Bengaluru, Hyderabad, and Pune. Enterprises increasingly deploy unified firewall policies across headquarters, branch networks, and cloud workloads, reducing configuration inconsistencies and administrative duplication.
Between 2026 and 2028, investment priorities will increasingly favor identity-aware inspection, automated policy lifecycle management, and consolidated security operations. Providers are expanding cloud security partnerships, developing managed SASE capabilities, and integrating firewall telemetry with threat detection platforms. Competitive advantage will depend on reliable enforcement, transparent service performance, and efficient multivendor security management.
Increasing exploitation of internet-facing infrastructure is accelerating enterprise adoption of managed firewall and UTM services. Vulnerability exploitation accounted for 20% of investigated breaches in 2025, representing a 34% annual increase, while ransomware appeared in 44% of breaches. Attackers increasingly target VPN gateways, exposed network appliances, and unpatched remote access infrastructure, increasing the operational importance of continuous intrusion prevention. In the United States, federal zero-trust modernization initiatives are strengthening requirements for network segmentation and identity-aware access enforcement. Managed security providers are expanding next-generation firewall operations, automated policy management, and threat intelligence integration through technology partnerships. Centralized security administration enables enterprises to address changing network exposures without proportionally expanding internal security teams.
Legacy network architecture and constrained security budgets restrict managed firewall deployment across heterogeneous enterprise environments. In 2025, 36% of surveyed cybersecurity professionals reported organizational budget cuts, while 33% identified insufficient resources to staff security teams adequately. Another 29% reported difficulty affording qualified cybersecurity personnel. Indian enterprises operating multivendor firewall estates face additional integration costs associated with policy migration, licensing, encrypted traffic inspection, and centralized logging. Differences between appliance firmware, cloud security interfaces, and network routing configurations increase implementation complexity and prolong customer onboarding. Providers are responding through standardized migration services, flexible subscription contracts, and vendor-neutral management platforms. Procurement increasingly favors predictable operating expenditure and interoperability rather than extensive appliance replacement, particularly among distributed midmarket organizations.
Cloud-native firewall management creates opportunities for providers serving enterprises with distributed applications and rapidly changing network boundaries. Approximately 63% of surveyed organizations lacked comprehensive AI governance policies in 2025, while 97% of organizations reporting AI-related security incidents lacked appropriate access controls. These findings reinforce demand for identity-aware security policies, cloud workload segmentation, and automated configuration assessment. Singapore's cybersecurity regulatory framework and expanding cloud infrastructure create opportunities for managed security providers offering localized policy enforcement and continuous compliance monitoring. Vendors are developing AI-assisted rule optimization, firewall-as-a-service subscriptions, and integrated secure access architectures. Partnerships with cloud infrastructure operators enable scalable deployment without dedicated appliances at every location. The strongest opportunity lies in reducing configuration drift across multicloud environments.
Maintaining consistent firewall enforcement across expanding enterprise networks presents a significant operational challenge. In 2025, 95% of surveyed cybersecurity professionals identified organizational skills requirements, while 59% reported critical or significant skills deficiencies. Additionally, 26% experienced cybersecurity process oversights associated with capability shortages. In Germany, industrial enterprises integrating operational technology with corporate networks face complex segmentation requirements involving legacy protocols, production availability, and encrypted application traffic. Frequent firewall rule changes increase the risk of unintended service disruption and inconsistent access controls. Managed providers must invest in automated policy testing, configuration rollback capabilities, and specialized network security engineering. Sustainable service delivery depends on maintaining enforcement accuracy while supporting continuous infrastructure changes without compromising industrial operations.
Encrypted Traffic Inspection Gains Priority: Enterprises are strengthening TLS inspection as encrypted application traffic reduces visibility into malicious payloads. TLS 1.3 and HTTP/3 introduce additional inspection complexity, while vulnerability exploitation accounted for 20% of investigated breaches in 2025. Managed security providers are deploying hardware acceleration, selective decryption, and application-aware inspection policies. These changes improve threat visibility while controlling processing overhead and protecting sensitive financial and healthcare communications.
Firewall Policy Auditing Becomes Continuous: Security teams are replacing periodic firewall rule reviews with automated policy verification and configuration monitoring. Third-party involvement reached 30% of investigated breaches in 2025, doubling from the previous reporting period. Enterprises are integrating access rule inventories, change approval workflows, and continuous configuration assessment. Managed service providers are introducing automated rule recertification and policy simulation, reducing unnecessary permissions while strengthening accountability across complex supplier networks.
Industrial Network Segmentation Gains Momentum: Manufacturing enterprises are strengthening firewall protection between operational technology and corporate networks. Espionage-related manufacturing breaches increased from 3% to 20% in recent investigations, highlighting changing industrial threat exposure. German automotive and machinery manufacturers are implementing industrial firewalls, protocol-aware inspection, and segmented remote maintenance connections. Security vendors are expanding operational technology partnerships and specialized deployment services, improving production network isolation without interrupting critical manufacturing processes.
Unified Security Platforms Reshape Procurement: Enterprises are consolidating firewall management, intrusion prevention, and centralized security analytics into integrated operating environments. Organizations extensively using security AI and automation recorded approximately 34% lower breach costs and 80 fewer breach lifecycle days. Providers are combining unified threat management consoles with automated incident workflows and integrated threat intelligence. This consolidation reduces administrative fragmentation and strengthens service differentiation through measurable security performance.
Managed Firewall Services represent the leading type within the global Managed Firewall and UTM Services Market, supported by established enterprise demand for continuous firewall administration, policy maintenance, and network perimeter protection. These services accommodate heterogeneous network infrastructure and existing security appliances without requiring immediate platform replacement. Unified Threat Management (UTM) remains important among small and medium-sized enterprises seeking integrated firewall, intrusion prevention, web filtering, and antivirus capabilities. Verizon's 2025 investigations identified vulnerability exploitation in 20% of breaches, emphasizing the importance of maintaining effective network security controls. Managed providers are strengthening centralized administration, automated configuration assessment, and service-level monitoring to improve operational consistency.
Cloud-Based Firewall Services represent the fastest-growing type as enterprises distribute applications across public cloud platforms and remote operating environments. Next-Generation Firewall Services maintain strong adoption through application identification, deep packet inspection, and integrated threat prevention. Extensive security AI and automation adoption has demonstrated approximately 34% lower breach costs, strengthening the commercial case for intelligent security management. Vendors are expanding cloud partnerships, virtual firewall offerings, and unified management platforms to support evolving deployment requirements.
Network Security represents the leading application within the Managed Firewall and UTM Services Market because enterprises require continuous protection of internal networks, internet gateways, and interconnected business systems. Financial institutions, healthcare providers, and telecommunications operators depend on firewall policy enforcement to regulate traffic flows and restrict unauthorized access. Vulnerability exploitation accounted for approximately 20% of investigated breaches in 2025, reinforcing demand for network segmentation and controlled connectivity. Threat Prevention remains a critical application through intrusion prevention systems, malicious traffic filtering, and integrated threat intelligence. Managed providers are strengthening inspection capabilities and automated configuration monitoring to improve detection consistency across enterprise environments.
Secure Remote Access is emerging as the fastest-growing application as organizations replace traditional VPN-centric connectivity with identity-aware access architectures. Third-party involvement in breaches reached 30%, highlighting risks associated with external network connections. Regulatory Compliance also supports adoption through requirements for documented security controls and audit-ready firewall configurations. Vendors are integrating secure access service edge capabilities, centralized policy orchestration, and continuous compliance monitoring. Enterprise investment increasingly prioritizes controlled application access rather than unrestricted network connectivity.
Banking and Financial Services represent a leading end-user category within the Managed Firewall and UTM Services Market, supported by extensive digital transaction infrastructure, strict security requirements, and continuous network availability needs. Financial institutions deploy managed firewall services across payment gateways, branch networks, data centers, and cloud-hosted banking applications. Verizon's 2025 investigations documented 3,336 security incidents involving financial organizations, reinforcing the importance of network access controls and intrusion prevention. Government agencies maintain significant demand through public infrastructure protection and security modernization initiatives, while IT and Telecommunications operators require scalable firewall administration across extensive interconnected networks. Providers are developing sector-specific security policies, managed segmentation services, and dedicated compliance support.
Manufacturing is emerging as an important expansion segment as industrial enterprises connect production systems with corporate IT infrastructure. Espionage-related manufacturing breaches increased from 3% to 20%, strengthening demand for industrial network segmentation. Healthcare organizations also require reliable protection for clinical systems and connected medical infrastructure. Managed security vendors are expanding operational technology expertise, healthcare-specific firewall configurations, and flexible subscription contracts. Competitive differentiation increasingly depends on industry-specific protection and deployment reliability.
North America accounted for the largest market share at an estimated 38% in 2025 however, Asia-Pacific is expected to register the fastest growth, expanding at a CAGR of an estimated 11.4% between 2026 and 2033.
Cloud Security Consolidation Strengthens Managed Firewall Adoption
North America maintains a leading position in managed firewall and UTM services, supported by extensive enterprise networking infrastructure, mature cybersecurity procurement, and established managed security service providers. The United States represents the principal deployment center, while Canada contributes through financial services modernization and critical infrastructure protection. Enterprises increasingly consolidate next-generation firewalls, intrusion prevention, and secure remote access within centrally administered security platforms. The United States federal zero-trust modernization agenda reinforces requirements for identity-aware network segmentation and continuous access verification. Financial institutions, healthcare organizations, and telecommunications operators are expanding managed security contracts to support hybrid infrastructure protection. Vendors including Fortinet, Palo Alto Networks, and Cisco are strengthening cloud security integrations and service provider partnerships. Regional competition increasingly centers on automated policy administration, consistent threat inspection, and integration with enterprise security operations platforms.
United States Market Outlook: The United States benefits from concentrated cybersecurity technology development, extensive cloud infrastructure, and established managed security delivery networks. Vulnerability exploitation accounted for approximately 20% of investigated breaches in 2025, reinforcing demand for continuous perimeter protection. American enterprises increasingly deploy centrally managed next-generation firewalls, automated rule validation, and secure access architectures. Federal cybersecurity modernization initiatives further strengthen procurement requirements for continuous monitoring and network segmentation.
Regulatory Harmonization Reshapes Enterprise Network Protection
Europe's managed firewall and UTM services market is increasingly influenced by cybersecurity regulation, critical infrastructure modernization, and cross-border network security requirements. Germany, France, the United Kingdom, and the Netherlands represent important enterprise deployment centers, supported by financial services, industrial manufacturing, and telecommunications infrastructure. The NIS2 Directive expands cybersecurity obligations across 18 critical sectors, encouraging stronger network access controls, incident reporting, and supplier security oversight. Financial institutions are also strengthening technology risk management under the Digital Operational Resilience Act. Managed security providers are expanding regional security operations centers, developing sovereign cloud security capabilities, and integrating automated firewall policy compliance monitoring. European enterprises increasingly prioritize auditable configuration management and data residency controls. Providers combining regulatory expertise with multivendor firewall orchestration gain competitive advantages in regulated procurement environments.
Germany Market Outlook: Germany's automotive, machinery, chemical, and industrial automation industries require secure connectivity between production networks and enterprise systems. The country's cybersecurity framework emphasizes critical infrastructure protection and structured security governance. Industrial enterprises increasingly deploy protocol-aware firewalls, network segmentation, and controlled remote maintenance access. German managed security providers are strengthening operational technology partnerships and specialized firewall administration services to support industrial network resilience.
Digital Infrastructure Expansion Accelerates Managed Security Deployment
Asia-Pacific is emerging as a major expansion environment for managed firewall and UTM services, supported by cloud infrastructure investment, enterprise digitalization, and increasing cybersecurity outsourcing. China, India, Japan, Australia, and Singapore represent important deployment markets with distinct technology and procurement requirements. India benefits from extensive IT services capabilities and established managed security delivery centers, while Japan emphasizes industrial network protection and reliable enterprise connectivity. Singapore's cybersecurity regulatory framework strengthens security requirements for designated critical information infrastructure. Australian organizations are expanding managed network protection following major cybersecurity incidents and critical infrastructure security reforms. Providers are developing localized security operations capabilities, cloud-delivered firewall platforms, and flexible subscription models. Competitive differentiation increasingly depends on affordable continuous monitoring, regional threat intelligence, and consistent policy enforcement across distributed enterprise networks.
India Market Outlook: India's expanding digital payments ecosystem, enterprise cloud adoption, and telecommunications infrastructure create substantial demand for managed firewall services. CERT-In requires specified cybersecurity incidents to be reported within six hours, strengthening the operational importance of continuous monitoring and rapid escalation. Cybersecurity service providers in Bengaluru, Hyderabad, Pune, and Noida are expanding firewall administration, intrusion prevention, and security orchestration capabilities for domestic and international enterprises.
Financial Digitalization Drives Managed Network Protection
South America's managed firewall and UTM services market is developing around financial technology adoption, telecommunications modernization, and increasing enterprise cloud connectivity. Brazil represents the principal cybersecurity deployment center, while Colombia, Chile, and Argentina contribute through banking modernization and government digital infrastructure programs. The expansion of instant payment systems and online financial services is increasing requirements for continuous network traffic inspection and secure application access. Enterprises increasingly outsource firewall administration to address specialized security staffing constraints and complex multivendor infrastructure. Managed service providers are strengthening regional telecommunications partnerships, expanding localized security operations, and introducing subscription-based UTM offerings for midmarket customers. Deployment limitations include uneven network infrastructure maturity and differences in cybersecurity procurement capacity. Providers offering standardized security management with localized technical support are positioned to improve enterprise adoption.
Brazil Market Outlook: Brazil's extensive banking infrastructure and expanding digital payment ecosystem support managed firewall deployment across financial institutions and technology providers. The Pix instant payment system processed more than 6 billion transactions during a single month in 2025, highlighting the operational scale of digital financial services. Brazilian enterprises are strengthening network segmentation, application-layer filtering, and secure connectivity while managed security providers expand local technical support and cloud security partnerships.
National Cybersecurity Programs Accelerate Infrastructure Protection
The Middle East & Africa managed firewall and UTM services market is shaped by government digital transformation, energy infrastructure protection, and expansion of enterprise cloud environments. Saudi Arabia and the United Arab Emirates lead major cybersecurity modernization initiatives, while South Africa supports demand through established financial services and telecommunications infrastructure. Saudi Arabia's Vision 2030 programs are expanding interconnected public services and industrial systems, strengthening requirements for centrally managed network protection. The UAE's cloud infrastructure development is encouraging deployment of virtual firewalls, secure access services, and integrated threat prevention. Energy operators increasingly require network segmentation between operational technology and corporate environments. Cybersecurity vendors are expanding localized managed security operations, developing regional cloud partnerships, and introducing industry-specific firewall services. Data sovereignty and specialized technical staffing remain important procurement considerations.
Saudi Arabia Market Outlook: Saudi Arabia's government digitalization, financial services modernization, and industrial infrastructure investment support managed firewall adoption. The National Cybersecurity Authority's Essential Cybersecurity Controls establish 114 controls across five domains, reinforcing structured network protection and security governance. Domestic enterprises are strengthening centralized firewall management, secure remote access, and continuous intrusion prevention. Regional providers are expanding partnerships with international cybersecurity vendors to improve service delivery across critical infrastructure environments.
Fortinet, Palo Alto Networks, Cisco, Check Point, and Sophos compete through firewall platforms, integrated threat prevention, and managed service partnerships, while Orange Cyberdefense and regional MSSPs differentiate through outsourced operations. The top five providers' combined managed services market share cannot be established reliably from publicly separated service revenues. Competition centers on detection effectiveness, subscription pricing, policy automation, and multicloud interoperability. Vulnerability exploitation increased 34% in 2025, while third-party involvement reached 30% of investigated breaches, intensifying demand for managed segmentation and continuous inspection. Vendors are expanding security operations partnerships, integrating AI-assisted policy management, and consolidating firewall telemetry with incident response workflows. Cloud-native security platforms challenge appliance-centered delivery models, while specialized providers compete through industry-specific configurations and localized support. Integration complexity, skilled personnel shortages, and customer switching costs constrain market entry. Winning requires measurable protection, predictable operating costs, and reliable security enforcement across heterogeneous enterprise environments at scale.
Fortinet, Inc.
Palo Alto Networks, Inc.
Cisco Systems, Inc.
Check Point Software Technologies Ltd.
Sophos Limited
Orange Cyberdefense
BT Group plc
AT&T Inc.
Verizon Communications Inc.
NTT DATA Group Corporation
Trustwave Holdings, Inc.
Secureworks
Managed firewall platforms combine next-generation packet inspection, intrusion prevention, application identification, and centralized policy orchestration. TLS inspection and virtual firewalls extend protection across encrypted traffic and hybrid infrastructure. Cloud-managed configurations replace device-by-device administration with reusable policy templates and automated validation. Organizations extensively using security AI and automation reported approximately 34% lower breach costs than organizations without these capabilities. Providers integrating firewall telemetry with security analytics platforms gain faster incident correlation and consistent enforcement.
Emerging architectures integrate firewall-as-a-service, zero-trust network access, and secure access service edge into unified enforcement platforms. Identity-aware inspection restricts application access according to user context rather than network location. Compared with legacy perimeter-only deployment, cloud-delivered enforcement improves remote-user coverage without routing connections through headquarters. In 2025, third parties were involved in 30% of investigated breaches, making supplier access governance an immediate priority. Providers are expanding cloud partnerships and automated policy testing to reduce misconfiguration exposure.
Between 2026 and 2028, AI-assisted rule recertification, behavioral traffic analytics, and infrastructure-as-code integration will reshape delivery. Continuous configuration assessment supports audit readiness, while automated rollback limits disruption from faulty updates. Multivendor providers benefit because customers retain mixed firewall estates. Competitive advantage shifts toward verified enforcement quality, efficient onboarding, and operational visibility rather than appliance throughput alone.
November 2025: Cisco expanded managed service provider capabilities within its Hybrid Mesh Firewall architecture, introducing multicustomer management and Secure Firewall 200 Series appliances offering up to threefold price-performance improvement. The expansion strengthens scalable branch protection and centralized policy enforcement. Source: cisco.com
May 2025: Check Point launched AI-powered Quantum Force Branch Office Security Gateways, delivering up to fourfold faster threat prevention than previous models. Existing data center and perimeter gateways also received 15–25% throughput improvements, strengthening enterprise security performance. Source: checkpoint.com
August 2025: Palo Alto Networks introduced 14 fifth-generation firewalls across three product families, including PA-5500 systems delivering up to fourfold higher performance. The portfolio expansion strengthens high-capacity data center inspection, distributed branch security, and managed infrastructure modernization capabilities. Source: paloaltonetworks.com
February 2025: Sophos completed its Secureworks acquisition, combining managed detection services with the Taegis security platform. The integrated business supports over 28,000 managed detection customers, expanding enterprise threat monitoring capabilities and strengthening cross-selling opportunities across network security portfolios. Source: securityweek.com
The Managed Firewall and UTM Services Market Report evaluates industry performance and competitive developments from 2026 to 2033 across four service types: Managed Firewall Services, Unified Threat Management (UTM), Next-Generation Firewall Services, and Cloud-Based Firewall Services. Application coverage includes Network Security, Threat Prevention, Secure Remote Access, and Regulatory Compliance. End-user analysis examines Banking and Financial Services, Healthcare, Government, IT and Telecommunications, and Manufacturing, identifying differences in security procurement, deployment architecture, and operational requirements.
Regional coverage encompasses North America, Europe, Asia-Pacific, South America, and the Middle East & Africa. The report assesses 12 influential market participants, cloud-native firewalls, AI-assisted policy management, and identity-aware access enforcement. It examines emerging industrial network protection and multicloud security opportunities, supporting investment prioritization, geographical expansion, competitive benchmarking, and managed service portfolio development through 2033.
| Report Attribute/Metric | Report Details |
|---|---|
Market Revenue in 2025 | USD 8710 Million |
Market Revenue in 2033 | USD 17611.6 Million |
CAGR (2026 - 2033) | 9.2% |
Base Year | 2025 |
Forecast Period | 2026 - 2033 |
Historic Period | 2021 - 2025 |
Segments Covered | By Type
By Application
By End-User
|
Key Report Deliverable | Revenue Forecast, Growth Trends, Market Dynamics, Segmental Overview, Regional and Country-wise Analysis, Competition Landscape |
Region Covered | North America, Europe, Asia-Pacific, South America, Middle East, Africa |
Key Players Analyzed | Fortinet, Inc., Palo Alto Networks, Inc., Cisco Systems, Inc., Check Point Software Technologies Ltd., Sophos Limited, Orange Cyberdefense, BT Group plc, AT&T Inc., Verizon Communications Inc., NTT DATA Group Corporation, Trustwave Holdings, Inc., Secureworks |
Customization & Pricing | Available on Request (10% Customization is Free) |




