
Reports
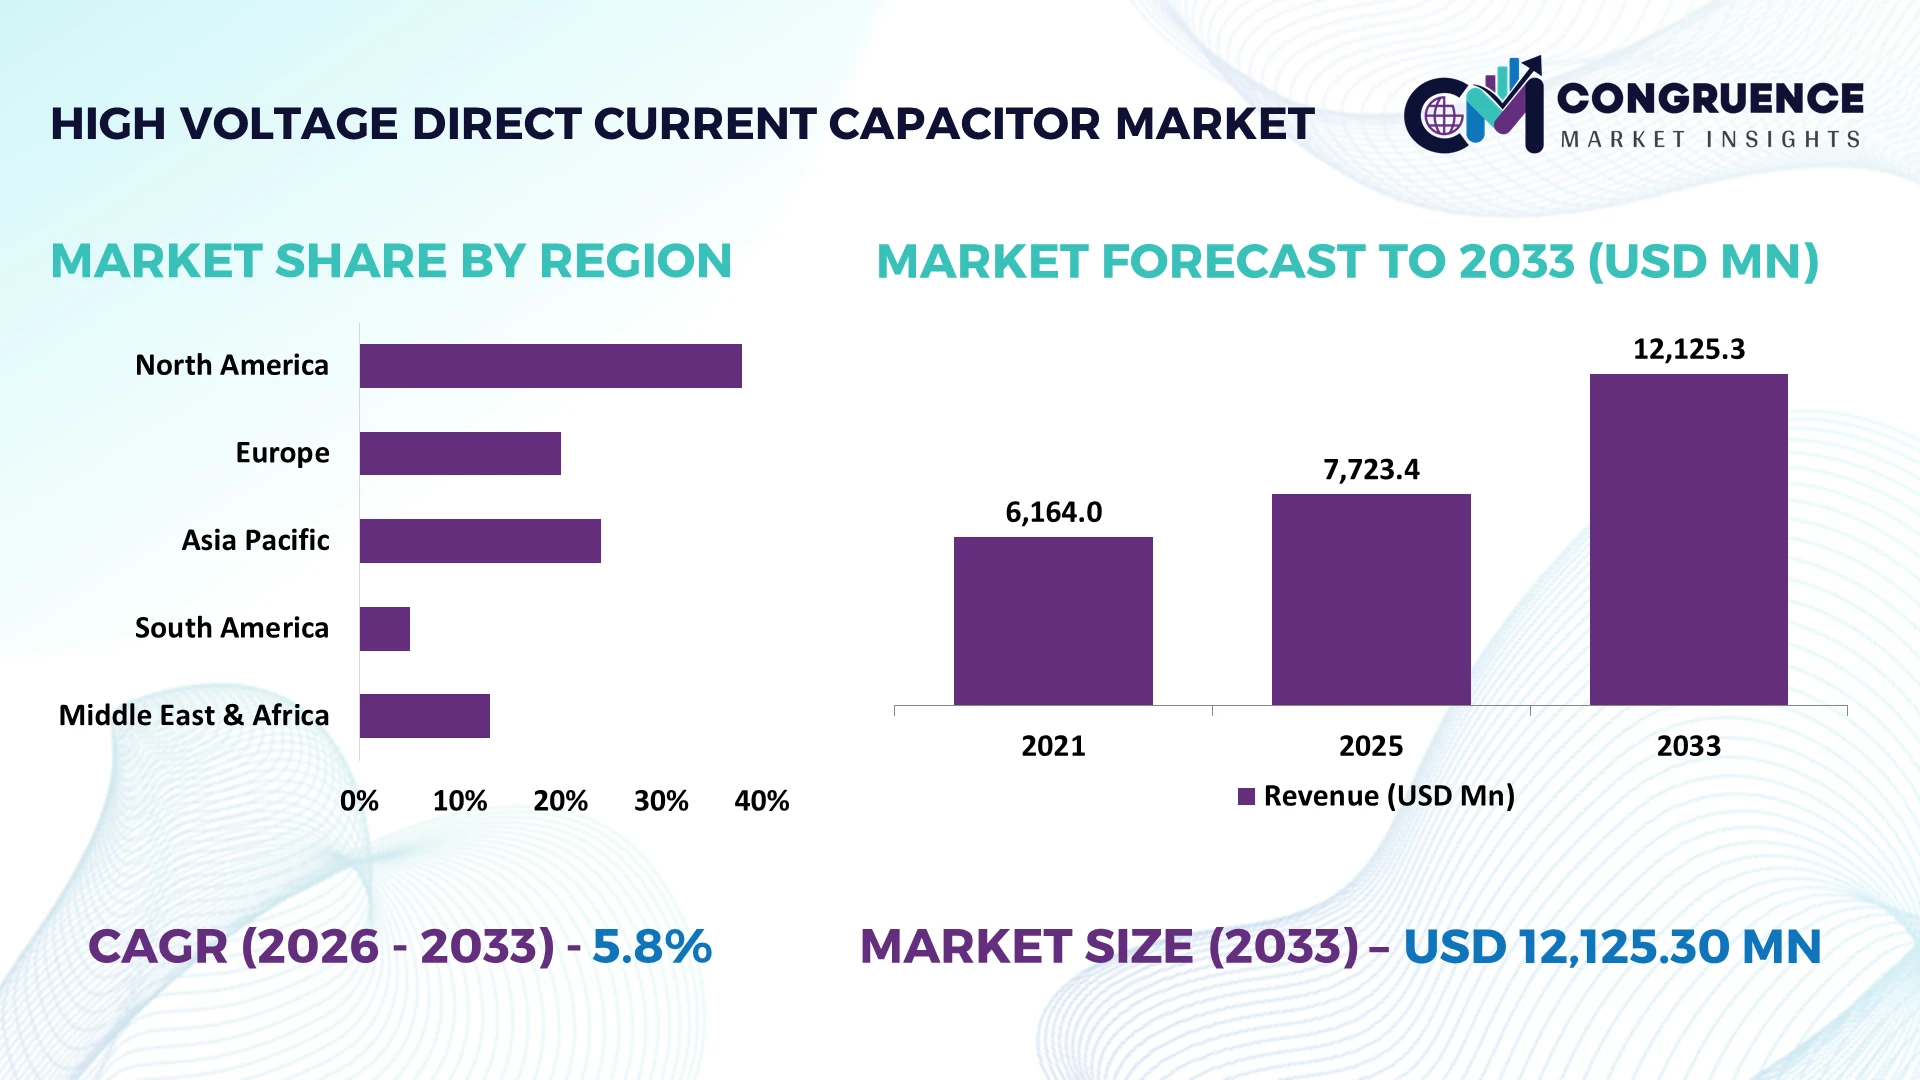
The Global High Voltage Direct Current Capacitor Market was valued at USD 7723.4 Million in 2025 and is anticipated to reach a value of USD 12125.3 Million by 2033 expanding at a CAGR of 5.8% between 2026 and 2033. Growth is driven by ultra-high-voltage transmission expansion, offshore wind grid integration, voltage source converter deployment, and increasing requirements for high-reliability DC filtering capacitors.
China dominates the global high voltage direct current infrastructure landscape through extensive ultra-high-voltage transmission networks, domestic capacitor manufacturing, and large-scale renewable electricity integration. China's installed renewable power capacity exceeded 1,800 GW in 2024, supporting advanced DC capacitor applications in converter stations and transmission networks. Its ±1,100 kV Changji–Guquan transmission system exceeds India's established ±800 kV HVDC voltage class by 37.5%. State Grid infrastructure investments, metallized polypropylene dielectric technology, and domestic power equipment manufacturing reinforce China's competitive position in high-voltage transmission systems.
Strategically, manufacturers should prioritize China's ±1,100 kV transmission infrastructure and India's ±800 kV grid modernization through advanced dielectric development, localized production, and long-term utility partnerships.
Market Size & Growth: The market reached USD 7,723.4 million in 2025 and is projected to attain USD 12,125.3 million by 2033, registering 5.8% CAGR, driven by HVDC transmission modernization.
Top Growth Drivers: Ultra-high-voltage transmission expansion (40%), electricity grid modernization (35%), and renewable energy integration (25%), representing an illustrative weighting of demand drivers.
Short-Term Forecast: By 2027, digital capacitor monitoring targets a modeled 10–15% reduction in unplanned maintenance interventions through predictive diagnostics and insulation condition assessment.
Emerging Technologies: Metallized polypropylene films, self-healing dielectric structures, and AI-enabled condition monitoring support advanced ±800 kV and ±1,100 kV transmission applications.
Regional Leaders: Illustrative 2033 allocations place Asia-Pacific at USD 5.46 billion, Europe at USD 3.15 billion, and North America at USD 2.18 billion, reflecting UHVDC deployment, offshore wind integration, and grid modernization.
Consumer/End-User Trends: Utility procurement increasingly prioritizes high-reliability components as more than 2,500 GW of renewable, storage, and large-load projects remain in global grid connection queues.
Pilot/Case Example: China's Changji–Guquan HVDC project, commissioned in 2019, achieved 50% higher transmission capacity than earlier ±800 kV links, demonstrating the operational advantages of ±1,100 kV technology.
Competitive Landscape: Hitachi Energy, Siemens Energy, GE Vernova, TDK, and Vishay compete through HVDC engineering, dielectric technologies, and system integration; individual capacitor market shares remain unverified.
Regulatory & ESG Impact: European RoHS requirements restrict lead concentrations to 0.1% in applicable homogeneous materials, strengthening demand for compliant dielectric materials and capacitor manufacturing processes.
Investment & Funding: China's State Grid announced approximately USD 574 billion in planned investments for 2026–2030, a 40% increase supporting transmission infrastructure and equipment procurement.
Innovation & Future Outlook: Advanced polymer dielectrics, digital diagnostics, and modular capacitor assemblies support ±800–1,100 kV systems, strengthening component reliability and lifecycle performance.
The High Voltage Direct Current Capacitor Market is increasingly influenced by long-distance renewable electricity transmission, offshore wind interconnections, and voltage source converter modernization. Advanced metallized polypropylene capacitors, self-healing dielectric structures, and integrated condition monitoring improve electrical reliability and maintenance planning. China's planned 40% increase in State Grid investment during 2026–2030 strengthens procurement opportunities for high-voltage components and specialized insulation systems. European offshore transmission projects are encouraging compact capacitor configurations and standardized testing requirements. These developments position dielectric performance, manufacturing consistency, and utility qualification capabilities as critical priorities for competitive differentiation and long-term strategic investment.
The High Voltage Direct Current Capacitor Market is becoming strategically important as utilities accelerate long-distance electricity transmission, renewable integration, and converter station modernization. China's operational ±1,100 kV Changji–Guquan transmission system delivers 12 GW of power transfer capacity, demonstrating the scale of advanced HVDC infrastructure. Increasing deployment of voltage source converters is shifting capacitor procurement toward high-energy-density dielectric materials, modular DC-link assemblies, and improved insulation reliability. Manufacturers are expanding qualification capabilities and strengthening partnerships with transmission equipment suppliers to secure long-term infrastructure contracts.
Technology modernization is improving transmission economics. HVDC transmission systems can reduce long-distance electricity losses by approximately 30–50% compared with conventional AC alternatives under suitable operating conditions. China's extensive ultra-high-voltage infrastructure contrasts with Europe's emphasis on offshore wind interconnections and India's expanding ±800 kV transmission corridors. Advanced metallized polypropylene capacitors provide self-healing capabilities and improved operational stability compared with conventional dielectric designs, strengthening converter reliability.
Between 2026 and 2028, capacitor manufacturers are prioritizing automated dielectric processing, predictive condition monitoring, and localized component production. India's renewable energy transmission projects provide practical deployment opportunities for high-voltage filtering and DC-link capacitors. Companies investing in accelerated insulation testing, digital diagnostics, and utility certification gain stronger procurement access, lower lifecycle risk, and sustainable competitive differentiation.
Rapid development of long-distance electricity transmission infrastructure is strengthening demand for high-voltage DC capacitors used in converter stations, harmonic filtering, and voltage stabilization. China's ±1,100 kV Changji–Guquan transmission system operates at 37.5% higher nominal voltage than conventional ±800 kV HVDC links. The International Energy Agency estimates that global electricity grid investment must increase by approximately 50% by 2030 to support energy transition requirements. India's renewable electricity expansion and interstate transmission development are accelerating procurement of high-reliability power electronics. Manufacturers are expanding metallized film production, strengthening converter equipment partnerships, and investing in advanced dielectric testing. Securing utility-approved capacitor designs provides suppliers with stronger access to multiyear transmission infrastructure programs.
High-voltage DC capacitor manufacturing faces structural constraints from specialized polypropylene films, aluminum metallization materials, insulation components, and stringent quality certification requirements. A modeled 15% increase in dielectric film procurement costs can significantly affect production economics when material expenses represent a substantial share of capacitor manufacturing costs. China's dominant position in electrical equipment manufacturing creates sourcing concentration for international converter suppliers. European manufacturers also face applicable RoHS restrictions limiting lead content to 0.1% in homogeneous materials, increasing material qualification requirements. A hypothetical 10% increase in compliance-related testing expenses further pressures smaller suppliers. Manufacturers are diversifying dielectric suppliers, establishing localized production partnerships, and negotiating long-term material contracts. Securing consistent film quality remains critical because insulation defects directly affect capacitor reliability and warranty exposure.
Next-generation dielectric materials and offshore HVDC converter systems create opportunities for compact, high-reliability capacitor assemblies. Europe's offshore wind expansion is increasing requirements for voltage source converters, DC-link capacitors, and advanced harmonic filtering systems. Metallized polypropylene capacitors incorporating self-healing structures can support modeled 10–15% reductions in maintenance interventions through improved fault tolerance and condition monitoring. Advanced modular capacitor designs also target 15–20% improvements in installation flexibility compared with conventional fixed assemblies. Germany's offshore transmission development and India's expanding renewable power corridors create opportunities for localized component qualification. Manufacturers are investing in dielectric research, automated winding technologies, and partnerships with converter system integrators. Integrated monitoring capabilities offer an additional competitive advantage through predictive maintenance services and improved lifecycle asset management.
Maintaining dielectric reliability across increasingly powerful HVDC converter installations presents substantial engineering and operational challenges. China's ±1,100 kV transmission infrastructure operates at 37.5% higher nominal voltage than ±800 kV systems, increasing insulation coordination requirements. Capacitor manufacturers must manage thermal cycling, partial discharge, harmonic stress, and electromagnetic compatibility within complex converter environments. Illustrative qualification programs targeting 99.9% component availability require extensive accelerated aging tests and continuous condition monitoring. A modeled 10% increase in testing complexity can extend product qualification schedules and delay utility procurement approvals. Manufacturers are investing in automated dielectric inspection, advanced simulation platforms, and collaborative testing with transmission equipment suppliers. Long-term competitiveness depends on maintaining consistent insulation performance while scaling production capacity and meeting increasingly demanding utility qualification standards.
Automated Dielectric Inspection Gains Industrial Adoption: Capacitor manufacturers are introducing machine vision inspection and automated film winding to improve production consistency. Illustrative manufacturing targets include 15–20% faster inspection cycles and 10–12% lower material rejection rates. China's electrical component manufacturers are integrating inline thickness measurement and defect detection into production workflows. Companies are expanding automated quality control systems to reduce insulation defects, improve manufacturing throughput, and strengthen qualification performance for high-voltage converter applications.
Digital Capacitor Monitoring Becomes Standardized: Utilities are integrating temperature sensors, partial discharge diagnostics, and predictive analytics into HVDC capacitor bank maintenance. Modeled deployment scenarios target 15% fewer unexpected maintenance interventions and 20% faster fault identification. India's transmission infrastructure modernization is encouraging centralized condition monitoring and remote asset diagnostics. Equipment suppliers are developing sensor-integrated capacitor assemblies and digital maintenance platforms to improve service reliability, reduce inspection requirements, and strengthen operational visibility across converter installations.
Grid Equipment Localization Reshapes Procurement: Supply chain diversification is encouraging capacitor manufacturers to establish regional production and qualification capabilities. Illustrative procurement strategies target 20–25% lower exposure to single-source suppliers and 10–15% shorter replacement component lead times. India's domestic electrical equipment manufacturing initiatives and European grid security requirements reinforce localization priorities. Manufacturers are developing regional dielectric sourcing agreements, expanding testing facilities, and strengthening utility partnerships to improve delivery reliability and reduce dependence on international component shipments.
Thermal Management Optimization Improves Reliability: Advanced capacitor assemblies increasingly incorporate improved heat dissipation, optimized winding geometry, and enhanced insulation monitoring. Engineering design targets include 10–15% lower localized temperature rise and 8–12% improvements in thermal operating stability. Germany's offshore converter installations require dependable operation under demanding environmental conditions. Manufacturers are refining enclosure designs, integrating thermal simulation, and introducing application-specific capacitor configurations to extend service intervals and reduce temperature-related degradation.
Film Capacitors Lead High-Voltage Applications
Film Capacitors represent the leading type in the High Voltage Direct Current Capacitor Market, with an indicative 38% share in 2025, supported by high dielectric strength, low electrical losses, and established utility qualification procedures. Their scalability across DC filtering and converter applications strengthens adoption in large transmission infrastructure projects. Ceramic Capacitors account for an estimated 17%, serving specialized high-frequency filtering and compact power electronics applications where thermal stability and low parasitic inductance are important. Manufacturers are investing in precision dielectric processing and automated winding equipment to strengthen electrical consistency and production efficiency.
Metallized Polypropylene Capacitors represent the fastest-growing type, with an indicative 32% share, supported by self-healing dielectric properties, improved energy density, and compatibility with advanced voltage source converter systems. Electrolytic Capacitors account for approximately 13%, primarily serving auxiliary DC-link and power conditioning functions where compact energy storage remains important. The shift toward metallized polypropylene technology is encouraging investment in advanced film processing, vacuum metallization, and modular capacitor configurations. Suppliers developing application-specific dielectric designs gain stronger positioning in high-reliability transmission and renewable integration projects.
HVDC Transmission Systems Dominate Capacitor Deployment
HVDC Transmission Systems represent the leading application, accounting for an indicative 36% of the High Voltage Direct Current Capacitor Market in 2025. Their dominance reflects extensive capacitor requirements for DC filtering, voltage stabilization, and converter station operation across long-distance transmission corridors. Line-Commutated Converter (LCC) Stations represent approximately 22%, supported by established high-capacity transmission infrastructure and reactive power compensation requirements. China's ±1,100 kV Changji–Guquan transmission system demonstrates the scale of capacitor deployment in advanced ultra-high-voltage installations. Manufacturers are strengthening utility qualification capabilities and developing application-specific capacitor banks to support demanding electrical operating conditions.
Voltage Source Converter (VSC) Stations represent the fastest-growing application, with an indicative 20% share, supported by offshore transmission networks, modular converter architectures, and flexible power flow control. Renewable Energy Grid Integration applications increasingly require capacitor technologies compatible with variable generation and converter-based transmission. Power System Stabilization remains important for voltage regulation and network reliability. Companies are investing in compact capacitor assemblies, integrated monitoring, and converter equipment partnerships to improve electrical performance and reduce installation complexity.
Power Transmission Utilities Lead Infrastructure Procurement
Power Transmission Utilities dominate the High Voltage Direct Current Capacitor Market, accounting for an indicative 40% share in 2025. Their leadership reflects direct responsibility for high-voltage transmission corridors, converter station reliability, and long-term electricity infrastructure development. Grid Infrastructure Operators represent approximately 22%, managing transmission assets, network modernization, and electrical system stability. Utility procurement emphasizes dielectric reliability, insulation coordination, and compliance with high-voltage equipment testing standards. China's State Grid and India's Power Grid Corporation demonstrate the importance of centralized transmission planning and large-scale equipment qualification. Manufacturers are strengthening utility partnerships and expanding high-voltage capacitor testing capabilities.
Renewable Energy Developers represent the fastest-growing end-user group, supported by offshore wind integration, large-scale solar generation, and long-distance renewable electricity transmission. HVDC Equipment Manufacturers require specialized capacitor assemblies for converter integration, while Industrial Power Systems utilize high-voltage components for demanding electrical applications. Companies are developing modular capacitor platforms, expanding technical support capabilities, and establishing long-term supply agreements. Competitive positioning increasingly depends on reliable dielectric performance, application-specific engineering, and coordinated delivery across transmission infrastructure projects.
Asia-Pacific accounted for the largest market share at an estimated 45% in 2025 however, Asia-Pacific is expected to register the fastest growth, expanding at a projected CAGR of 7.2% between 2026 and 2033.
Grid Modernization and Advanced Converter Infrastructure Deployment
North America accounted for an estimated 18% of the global High Voltage Direct Current Capacitor Market in 2025, supported by transmission modernization, renewable electricity integration, and interregional grid connectivity. The United States dominates regional equipment procurement through high-voltage transmission upgrades and converter station investments. Canada's hydroelectric transmission infrastructure strengthens demand for DC filtering capacitors and voltage stabilization equipment. The Champlain Hudson Power Express project involves approximately 339 miles of transmission infrastructure connecting Canadian hydropower with New York electricity networks. Increasing deployment of voltage source converter technologies is encouraging procurement of low-loss dielectric capacitors and advanced insulation components. Manufacturers are expanding partnerships with transmission utilities, strengthening domestic equipment qualification, and integrating digital condition monitoring into capacitor assemblies. These developments support reliable electricity transfer, improved transmission flexibility, and reduced dependence on aging electrical infrastructure.
United States Market Outlook: The United States maintains a strategic position through advanced electrical equipment engineering, utility modernization programs, and extensive renewable electricity development. The SunZia Transmission project includes approximately 550 miles of high-voltage direct current infrastructure designed to transfer 3,000 MW of electricity. Domestic transmission developers are strengthening converter equipment partnerships, capacitor qualification procedures, and grid reliability investments to support long-distance renewable power delivery.
Offshore Transmission Expansion and Converter Technology Modernization
Europe represented an estimated 26% of the global High Voltage Direct Current Capacitor Market in 2025, supported by offshore wind interconnections, cross-border electricity trading, and advanced converter station deployment. Germany, the United Kingdom, France, and Norway remain important markets for high-voltage transmission equipment and specialized capacitor technologies. Germany's SuedLink transmission project involves approximately 700 kilometers of underground HVDC infrastructure, strengthening demand for converter station components and high-reliability electrical insulation. European transmission system operators increasingly favor voltage source converter architectures for offshore applications and flexible grid integration. Capacitor manufacturers are developing compact metallized polypropylene assemblies, improving dielectric thermal stability, and expanding partnerships with converter equipment suppliers. European electricity infrastructure policies encourage interoperability, transmission resilience, and grid decarbonization. These requirements strengthen procurement opportunities for certified capacitor technologies capable of supporting demanding electrical and environmental operating conditions.
Germany Market Outlook: Germany maintains a strong position through established power electronics engineering, transmission infrastructure investment, and advanced industrial manufacturing. The SuedOstLink project incorporates approximately 540 kilometers of high-voltage underground transmission infrastructure, supporting renewable electricity transfer between northern and southern Germany. German manufacturers are strengthening dielectric material research, automated capacitor production, and utility certification capabilities to support high-reliability converter applications and transmission network modernization.
Ultra-High-Voltage Transmission Leadership and Manufacturing Scale Advantages
Asia-Pacific dominated the global High Voltage Direct Current Capacitor Market with an estimated 45% share in 2025, supported by extensive transmission infrastructure, concentrated electrical equipment manufacturing, and renewable electricity integration. China leads regional deployment through ultra-high-voltage direct current corridors and domestic converter equipment production. Its ±1,100 kV Changji–Guquan transmission system provides 12 GW of transfer capacity across approximately 3,300 kilometers. India is expanding interstate transmission infrastructure to connect renewable electricity generation centers with industrial demand regions. Japan and South Korea contribute advanced dielectric materials, precision manufacturing technologies, and specialized power electronic components. Regional capacitor manufacturers are investing in automated metallized film processing, high-voltage insulation testing, and localized supply networks. Strong domestic utility procurement and established electrical equipment ecosystems support manufacturing scale, technical qualification, and competitive component delivery.
China Market Outlook: China maintains technological leadership through extensive ultra-high-voltage transmission deployment, domestic power equipment manufacturing, and integrated electricity infrastructure planning. The country's renewable electricity capacity exceeded 1,800 GW in 2024, increasing requirements for long-distance power transmission and converter equipment. State Grid infrastructure programs support domestic capacitor manufacturers specializing in high-voltage dielectric films, harmonic filtering systems, and advanced insulation technologies. Integrated manufacturing networks strengthen equipment availability and project execution.
Hydropower Transmission Expansion and Long-Distance Grid Connectivity
South America accounted for an estimated 7% of the global High Voltage Direct Current Capacitor Market in 2025, supported by hydropower transmission infrastructure, renewable electricity integration, and long-distance grid development. Brazil dominates regional HVDC deployment through extensive hydroelectric generation and transmission networks connecting remote production centers with major industrial regions. The Belo Monte transmission infrastructure includes an approximately 2,500-kilometer HVDC corridor operating at ±800 kV, demonstrating the importance of advanced converter station equipment. Chile's renewable electricity development is strengthening requirements for transmission modernization and grid flexibility. Regional infrastructure projects face challenges involving financing, equipment import dependence, and difficult geographical conditions. Manufacturers are strengthening local engineering partnerships, expanding maintenance support, and developing high-reliability capacitor assemblies. These measures improve equipment availability and support long-term transmission reliability across geographically dispersed electricity networks.
Brazil Market Outlook: Brazil maintains regional leadership through large-scale hydropower generation, established HVDC transmission infrastructure, and growing renewable electricity development. The Itaipu transmission system includes approximately 800 kilometers of ±600 kV HVDC infrastructure connecting major hydroelectric generation facilities with southeastern electricity demand centers. Brazilian utilities are prioritizing converter station maintenance, dielectric component replacement, and transmission equipment modernization. Local service partnerships improve maintenance responsiveness and reduce dependence on imported replacement components.
Cross-Border Electricity Interconnections and Grid Infrastructure Modernization
The Middle East & Africa represented an estimated 4% of the global High Voltage Direct Current Capacitor Market in 2025, supported by cross-border electricity transmission, renewable energy integration, and national grid modernization programs. Saudi Arabia, the United Arab Emirates, Egypt, and South Africa are strengthening transmission infrastructure to improve electricity system flexibility. The Saudi Arabia–Egypt electricity interconnection project is designed for 3,000 MW of transfer capacity, creating requirements for advanced converter equipment and high-voltage electrical components. Saudi Arabia's renewable electricity diversification initiatives are encouraging investment in long-distance transmission infrastructure. Regional equipment procurement increasingly emphasizes reliability under elevated temperatures and demanding environmental conditions. Capacitor manufacturers are developing specialized thermal management designs, expanding utility partnerships, and strengthening regional maintenance capabilities. These investments support transmission availability and improve operational resilience across emerging electricity interconnection networks.
Saudi Arabia Market Outlook: Saudi Arabia is strengthening its position through large-scale electricity infrastructure investment, renewable energy development, and cross-border transmission connectivity. The Saudi Arabia–Egypt interconnection includes approximately 1,350 kilometers of transmission infrastructure, incorporating overhead lines and submarine cables. National grid modernization initiatives are increasing requirements for high-voltage insulation, converter station reliability, and advanced capacitor technologies. Equipment suppliers are expanding technical partnerships and developing heat-resistant electrical components suited to demanding operating conditions.
The High Voltage Direct Current Capacitor Market features competition between integrated transmission technology suppliers and specialized capacitor manufacturers. Hitachi Energy, Siemens Energy, and GE Vernova compete through converter system integration, while TDK, Vishay, and KYOCERA AVX emphasize dielectric engineering and component reliability. An illustrative market structure assigns the five largest participants a combined 45% share, although supplier-specific rankings require validation. Advanced metallized polypropylene designs target 10–15% lower dielectric losses, while automated manufacturing initiatives pursue 12–18% improvements in production efficiency. Integrated suppliers leverage utility relationships and converter qualification expertise, whereas specialized manufacturers compete through customized capacitor assemblies and competitive delivery schedules. Companies are expanding dielectric research, strengthening regional manufacturing partnerships, and integrating predictive monitoring technologies. Increasing insulation performance requirements and lengthy utility certification procedures create substantial entry barriers. Competitive success depends on verified electrical reliability, scalable manufacturing, localized technical support, and long-term converter equipment partnerships.
Hitachi Energy Ltd.
Siemens Energy AG
GE Vernova Inc.
TDK Corporation
Vishay Intertechnology, Inc.
KYOCERA AVX Components Corporation
KEMET Corporation (Yageo Group)
Cornell Dubilier Electronics, Inc.
WIMA GmbH & Co. KG
ELECTRONICON Kondensatoren GmbH
Shizuki Electric Co., Inc.
Samwha Capacitor Group
China XD Electric Co., Ltd.
Guilin Power Capacitor Co., Ltd.
Current HVDC capacitor technologies emphasize metallized polypropylene films, self-healing dielectric structures, and precision winding systems. These components support DC filtering, voltage stabilization, and converter station operation across ±800 kV transmission networks. Compared with conventional non-self-healing designs, advanced metallized capacitors target 10–15% lower maintenance requirements under modeled operating conditions. Automated dielectric inspection targets 12% fewer manufacturing defects, improving production consistency. China's extensive ultra-high-voltage infrastructure provides established deployment opportunities for qualified capacitor assemblies and integrated condition monitoring.
Emerging technologies include nanocomposite dielectric films, high-temperature polymer insulation, and sensor-integrated capacitor banks. Advanced dielectric formulations target 15–20% higher energy density, while embedded temperature and partial-discharge monitoring supports modeled 10–15% reductions in unplanned maintenance interventions. European offshore converter projects increasingly require compact capacitor assemblies compatible with modular multilevel converters. Manufacturers investing in dielectric research, automated metallization, and thermal simulation gain competitive advantages through improved component reliability and application-specific engineering capabilities.
Between 2026 and 2028, disruptive developments will emphasize digital-twin diagnostics, automated insulation qualification, and intelligent capacitor lifecycle management. Predictive analytics platforms target 20% faster fault identification through continuous electrical condition assessment. Integration with converter control systems improves maintenance scheduling and equipment availability. Suppliers combining advanced materials, scalable manufacturing, and utility-certified digital monitoring will strengthen procurement access across demanding transmission infrastructure programs.
January 2026: TDK introduced ModCap UHP DC-link capacitors delivering 20% higher current density and continuous operation at 105°C without derating. The innovation improves thermal endurance and supports compact power electronic converter designs, strengthening component reliability. Source: tdk-electronics.tdk.com
April 2025: Hitachi Energy partnered with BHEL to deliver HVDC converter terminals for India's 6,000 MW Bhadla–Fatehpur transmission corridor. The 950-kilometer project strengthens renewable electricity evacuation and expands demand for high-voltage converter components, including capacitors. Source: hitachienergy.com
May 2026: Siemens Energy detailed its SuedLink HVDC deployment in Germany, featuring 700 kilometers of transmission infrastructure and advanced converter stations. The project strengthens renewable electricity transfer, supporting demand for reliable converter insulation and high-voltage capacitor technologies. Source: siemens-energy.com
December 2024: Hitachi Energy secured contracts with German grid operator Amprion to supply four converter stations for Korridor B, incorporating two 2 GW HVDC links. The development strengthens grid integration and transmission equipment procurement. Source: reuters.com
The High Voltage Direct Current Capacitor Market Report examines industry developments, technology adoption, and competitive positioning between 2026 and 2033. Segmentation covers Film Capacitors, Ceramic Capacitors, Electrolytic Capacitors, and Metallized Polypropylene Capacitors. Application analysis evaluates HVDC Transmission Systems, VSC Stations, LCC Stations, Renewable Energy Grid Integration, and Power System Stabilization. End-user coverage includes transmission utilities, renewable energy developers, grid infrastructure operators, industrial power systems, and HVDC equipment manufacturers. Indicative analysis assigns Film Capacitors a 38% market share.
Regional assessment covers North America, Europe, Asia-Pacific, South America, and the Middle East & Africa, with Asia-Pacific holding an estimated 45% share. Technology evaluation examines advanced dielectrics, automated manufacturing, self-healing capacitors, and predictive monitoring. Competitive benchmarking supports manufacturing investment, supplier qualification, infrastructure expansion, and strategic procurement decisions across emerging HVDC applications.
| Report Attribute/Metric | Report Details |
|---|---|
Market Revenue in 2025 | USD 7723.4 Million |
Market Revenue in 2033 | USD 12125.3 Million |
CAGR (2026 - 2033) | 5.8% |
Base Year | 2025 |
Forecast Period | 2026 - 2033 |
Historic Period | 2021 - 2025 |
Segments Covered | By Type
By Application
By End-User
|
Key Report Deliverable | Revenue Forecast, Growth Trends, Market Dynamics, Segmental Overview, Regional and Country-wise Analysis, Competition Landscape |
Region Covered | North America, Europe, Asia-Pacific, South America, Middle East, Africa |
Key Players Analyzed | Hitachi Energy Ltd., Siemens Energy AG, GE Vernova Inc., TDK Corporation, Vishay Intertechnology, Inc., KYOCERA AVX Components Corporation, KEMET Corporation (Yageo Group), Cornell Dubilier Electronics, Inc., WIMA GmbH & Co. KG, ELECTRONICON Kondensatoren GmbH, Shizuki Electric Co., Inc., Samwha Capacitor Group, China XD Electric Co., Ltd., Guilin Power Capacitor Co., Ltd. |
Customization & Pricing | Available on Request (10% Customization is Free) |




