
Reports
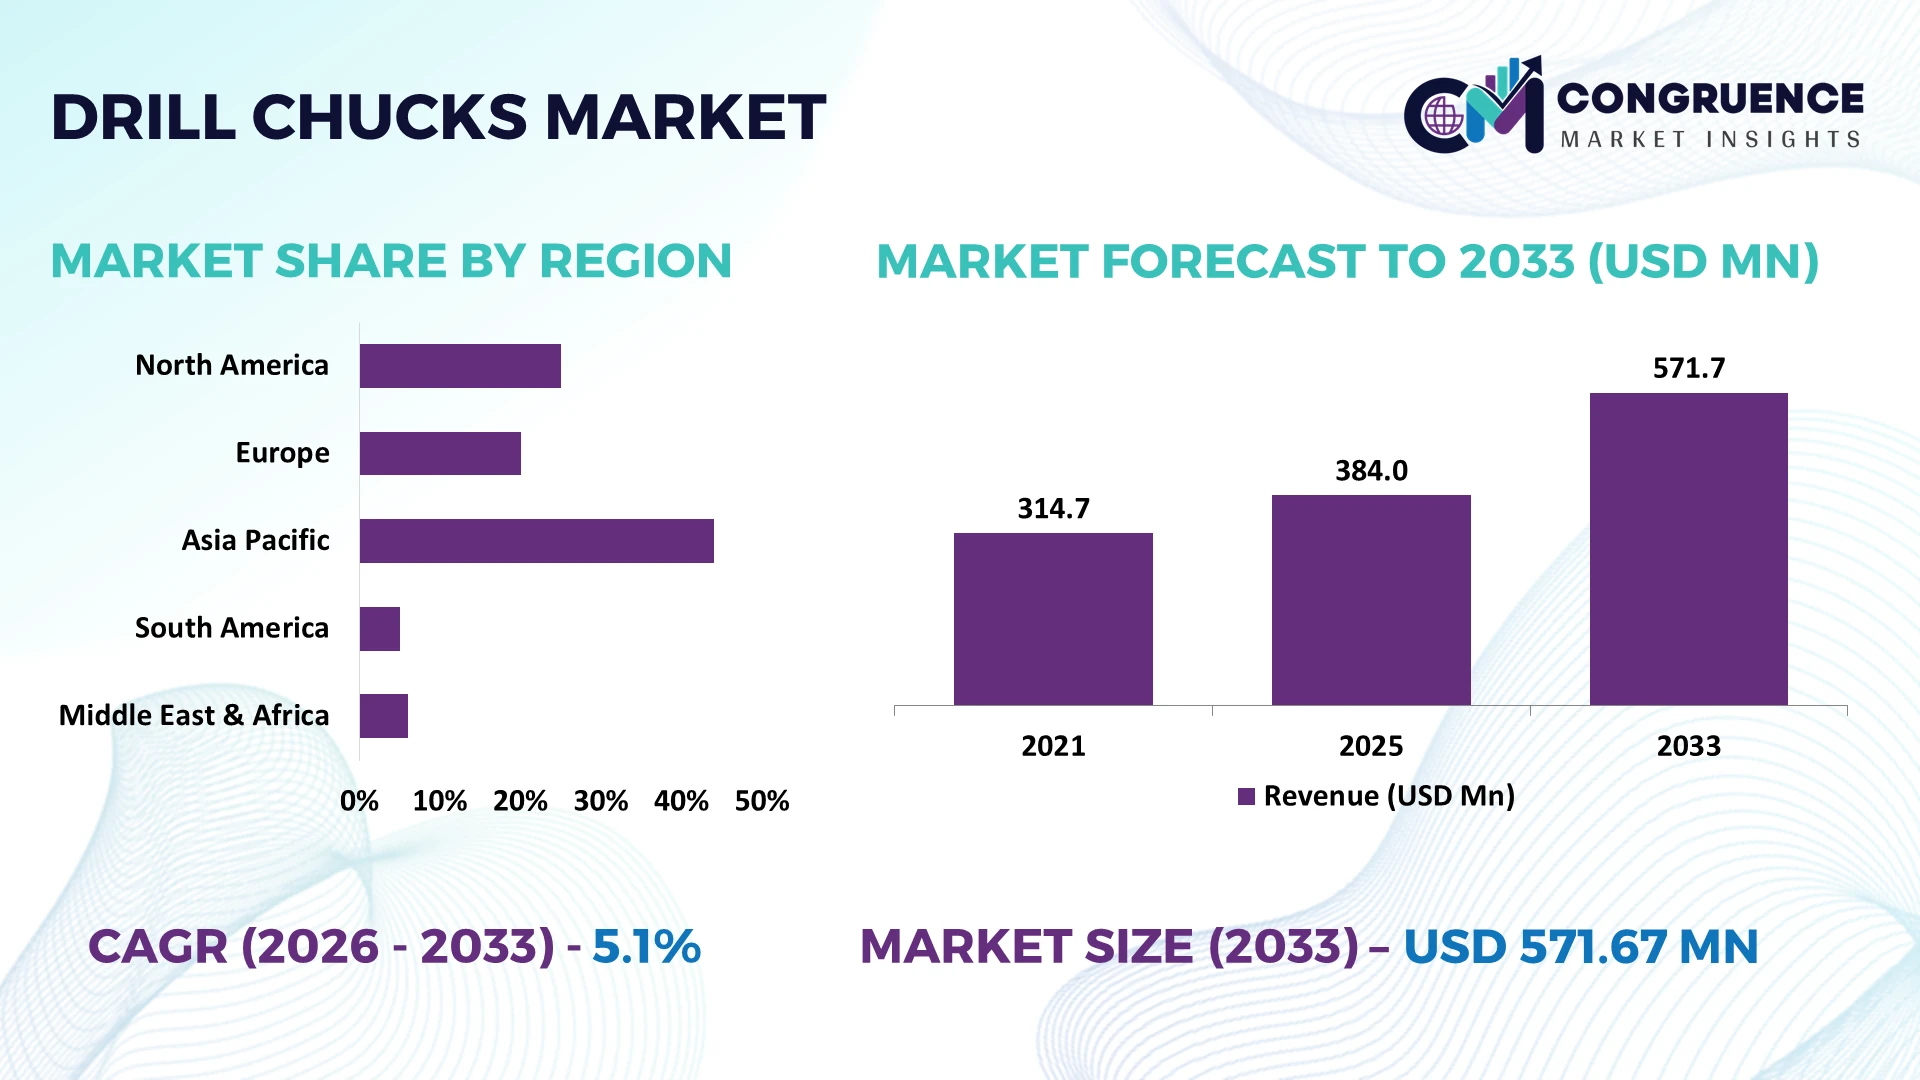
The Global Drill Chucks Market was valued at USD 384 Million in 2025 and is anticipated to reach a value of USD 571.67 Million by 2033 expanding at a CAGR of 5.1% between 2026 and 2033. Growth is driven by expanding cordless drill production, increasing demand for precision keyless chucks, CNC machining applications, and the adoption of automatic spindle locking mechanisms in professional power tools.
China dominates the global drill chuck manufacturing landscape through established precision engineering clusters in Zhejiang, Shandong, and Jiangsu. Manufacturers specialize in keyed, keyless, and self tightening drill chucks for automotive manufacturing, metalworking, construction, and power tool assembly. Standard 10 mm and 13 mm chuck capacities support high volume cordless drilling applications, while industrial precision models target runout tolerances below 0.05 mm. Compared with Germany's emphasis on precision engineered industrial chucks, Chinese suppliers prioritize production scale, automated machining, and export competitiveness amid international supply chain diversification.
Strategically, manufacturers should prioritize 10 mm and 13 mm keyless chuck platforms, precision jaw mechanisms, and localized supply partnerships to strengthen industrial customer retention and product differentiation.
Market Size & Growth: USD 384 million in 2025, reaching USD 571.67 million by 2033 at 5.1% CAGR, driven by cordless power tool integration and precision machining.
Top Growth Drivers: Keyless chuck adoption at 58%, machine tool applications at 55%, and 61% of professional buyers prioritizing faster tool changes.
Short Term Forecast: By 2027, precision machining upgrades target 10% fewer assembly defects through automated concentricity inspection and improved jaw calibration.
Emerging Technologies: Three innovations include self tightening mechanisms, vibration resistant clamping, and sensor integrated monitoring for advanced industrial drilling systems.
Regional Leaders: Indicative 2033 allocations place Asia Pacific at USD 240.10 million, Europe at USD 137.20 million, and North America at USD 125.77 million, emphasizing precision tooling adoption.
Consumer/End User Trends: Approximately 58% keyless chuck demand reflects preference for convenient bit replacement, especially across professional cordless drilling applications.
Pilot/Case Example: A proposed 2027 automated inspection pilot targets 15% fewer rejected chuck assemblies through precision runout measurement and calibrated jaw alignment.
Competitive Landscape: Röhm and Shandong Weida jointly hold an estimated 27% share; Jacobs, Albrecht, and Yukiwa Seiko strengthen competition in precision tooling.
Regulatory & ESG Impact: ISO 9001 manufacturing controls support product traceability, while precision grinding optimization targets 10% lower material scrap.
Investment & Funding: An illustrative USD 5 million manufacturing modernization program prioritizes CNC grinding, automated inspection, and supplier localization.
Innovation & Future Outlook: Advanced drill chucks emphasize 3 capabilities: automatic locking, precision concentricity, and connected condition monitoring for industrial applications.
The Drill Chucks Market is shifting toward precision clamping solutions as cordless power tool manufacturers, CNC machining facilities, and industrial maintenance operators prioritize secure bit retention and faster tool replacement. Keyless designs account for approximately 58% of product demand in one market assessment, reflecting changing preferences for operator convenience. Self tightening mechanisms, hardened gripping jaws, and precision ground components improve reliability in demanding drilling applications. China's established chuck manufacturing clusters support volume production, while German and Japanese suppliers emphasize concentricity and machining accuracy. These differences are reshaping equipment sourcing, product development, and competitive positioning across professional and industrial drilling applications.
The Drill Chucks Market is gaining strategic importance as power tool manufacturers and industrial machining companies prioritize precision clamping, faster bit replacement, and equipment compatibility. The transition toward cordless drilling platforms is reshaping chuck specifications, particularly for compact 10 mm and professional 13 mm configurations. China's established precision component manufacturing clusters support large scale production, while supply chain diversification encourages manufacturers to strengthen sourcing partnerships in India and Southeast Asia. Product differentiation increasingly depends on gripping reliability, dimensional accuracy, and integration with advanced spindle locking mechanisms.
Modern keyless drill chucks eliminate separate tightening keys and simplify tool replacement compared with conventional keyed designs. In repetitive drilling operations, manufacturers can target 15% to 20% shorter bit change times through improved locking mechanisms and ergonomic gripping surfaces. German and Japanese suppliers emphasize precision concentricity and industrial machining performance, while Chinese manufacturers compete through manufacturing scale and product customization. Between 2026 and 2028, automated inspection and precision grinding upgrades are expected to strengthen manufacturing consistency across professional tooling applications.
A practical deployment involves integrating automated runout inspection into drill chuck assembly lines, targeting 10% fewer rejected components through calibrated jaw alignment. Manufacturers are investing in CNC grinding equipment, hardened steel components, and application specific product development. Competitive positioning increasingly depends on consistent gripping performance, reliable supply agreements, and precision engineering capabilities.
Increasing adoption of cordless drilling equipment is strengthening demand for compact keyless drill chucks with reliable torque transmission and rapid bit replacement. Professional drilling platforms commonly utilize 10 mm and 13 mm chuck capacities, supporting diverse construction and maintenance applications. Modern keyless mechanisms can target 15% to 20% shorter bit change times compared with conventional keyed configurations, while precision jaw manufacturing can reduce assembly rejection rates by approximately 10% under controlled production conditions. China's established power tool manufacturing ecosystem supports large scale component integration, encouraging suppliers to expand automated machining capabilities. Manufacturers are investing in hardened gripping jaws, improved spindle interfaces, and precision grinding technologies. Competitive advantage increasingly depends on reliable chuck retention under repetitive drilling loads.
Drill chuck manufacturing faces structural cost pressure from alloy steel procurement, precision grinding requirements, and specialized component sourcing. High accuracy industrial chucks require tighter machining tolerances, increasing production complexity compared with standard consumer models. Precision grinding and inspection upgrades can raise initial equipment expenditure by an indicative 15% to 25%, while fluctuations in alloy steel procurement costs can influence component manufacturing expenses by approximately 10%. China's established steel processing network provides manufacturing scale advantages, but international suppliers remain exposed to shipping costs and currency movements. Manufacturers are responding through localized material procurement, long term supplier contracts, and standardized jaw component designs. Maintaining competitive pricing requires balancing machining precision against production efficiency and component availability.
Advanced keyless mechanisms and intelligent machining technologies create opportunities for drill chuck manufacturers targeting professional and industrial applications. Precision jaw geometry and improved locking designs can target 10% to 15% better gripping consistency under controlled operating conditions. Automated concentricity inspection offers potential reductions of 15% to 20% in quality verification time compared with manual measurement procedures. Germany's established precision engineering ecosystem supports development of high accuracy industrial chucks, while India's expanding machinery manufacturing capabilities create opportunities for localized component production. Manufacturers are strengthening research partnerships, investing in digital inspection systems, and developing application specific chuck configurations. Retrofit compatible precision chucks provide an additional opportunity by upgrading existing drilling equipment without requiring complete machine replacement.
Maintaining consistent chuck accuracy across large production volumes presents significant technical challenges involving jaw alignment, spindle compatibility, and quality control integration. Industrial precision chucks can require runout tolerances below 0.05 mm, placing demanding requirements on machining equipment and inspection procedures. Inadequate calibration can increase dimensional rejection rates, while manufacturers implementing advanced production systems target equipment availability above 90% and inspection consistency improvements of approximately 15%. Japanese precision tooling manufacturers maintain established expertise in concentricity control, creating competitive pressure for suppliers expanding into premium industrial applications. Companies must invest in skilled machining personnel, automated metrology, and standardized quality procedures. Long term competitiveness depends on maintaining precision consistency without sacrificing manufacturing throughput or equipment reliability.
Compact Chuck Architecture Gains Importance: Power tool manufacturers are refining chuck dimensions to accommodate increasingly compact drilling equipment. Standard 10 mm and 13 mm capacities remain important across portable drilling platforms. Compact housing configurations target 8% to 12% lower component weight while preserving gripping performance. Chinese suppliers are optimizing steel housing geometry and assembly processes, improving ergonomics and reducing material consumption without compromising durability.
Surface Engineering Improves Jaw Durability: Manufacturers are adopting advanced heat treatment, surface hardening, and wear resistant coatings to improve chuck jaw performance. Optimized treatments target 15% to 20% longer gripping surface durability and approximately 10% lower premature component replacement. German precision tooling suppliers are refining hardened steel specifications, while Chinese manufacturers are expanding controlled heat treatment capabilities to improve consistency across high volume production batches.
Standardized Interfaces Simplify Product Sourcing: International power tool manufacturers are prioritizing standardized spindle connections and interchangeable chuck configurations. Common 3/8 inch and 1/2 inch mounting interfaces support compatibility across established drilling platforms. Standardized component sourcing can target 10% to 15% lower inventory complexity and approximately 8% faster assembly scheduling. Suppliers are consolidating compatible product families and strengthening distribution partnerships to simplify replacement component availability.
Digital Traceability Reshapes Quality Management: Precision chuck manufacturers are implementing serialized component identification and digital production records to improve manufacturing accountability. Traceability systems can target 20% faster defect investigation and 10% shorter quality documentation cycles. Automotive and industrial tooling customers increasingly require consistent inspection records, encouraging suppliers to integrate barcode identification, digital metrology records, and centralized quality management platforms across production facilities.
Keyless Drill Chucks represent an estimated 38% of global drill chuck demand, reflecting their widespread integration into professional cordless drills and general purpose drilling equipment. Their principal advantage lies in convenient bit replacement without separate tightening tools, improving operating efficiency across repetitive drilling applications. Modern keyless configurations can target 15% to 20% shorter tool change times compared with conventional keyed designs. Manufacturers are expanding compact 10 mm and 13 mm product platforms while improving jaw geometry, locking mechanisms, and spindle compatibility. Keyed Drill Chucks maintain an established position in applications requiring mechanically assisted tightening and reliable tool retention.
Precision Drill Chucks represent the fastest expanding segment as industrial manufacturers prioritize concentricity, machining accuracy, and consistent clamping performance. Advanced precision models target runout below 0.05 mm, supporting demanding metalworking operations. SDS Drill Chucks serve specialized drilling systems requiring rapid tool engagement, while Hybrid Drill Chucks combine conventional tightening features with improved operating convenience. German and Japanese manufacturers emphasize precision engineering, while Chinese suppliers prioritize scalable production and competitive pricing. Investment increasingly favors differentiated clamping performance and application specific product configurations.
Metalworking accounts for an estimated 32% of global drill chuck applications, supported by extensive drilling, tapping, and precision hole making requirements across industrial manufacturing facilities. Metalworking operations prioritize concentricity, secure gripping force, and compatibility with different drill bit diameters. Precision chuck configurations targeting runout below 0.05 mm support improved hole positioning and machining consistency. Industrial Manufacturing represents the fastest expanding application as automated production equipment and digitally controlled machining operations increase requirements for reliable tooling interfaces. Equipment suppliers are strengthening precision grinding capabilities and expanding industrial chuck product portfolios to address these specifications.
Construction remains an important application, particularly through portable drilling equipment used for fastening, installation, and structural assembly. Woodworking emphasizes convenient bit replacement and consistent gripping across varying material densities. Automotive Repair requires durable chuck mechanisms compatible with repetitive maintenance operations. Advanced keyless systems can target 15% faster bit changes, improving workshop productivity. Manufacturers are developing application specific gripping jaws, improved spindle interfaces, and standardized replacement components. Competitive positioning increasingly depends on machining accuracy, product durability, and dependable distribution networks.
Metal Fabrication represents an estimated 30% of global drill chuck demand among the specified end user industries, reflecting frequent drilling operations across structural components, fabricated assemblies, and precision metal products. Fabrication facilities prioritize gripping reliability, dimensional accuracy, and compatibility with industrial drilling equipment. Precision chuck systems targeting runout below 0.05 mm support consistent machining outcomes, while improved keyless mechanisms can reduce repetitive tool change time by approximately 15%. Machine Shops remain important purchasers because their operations require adaptable chuck configurations across varied machining tasks and material specifications.
The Aerospace Industry represents the fastest expanding end user category, supported by stringent component accuracy requirements and increasing use of advanced manufacturing processes. Aerospace machining emphasizes precise tool alignment, reliable clamping, and consistent quality documentation. The Automotive Industry maintains established demand through vehicle component production and maintenance operations, while the Construction Industry prioritizes durable chucks for portable drilling equipment. Manufacturers are developing specialized precision chuck platforms, application specific product portfolios, and technical distribution partnerships. Investment priorities increasingly emphasize certified quality systems, product traceability, and dependable industrial performance.
Asia Pacific accounted for the largest market share at an estimated 42% in 2025 however, Asia Pacific is expected to register the fastest growth, expanding at an indicative CAGR of 6.2% between 2026 and 2033.
Professional Power Tool Integration and Precision Machining Modernization
North America accounted for an estimated 22% of global drill chuck demand in 2025, supported by established power tool manufacturing, aerospace machining, automotive maintenance, and industrial metalworking activities. The United States represents the principal regional market, with professional cordless drilling platforms driving demand for compact keyless chuck mechanisms. Standard 10 mm and 13 mm capacities remain important across construction and industrial maintenance applications. Industrial manufacturers increasingly prioritize precision jaw alignment, secure bit retention, and compatibility with automated drilling equipment. Canada's aerospace and machinery manufacturing sectors support demand for high accuracy clamping systems. Mexico's automotive production facilities strengthen procurement of durable industrial tooling components. Equipment suppliers are expanding distribution partnerships, improving replacement chuck availability, and introducing application specific products. Competitive differentiation centers on operational reliability, tool compatibility, and consistent gripping performance under repetitive industrial drilling conditions.
United States Market Outlook: The United States maintains a strong position through established industrial tooling distribution networks, professional power tool adoption, and advanced machining capabilities. Jacobs branded drill chucks serve professional drilling and industrial applications, while domestic machinery manufacturers require precision clamping components. The country's manufacturing sector employed approximately 12.8 million workers during 2025, supporting extensive equipment maintenance and machining activity. Suppliers emphasize standardized spindle connections, product durability, and reliable replacement component availability.
Precision Engineering and Advanced Industrial Clamping Technologies
Europe represented an estimated 24% of global drill chuck demand in 2025, supported by Germany's precision engineering capabilities and established industrial manufacturing networks across Italy, France, and the United Kingdom. European suppliers emphasize concentricity, clamping accuracy, and durable jaw mechanisms for professional and industrial drilling applications. Precision chuck configurations with runout specifications below 0.05 mm support demanding machining operations where hole accuracy influences component quality. Germany's automotive and machinery sectors maintain demand for advanced toolholding systems, while Italy's industrial equipment manufacturers require adaptable drilling components. European manufacturers are strengthening precision grinding capabilities, improving surface treatments, and expanding application specific product portfolios. Increasing emphasis on manufacturing traceability encourages investment in digital inspection and standardized quality documentation. Competitive positioning depends on machining accuracy, product reliability, and integration with established industrial equipment platforms.
Germany Market Outlook: Germany benefits from established precision tooling manufacturers, including Röhm and Albrecht, serving industrial machining and professional drilling applications. The country's automotive and mechanical engineering industries require reliable toolholding performance and consistent dimensional accuracy. German manufacturers emphasize precision ground components, hardened gripping jaws, and specialized clamping mechanisms. Industrial chuck specifications commonly include 1/2 inch mounting interfaces and demanding concentricity requirements, supporting premium equipment differentiation.
Manufacturing Scale and Cordless Tool Component Localization
Asia Pacific dominated the global drill chucks market with an estimated 42% share in 2025, supported by extensive power tool production, industrial machining, and precision component manufacturing. China maintains the largest regional manufacturing ecosystem, particularly across Zhejiang, Jiangsu, and Shandong, where suppliers produce keyed, keyless, and industrial precision chucks. Japan contributes advanced precision engineering capabilities through specialized tooling manufacturers, while India provides expanding opportunities for localized machining component production. Professional cordless drilling platforms increasingly utilize 10 mm and 13 mm chuck capacities, supporting standardized product manufacturing. China's integrated steel processing and component supply networks strengthen production scalability and export competitiveness. Manufacturers are expanding automated assembly capabilities, improving precision grinding processes, and developing compact chuck mechanisms. Regional competition increasingly centers on product accuracy, manufacturing flexibility, and reliable supply chain integration.
China Market Outlook: China maintains a leading position in drill chuck production through established component manufacturing clusters and integrated industrial supply networks. Shandong Weida Machinery manufactures drill chucks and related power tool components for domestic and international customers. China's manufacturing sector contributed approximately 25% of national economic output in 2024, demonstrating substantial industrial scale. Domestic suppliers emphasize automated machining, standardized jaw production, and export oriented product development.
Industrial Maintenance and Automotive Tooling Demand
South America accounted for an estimated 6% of global drill chuck demand in 2025, with Brazil representing the largest regional industrial market. Automotive manufacturing, metal fabrication, machinery maintenance, and construction equipment servicing support procurement of keyed and keyless drill chucks. Brazilian industrial facilities require durable clamping components compatible with conventional drilling equipment and increasingly adopted cordless power tools. Argentina and Colombia contribute additional demand through industrial maintenance and construction applications. Standard 10 mm and 13 mm capacities remain important for replacement chuck procurement and professional workshop operations. Imported component costs and currency fluctuations influence purchasing decisions, encouraging distributors to diversify suppliers and maintain regional inventories. Manufacturers are strengthening partnerships with industrial tool distributors and expanding replacement component portfolios. Competitive success depends on product availability, standardized mounting compatibility, and dependable performance across established drilling equipment.
Brazil Market Outlook: Brazil benefits from established automotive manufacturing clusters in São Paulo and industrial machinery operations across southern manufacturing centers. The country produces more than 2 million vehicles annually, supporting substantial machining, maintenance, and repair requirements. Industrial distributors supply drill chucks for workshop equipment, metal fabrication, and professional drilling applications. Suppliers emphasizing durable jaw mechanisms, accessible replacement components, and competitive procurement arrangements maintain stronger positions in price sensitive industrial markets.
Industrial Diversification and Infrastructure Equipment Modernization
Middle East & Africa represented an estimated 6% of global drill chuck demand in 2025, supported by infrastructure construction, industrial maintenance, energy equipment servicing, and manufacturing diversification. Saudi Arabia and the United Arab Emirates represent important markets for professional drilling tools used in construction and industrial installation activities. South Africa maintains established mining equipment maintenance and metal fabrication industries requiring durable industrial chuck mechanisms. Standard 13 mm keyless configurations support professional drilling applications, while keyed mechanisms remain relevant for conventional workshop machinery. Industrial procurement increasingly emphasizes equipment durability, replacement component availability, and compatibility with imported power tool platforms. Manufacturers are expanding distributor partnerships and improving regional inventory availability. Industrial localization initiatives encourage stronger relationships between international tooling suppliers and domestic equipment servicing companies, strengthening aftermarket demand and technical support capabilities.
Saudi Arabia Market Outlook: Saudi Arabia's Vision 2030 industrial diversification strategy supports manufacturing localization, infrastructure development, and industrial equipment modernization. The National Industrial Development and Logistics Program promotes domestic manufacturing capabilities across machinery and industrial components. Construction contractors and industrial maintenance providers require dependable drilling equipment compatible with professional power tool platforms. Suppliers offering standardized 10 mm and 13 mm chucks, durable clamping mechanisms, and reliable technical distribution gain advantages in industrial procurement.
The Drill Chucks Market features competition between precision engineering specialists Röhm, Albrecht, and Yukiwa Seiko and volume oriented manufacturers Shandong Weida and San Ou Machinery. The leading five suppliers collectively represent an indicative 35% market share, reflecting competition across industrial and professional drilling applications. German and Japanese manufacturers emphasize concentricity, gripping accuracy, and premium materials, while Chinese suppliers prioritize manufacturing scale, customization, and competitive pricing. Advanced keyless mechanisms target 15% to 20% faster bit replacement, while automated precision inspection can reduce assembly defects by approximately 10%. Manufacturers are expanding CNC grinding capacity, strengthening power tool partnerships, and integrating automated quality controls. Competition is shifting toward compact locking mechanisms, standardized spindle compatibility, and dependable component sourcing. Precision machining expertise, hardened jaw manufacturing, and established distribution relationships create significant entry barriers. Competitive success requires consistent clamping accuracy, reliable delivery, application specific engineering, and competitive lifecycle costs.
Röhm GmbH
Albrecht Präzision GmbH & Co. KG
Shandong Weida Machinery Co., Ltd.
Zhejiang San Ou Machinery Co., Ltd.
Yukiwa Seiko Inc.
Jacobs Chuck Manufacturing Company
Llambrich Precision S.L.
SBF Vertriebsgesellschaft mbH
BISON S.A.
Vertex Machinery Works Co., Ltd.
Chum Power Machinery Corp.
Drill Master Precision Tooling
Zhejiang Bried Machinery Co., Ltd.
Current drill chuck technologies emphasize precision jaw geometry, hardened steel components, automatic spindle locking, and compact keyless mechanisms. Professional drilling platforms commonly employ 10 mm and 13 mm capacities, demonstrating established deployment across construction and industrial maintenance. Keyless designs eliminate separate tightening tools, offering targeted bit replacement time reductions of 15% to 20% compared with conventional keyed mechanisms. Precision grinding and calibrated assembly can target 10% fewer concentricity defects, improving drilling accuracy and reducing component rejection.
Emerging technologies include advanced surface coatings, automated optical inspection, and digitally controlled jaw manufacturing. Optimized surface treatments target 15% longer gripping surface durability, while machine vision inspection can reduce quality verification time by approximately 20%. Sensor integrated production equipment monitors jaw alignment, dimensional variation, and assembly consistency. German and Japanese precision tooling specialists benefit from premium accuracy requirements, while Chinese manufacturers strengthen competitiveness through automated machining and scalable component production.
Between 2026 and 2028, disruptive developments will emphasize intelligent clamping verification, lightweight chuck architecture, and automated manufacturing integration. Digital inspection platforms can target 12% lower assembly defects, while optimized housing designs offer potential weight reductions of 8%. Manufacturers investing in modular interfaces, advanced metrology, and integrated production controls gain stronger product differentiation and improved supplier qualification across demanding industrial applications.
April 2026: RÖHM introduced its patented Shock Absorbing System for professional drill chucks, preventing accidental opening during abrupt spindle stops. The Extra 50 measures just 51 mm, combining compact dimensions with improved clamping security for cordless drilling applications. Source: roehm.biz.
June 2026: Llambrich Precision redesigned its CKS drill chuck range, standardizing hardened components and extending taper adapters. The changes improve compatibility and durability across 8 mm and 16 mm capacities, reducing adaptation conflicts for industrial machining customers. Source: leaderchuck.com.
October 2024: Kyocera Unimerco introduced 2 hydraulic chuck models, Hydro Chuck Uni and Hydro Chuck HD, for precision drilling and machining. The differentiated designs address general and demanding applications, expanding industrial tooling choices while improving application specific clamping capabilities. Source: kyocera.com.
November 2025: Dormer Pramet launched 3 solid carbide drill families, including Force Micro drills operating at 15,000 RPM. The expansion strengthens precision drilling requirements and increases demand for compatible high accuracy toolholding systems across industrial machining applications. Source: americanmachinist.com.
The Drill Chucks Market Report evaluates product technologies, manufacturing capabilities, competitive dynamics, and procurement trends from 2026 to 2033. Segmentation covers five types: Keyed Drill Chucks, Keyless Drill Chucks, SDS Drill Chucks, Hybrid Drill Chucks, and Precision Drill Chucks. Application analysis examines Metalworking, Woodworking, Construction, Automotive Repair, and Industrial Manufacturing. End user assessment covers the Automotive Industry, Aerospace Industry, Construction Industry, Metal Fabrication, and Machine Shops, highlighting precision requirements, equipment compatibility, and purchasing priorities.
Geographical coverage includes North America, Europe, Asia Pacific, South America, and Middle East & Africa, with emphasis on China, Germany, Japan, and the United States. Technology evaluation examines self tightening mechanisms, hardened jaws, precision grinding, and automated inspection. Competitive analysis supports investment planning, supplier selection, manufacturing localization, and strategic product development.
| Report Attribute/Metric | Report Details |
|---|---|
Market Revenue in 2025 | USD 384 Million |
Market Revenue in 2033 | USD 571.67 Million |
CAGR (2026 - 2033) | 5.1% |
Base Year | 2025 |
Forecast Period | 2026 - 2033 |
Historic Period | 2021 - 2025 |
Segments Covered | By Type
By Application
By End-User
|
Key Report Deliverable | Revenue Forecast, Growth Trends, Market Dynamics, Segmental Overview, Regional and Country-wise Analysis, Competition Landscape |
Region Covered | North America, Europe, Asia-Pacific, South America, Middle East, Africa |
Key Players Analyzed | Röhm GmbH, Albrecht Präzision GmbH & Co. KG, Shandong Weida Machinery Co., Ltd., Zhejiang San Ou Machinery Co., Ltd., Yukiwa Seiko Inc., Jacobs Chuck Manufacturing Company, Llambrich Precision S.L., SBF Vertriebsgesellschaft mbH, BISON S.A., Vertex Machinery Works Co., Ltd., Chum Power Machinery Corp., Drill Master Precision Tooling, Zhejiang Bried Machinery Co., Ltd. |
Customization & Pricing | Available on Request (10% Customization is Free) |




