
Reports
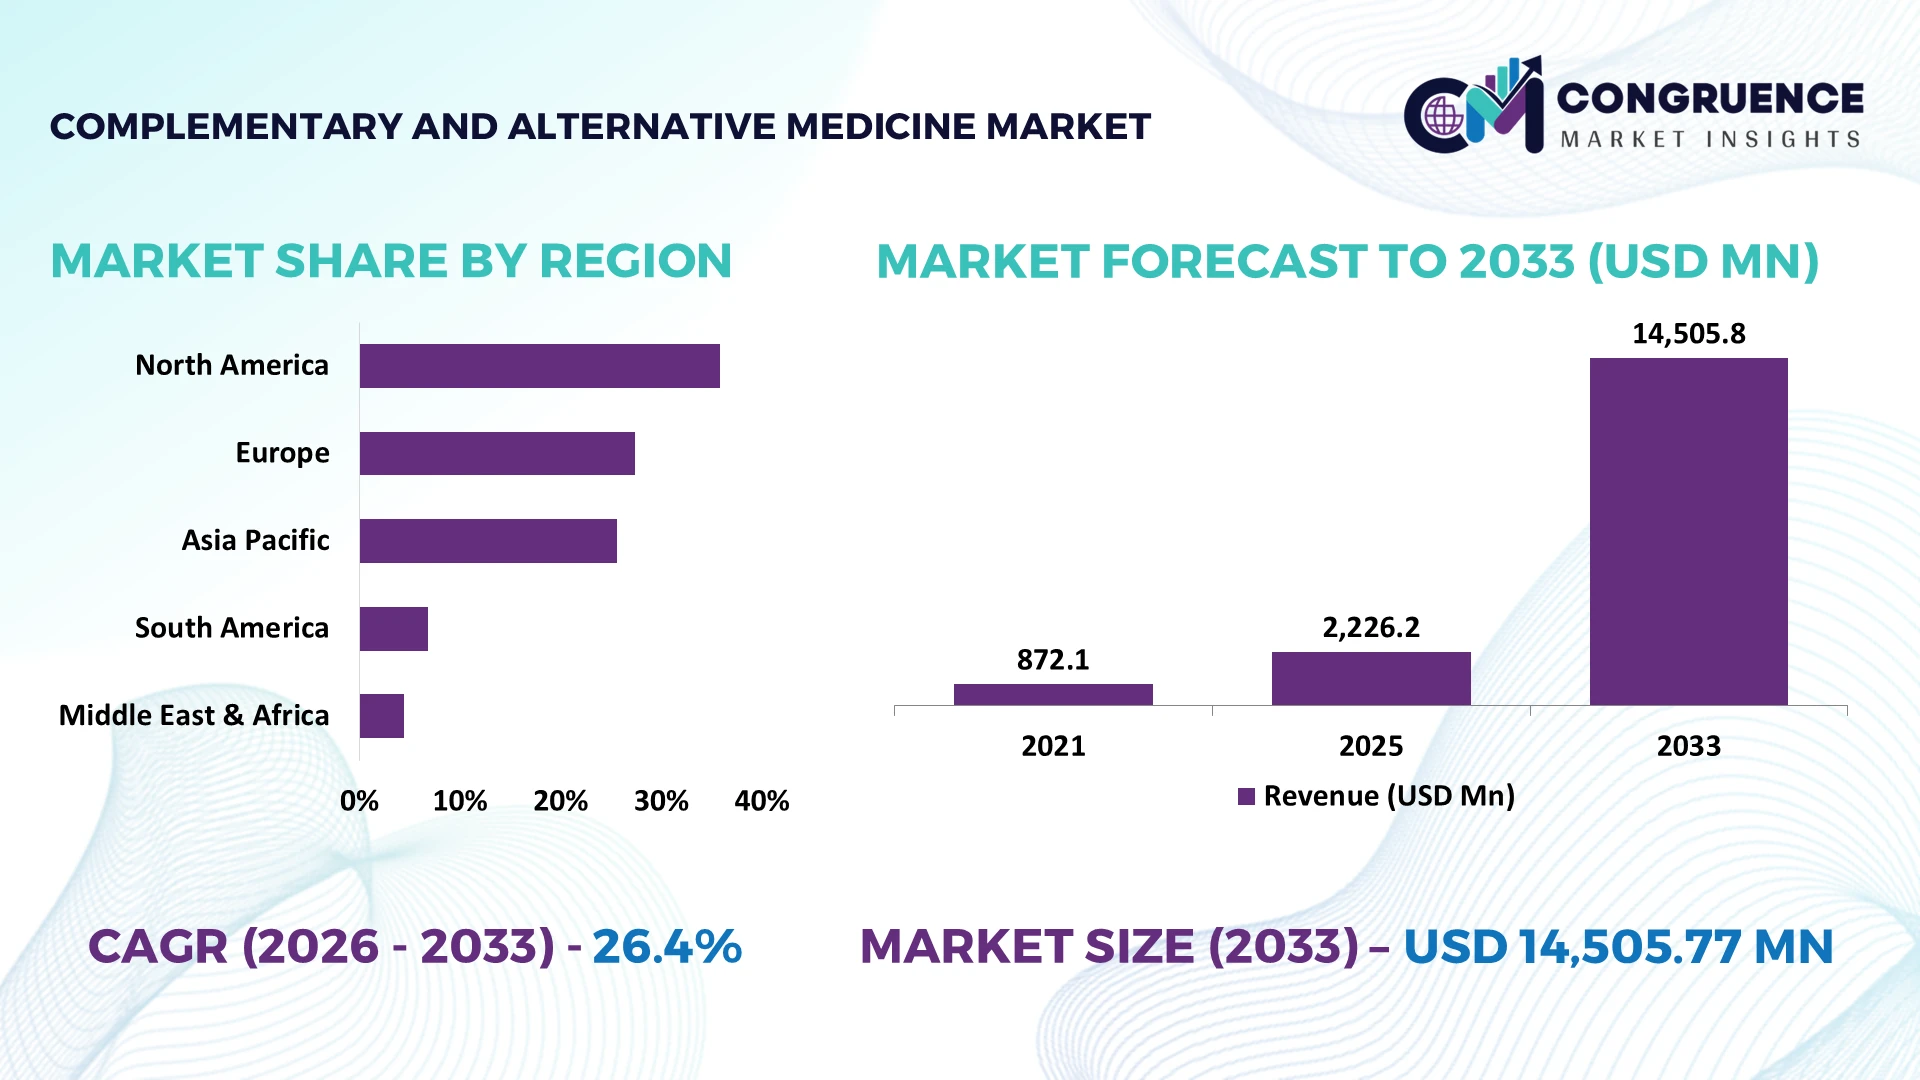
The Global Complementary and Alternative Medicine Market was valued at USD 2,226.2 Million in 2025 and is anticipated to reach a value of USD 14,505.8 Million by 2033 expanding at a CAGR of 26.4% between 2026 and 2033. Market expansion is driven by increasing integration of acupuncture, herbal therapeutics, chiropractic care, and mindfulness-based interventions into preventive healthcare, supported by digital wellness platforms and expanding insurance recognition.
The United States maintains a dominant position in the global complementary and alternative medicine industry, supported by established integrative healthcare networks and digital wellness infrastructure. According to the 2022 National Health Interview Survey, 36.7% of U.S. adults used at least one selected complementary health approach, compared with 19.2% in 2002. India's Ministry of AYUSH supports traditional medicine infrastructure, while China's national healthcare policies promote traditional Chinese medicine integration.
Strategically, providers combining evidence-based therapies, practitioner accreditation, and digital accessibility are positioned to capture stronger institutional partnerships and recurring patient engagement.
Market Size & Growth: USD 2,226.2 Million in 2025, reaching USD 14,505.8 Million by 2033 at 26.4% CAGR, driven by integrative healthcare adoption and digital wellness expansion.
Top Growth Drivers: U.S. adult complementary health approach usage reached 36.7%, while meditation adoption increased from 4.1% in 2012 to 17.3% in 2022.
Short-Term Forecast: By 2028, digital appointment integration and standardized practitioner documentation are expected to improve patient onboarding efficiency across established wellness networks.
Emerging Technologies: AI-assisted wellness personalization, wearable biometric monitoring, and telehealth-enabled integrative consultations are reshaping therapy delivery.
Regional Leaders: North America, Europe, and Asia Pacific anchor demand; their projected regional USD values require validated market-share allocations.
Consumer/End-User Trends: Yoga participation among U.S. adults increased from 9.5% in 2012 to 16.9% in 2022.
Pilot/Case Example: The 2022 U.S. National Health Interview Survey documented 17.3% adult meditation participation, establishing a measurable adoption benchmark.
Competitive Landscape: Herbalife, Amway, Dabur, Himalaya Wellness, and Patanjali compete across distinct wellness and traditional medicine categories; consolidated market leadership remains unverified.
Regulatory & ESG Impact: WHO's Traditional Medicine Strategy 2025–2034 establishes a 10-year framework emphasizing evidence, safety, regulation, and integration.
Investment & Funding: Public investment supports AYUSH infrastructure, practitioner education, and traditional medicine research; a comparable global funding total remains unavailable.
Innovation & Future Outlook: Personalized herbal formulations, AI-supported patient monitoring, and evidence-based integrative care models are strengthening service differentiation.
The complementary and alternative medicine market is experiencing increased activity across herbal medicine, acupuncture, yoga, meditation, and chiropractic services. Digital wellness applications and wearable monitoring technologies are improving consumer engagement and practitioner accessibility. U.S. meditation participation reached 17.3% in 2022, reinforcing demand for structured mind-body interventions. WHO's traditional medicine initiatives are accelerating attention toward clinical evidence, product quality, and standardized treatment practices.
Complementary and alternative medicine is becoming strategically important as healthcare providers diversify preventive care, chronic pain management, and behavioral wellness services. The integration of acupuncture, meditation, and evidence-informed herbal interventions into multidisciplinary treatment pathways is changing competitive positioning. WHO's Traditional Medicine Strategy 2025–2034 reinforces regulatory harmonization, clinical validation, and practitioner competency. Healthcare operators increasingly prioritize standardized treatment documentation, digital patient engagement, and measurable therapeutic outcomes to secure institutional partnerships.
Digital consultation platforms offer operational advantages over exclusively clinic-based appointment models by reducing travel requirements and expanding practitioner reach. In the United States, 36.7% of adults reported using selected complementary health approaches in 2022, demonstrating established consumer participation. India benefits from AYUSH-supported infrastructure and traditional medicine education, while China maintains extensive traditional Chinese medicine integration. These differences favor technology-enabled services in mature markets and infrastructure-supported expansion in established traditional medicine systems.
During 2026–2028, investment priorities are expected to concentrate on teleconsultation capabilities, clinical evidence generation, and practitioner accreditation. Hospitals integrating acupuncture into multidisciplinary pain management illustrate the shift toward coordinated service delivery. Companies are strengthening university partnerships, expanding digital booking infrastructure, and developing standardized patient monitoring protocols. Competitive advantage increasingly depends on validated outcomes, reliable service delivery, and institutional healthcare integration.
Increasing utilization of nonpharmacological therapies for chronic pain, stress management, and preventive wellness is strengthening the complementary and alternative medicine market. U.S. National Health Interview Survey findings indicate that adult use of selected complementary health approaches increased from 19.2% in 2002 to 36.7% in 2022. Meditation participation reached 17.3%, while yoga participation increased to 16.9% in 2022. These shifts encourage healthcare providers to incorporate structured mind-body interventions into broader treatment pathways. Growing clinical interest in acupuncture and multidisciplinary pain management supports institutional adoption. Companies are responding through practitioner training, digital appointment systems, and partnerships with healthcare facilities. The strongest operational advantage comes from combining accessible wellness services with documented clinical outcomes.
Inconsistent clinical evidence, product standardization, and regulatory classification constrain commercial scalability across complementary medicine categories. The U.S. National Health Interview Survey reported 36.7% adult participation in selected complementary approaches in 2022, yet widespread utilization does not establish therapeutic efficacy across individual treatments. Herbal products face variable ingredient concentrations, contamination risks, and inconsistent labeling requirements. India's traditional medicine manufacturers must navigate applicable AYUSH licensing and quality standards, while U.S. dietary supplements operate under a different regulatory framework. These differences increase compliance costs and complicate international product registration. Manufacturers are strengthening botanical traceability, laboratory testing, and supplier qualification. Commercial differentiation increasingly depends on verified product composition rather than traditional usage claims alone.
The convergence of digital health platforms, wearable monitoring, and personalized integrative care creates opportunities for scalable complementary medicine delivery. U.S. meditation participation increased from 4.1% in 2012 to 17.3% in 2022, demonstrating substantial expansion in consumer engagement with mind-body practices. Yoga participation reached 16.9% in 2022, supporting digital instruction and hybrid wellness programs. India's AYUSH ecosystem offers opportunities to connect accredited practitioners with remote consultations and standardized patient records. AI-supported scheduling, biometric feedback, and longitudinal symptom tracking can improve service coordination and patient engagement. Companies are investing in mobile wellness applications, clinical research partnerships, and practitioner marketplaces. The strategic opportunity lies in converting fragmented wellness participation into coordinated, measurable care pathways.
Scaling complementary and alternative medicine services requires consistent practitioner competencies, interoperable patient records, and credible outcome measurement. U.S. participation in selected complementary approaches reached 36.7% in 2022, while meditation and yoga adoption stood at 17.3% and 16.9%, respectively. These overlapping participation figures demonstrate substantial service diversity but also highlight the complexity of establishing comparable treatment outcomes. Integrating acupuncture, herbal consultations, and mind-body interventions into hospital workflows requires specialized training, informed consent protocols, and coordinated clinical documentation. China's traditional medicine infrastructure provides an established integration model, although international accreditation standards remain inconsistent. Providers must invest in workforce certification, secure digital records, and longitudinal effectiveness studies. Sustainable competitiveness depends on translating practitioner expertise into reproducible, evidence-supported service quality.
Standardized Botanical Manufacturing Gains Momentum: Herbal medicine manufacturers are strengthening ingredient authentication, extraction consistency, and batch-level quality control. India's Ministry of AYUSH oversees traditional medicine manufacturing standards, while WHO's Traditional Medicine Strategy 2025–2034 establishes a 10-year policy direction for quality and safety. Suppliers are introducing chromatographic fingerprinting, digital batch records, and validated botanical sourcing. Standardized manufacturing reduces product variability, strengthens export readiness, and supports partnerships with regulated healthcare distributors.
Institutional Acupuncture Services Become More Structured: Hospitals and specialty clinics are formalizing acupuncture referral pathways, practitioner credentialing, and treatment documentation. U.S. adult acupuncture utilization increased from approximately 1.0% in 2002 to 2.2% in 2022. Providers are introducing electronic referral systems and standardized treatment protocols to reduce administrative fragmentation. Specialist partnerships increasingly prioritize clinical documentation and patient retention rather than standalone appointment volumes.
Corporate Wellness Programs Shift Toward Outcomes: Employers are replacing isolated wellness activities with structured yoga, meditation, and stress-management programs. U.S. adult meditation participation reached 17.3% in 2022, while yoga participation reached 16.9%. Corporate wellness providers are introducing attendance analytics, employee feedback systems, and hybrid delivery formats. Companies are expanding enterprise subscriptions and tailoring interventions to workforce schedules, improving utilization visibility and program accountability.
Traditional Medicine Supply Chains Regionalize: Botanical ingredient processors are diversifying procurement as climate variability, agricultural traceability requirements, and international quality standards reshape sourcing. India's traditional medicine ecosystem and China's established herbal processing infrastructure remain strategically important. WHO's 2025–2034 strategy reinforces evidence and safety requirements. Manufacturers are developing contracted cultivation networks, regional extraction facilities, and authenticated ingredient inventories. The less obvious competitive advantage is consistent phytochemical composition, which improves formulation reproducibility and reduces downstream quality-control complexity.
Herbal medicine represents a leading segment of the complementary and alternative medicine market, accounting for approximately 34.6% of the market in 2025 within a published therapy-type classification. Established botanical formulations, standardized extracts, and widespread pharmacy distribution support commercial scalability. Traditional Chinese Medicine benefits from established healthcare infrastructure in China, while homeopathy maintains specialized consumer markets in India and parts of Europe despite limited clinical evidence for specific therapeutic claims. Naturopathy serves consumers seeking practitioner-guided lifestyle interventions. These segments compete through formulation quality, accessibility, treatment positioning, and regulatory compliance.
Mind-body interventions, including meditation and yoga, represent a rapidly expanding adjacent therapy category, supported by digital instruction and subscription-based wellness services. U.S. adult meditation participation reached 17.3% in 2022, while yoga participation reached 16.9%. Manufacturers such as Dabur and Himalaya Wellness are strengthening botanical product portfolios, while digital wellness providers prioritize personalized engagement and hybrid delivery. Investment is shifting toward authenticated herbal ingredients, standardized practitioner networks, and scalable digital interfaces.
Musculoskeletal disorders represent an established application for complementary and alternative medicine, supported by recurring utilization of acupuncture, chiropractic care, massage therapy, and movement-based interventions. However, published market classifications differ: one 2025 analysis identifies metabolic disorders as the leading application with approximately 27.08% share. Arthritis and musculoskeletal applications remain important because chronic pain management often requires repeated consultations and coordinated treatment pathways. Digestive disorders support demand for dietary interventions and selected botanical formulations, while other applications include general wellness and symptom management.
Stress and mental wellness represents a rapidly expanding application, supported by meditation, yoga, and structured relaxation programs. U.S. adult meditation participation reached 17.3% in 2022, compared with 4.1% in 2012. Providers are expanding employer-sponsored wellness programs, hybrid consultations, and digitally monitored behavioral interventions. Meanwhile, specialist clinics are integrating selected complementary approaches into multidisciplinary pain management. Competitive priorities increasingly emphasize documented patient outcomes, practitioner competency, and accessible appointment infrastructure rather than unverified therapeutic claims.
Adults represent the dominant end-user segment in an age-based complementary and alternative medicine classification, accounting for approximately 68.9% of the market in 2025. Demand concentrates among working-age consumers purchasing herbal products, accessing stress-management services, and seeking complementary approaches for musculoskeletal discomfort. Seniors represent an important group for practitioner-delivered services, particularly acupuncture and therapeutic massage, while pediatric utilization requires stronger clinical supervision and age-appropriate safety evaluation. Adult purchasing behavior supports pharmacy distribution, direct-to-consumer subscriptions, and digital wellness engagement.
Institutional buyers, particularly hospitals and specialty clinics, are becoming strategically important through multidisciplinary care integration. Another published classification places hospitals and specialty clinics at approximately 45% of its institutional and consumer end-user market. Wellness centers and spas continue serving relaxation and preventive wellness demand, while homecare and self-care benefit from remote consultations and digital instruction. Companies are strengthening practitioner referral partnerships, offering customized wellness packages, and developing hybrid service models. Competitive differentiation increasingly depends on patient safety, treatment documentation, and convenient service access.
North America accounted for the largest market share at 35.8% in 2025 however, Asia-Pacific is expected to register the fastest growth, expanding at a CAGR of 29.2% between 2026 and 2033.
North America accounted for approximately 35.8% of the global complementary and alternative medicine market in 2025, supported by established integrative healthcare infrastructure, high consumer awareness, and expanding practitioner networks. The United States dominates regional activity through acupuncture clinics, chiropractic practices, herbal supplement distribution, and hospital-affiliated wellness programs. The 2022 National Health Interview Survey found that 36.7% of U.S. adults utilized selected complementary health approaches, reflecting substantial consumer engagement. Canada contributes through regulated natural health products and growing multidisciplinary wellness services. Digital appointment platforms, wearable health monitoring, and virtual mindfulness programs are improving service accessibility. Healthcare organizations increasingly integrate nonpharmacological pain management into coordinated treatment pathways. Companies are strengthening clinical partnerships, practitioner accreditation, and evidence-based service portfolios to improve patient retention and institutional acceptance. Regulatory oversight remains important for botanical product quality and therapeutic claims.
United States Market Outlook: The United States maintains a competitive advantage through established healthcare networks, research institutions, and specialized integrative medicine centers. The National Center for Complementary and Integrative Health supports research into acupuncture, meditation, and natural products. Adult meditation participation reached 17.3% in 2022, while yoga participation stood at 16.9%. Healthcare providers are expanding structured mind-body programs and integrating electronic patient documentation, strengthening treatment coordination and commercial service differentiation.
Europe represented approximately 27.4% of the global complementary and alternative medicine market in 2025, supported by established herbal medicine industries, naturopathic services, and acupuncture practices. Germany, France, Italy, and the United Kingdom maintain significant consumer and practitioner ecosystems. European Union regulations governing traditional herbal medicinal products encourage standardized manufacturing, documented product quality, and pharmacovigilance. The European Medicines Agency's herbal monograph framework supports consistent evaluation of botanical ingredients across member states. Germany's established phytopharmaceutical industry strengthens regional formulation expertise, while France maintains an extensive pharmacy distribution network. Digital wellness providers are expanding meditation subscriptions and hybrid practitioner consultations. Manufacturers increasingly invest in authenticated botanical ingredients, traceable procurement, and validated extraction technologies. Competitive differentiation is shifting toward regulatory compliance, standardized formulations, and integration with established healthcare distribution channels rather than relying exclusively on traditional product positioning.
Germany Market Outlook: Germany benefits from a mature phytopharmaceutical manufacturing ecosystem and established pharmacy-based distribution. Companies including Schwabe Group and Bionorica maintain specialized capabilities in botanical extraction, formulation development, and quality-controlled production. Germany's healthcare infrastructure supports physician-supervised complementary interventions, while pharmaceutical manufacturing standards strengthen international commercialization. Investment priorities emphasize clinical documentation, ingredient standardization, and differentiated plant-based therapeutic portfolios.
Asia-Pacific accounted for approximately 25.6% of the global complementary and alternative medicine market in 2025, supported by extensive traditional medicine infrastructure, botanical manufacturing capabilities, and institutional healthcare integration. China maintains established traditional Chinese medicine hospitals, herbal processing facilities, and acupuncture services. India contributes through Ayurveda, yoga, naturopathy, and AYUSH-supported education and healthcare networks. Japan and South Korea strengthen regional capabilities through Kampo medicine and traditional Korean medicine practices. India's National AYUSH Mission supports traditional healthcare infrastructure development, while China's healthcare policies promote traditional medicine integration. Botanical manufacturers are investing in standardized extraction, ingredient authentication, and contract cultivation networks. Digital practitioner platforms are expanding consultation accessibility beyond metropolitan centers. Regional competitiveness increasingly depends on combining established therapeutic knowledge with pharmaceutical-grade manufacturing, clinical evaluation, and international product certification.
India Market Outlook: India holds a strategically important position through its Ayurveda manufacturing ecosystem, medicinal plant resources, and institutional AYUSH infrastructure. The country operates more than 750,000 registered AYUSH practitioners across recognized traditional medicine systems. Companies such as Dabur, Himalaya Wellness, and Patanjali maintain extensive botanical product portfolios and domestic distribution networks. Government-supported research, quality certification, and international cooperation strengthen India's positioning in standardized herbal formulations and integrative wellness services.
South America represented approximately 6.8% of the global complementary and alternative medicine market in 2025, supported by traditional botanical knowledge, expanding wellness services, and increasing interest in nonpharmacological healthcare. Brazil dominates regional activity through its medicinal plant resources, integrative healthcare programs, and established pharmaceutical manufacturing infrastructure. Argentina, Chile, and Colombia contribute through herbal product distribution, acupuncture services, and specialized wellness centers. Brazil's Unified Health System incorporates integrative and complementary health practices, supporting structured service delivery within public healthcare facilities. Regional manufacturers are improving botanical ingredient traceability, extraction consistency, and packaging standards. However, uneven practitioner availability, fragmented distribution networks, and limited clinical research infrastructure constrain commercialization outside major cities. Companies are developing partnerships with local healthcare providers, botanical cooperatives, and research institutions to strengthen supply reliability and expand access to standardized complementary therapies.
Brazil Market Outlook: Brazil maintains regional leadership through its extensive medicinal plant biodiversity, pharmaceutical manufacturing capabilities, and public healthcare integration. The National Policy on Integrative and Complementary Practices supports the inclusion of selected therapies within the Unified Health System. More than 20 integrative practice categories are recognized within the policy framework. Brazilian enterprises are prioritizing phytotherapeutic product development, sustainable botanical sourcing, and partnerships with universities to improve clinical validation and domestic commercialization.
The Middle East & Africa accounted for approximately 4.4% of the global complementary and alternative medicine market in 2025, supported by healthcare diversification, traditional herbal medicine practices, and expanding private wellness infrastructure. The United Arab Emirates and Saudi Arabia are strengthening integrative healthcare capabilities through specialized clinics, medical tourism, and preventive wellness initiatives. South Africa contributes through indigenous medicinal plant research, herbal product manufacturing, and complementary practitioner services. Saudi Arabia's Vision 2030 healthcare transformation encourages preventive care and service diversification, creating opportunities for regulated wellness providers. Regional distributors increasingly emphasize imported botanical products, standardized formulations, and practitioner-led services. Infrastructure gaps and inconsistent regulatory requirements continue to limit broader market penetration. Companies are responding through hospital partnerships, practitioner training, localized distribution, and investments in product authentication to improve commercial reliability and patient confidence.
Saudi Arabia Market Outlook: Saudi Arabia is strengthening its complementary medicine ecosystem through healthcare modernization, regulatory oversight, and private-sector investment. The National Center for Complementary and Alternative Medicine supports practitioner regulation, professional development, and public awareness. Vision 2030 initiatives are encouraging preventive healthcare and specialized wellness service expansion. Private healthcare operators are investing in accredited treatment facilities, integrated patient management systems, and structured wellness programs to improve service quality and institutional acceptance.
The complementary and alternative medicine market remains fragmented, with the five largest participants estimated to control less than 15% of global activity, reflecting competition across products and practitioner services. Dabur, Himalaya Wellness, and Patanjali compete in botanical formulations, while Schwabe Group and Bionorica emphasize standardized phytopharmaceuticals. Herbalife and Amway challenge traditional suppliers through direct selling and personalized nutrition. U.S. meditation participation reached 17.3%, while yoga adoption reached 16.9%, encouraging digital wellness differentiation. Manufacturers prioritize ingredient traceability, extraction consistency, and distribution partnerships to strengthen product reliability. Indian suppliers leverage established medicinal plant networks, whereas European producers emphasize clinical documentation and regulatory compliance. Competition increasingly shifts toward authenticated botanical sourcing, digital patient engagement, and integrated healthcare partnerships. Clinical validation expenses, practitioner accreditation, and regulatory fragmentation create entry barriers. Winning requires consistent product quality, credible therapeutic evidence, efficient distribution, and differentiated patient experiences across institutional and consumer channels worldwide.
Dabur India Limited
Himalaya Wellness Company
Patanjali Ayurved Limited
Schwabe Group
Bionorica SE
Herbalife Ltd.
Amway Corporation
Nature's Way Brands, LLC
Gaia Herbs, Inc.
Boiron SA
Emami Limited
Organic India Private Limited
TCM Healthcare (London) Limited
Health & Happiness (H&H) Group
Digital health platforms, standardized botanical extraction, and electronic clinical documentation are transforming complementary medicine delivery. AI-assisted scheduling and virtual consultations improve practitioner accessibility while reducing administrative workloads. U.S. adult meditation participation reached 17.3% in 2022, indicating established demand for digitally deliverable mind-body services. Compared with paper-based appointment management, integrated scheduling systems can target 15–25% lower administrative processing time, depending on clinic utilization. Providers implementing electronic records gain stronger referral coordination, appointment visibility, and longitudinal patient monitoring capabilities across multidisciplinary treatment environments.
Emerging technologies include chromatographic botanical fingerprinting, DNA-based ingredient authentication, wearable biometric sensors, and personalized wellness analytics. High-performance liquid chromatography supports consistent phytochemical identification, while automated extraction improves batch reproducibility. Manufacturers targeting 10–20% reductions in quality-control processing time benefit from integrated laboratory information systems and digital production records. Wearable monitoring introduces measurable engagement indicators for meditation, relaxation, and movement-based interventions. Established pharmaceutical manufacturers benefit from validated production infrastructure, while specialized digital wellness companies compete through accessible interfaces and personalized service delivery.
Between 2026 and 2028, interoperable clinical platforms, AI-supported symptom tracking, and automated botanical quality assurance will influence investment priorities. Healthcare providers will emphasize practitioner credentialing, secure patient information exchange, and documented treatment outcomes. Manufacturers integrating cultivation traceability with analytical testing will strengthen export readiness. Competitive advantage will increasingly depend on combining clinical credibility, operational efficiency, and reliable technology integration across complementary healthcare services.
June 2025: Dabur India launched Siens, a digital-first nutraceutical brand covering 3 wellness categories: beauty, daily wellness, and gut health. The expansion strengthens direct-to-consumer distribution and positions Dabur to compete in science-backed supplements and personalized preventive wellness. Source: dabur.com.
May 2026: Amway completed a $75 million manufacturing investment at its Michigan headquarters, converting 52,000 square feet into advanced Nutrilite production facilities. The expansion strengthens botanical supplement manufacturing, quality control, and global supply capabilities across 60 markets. Source: amwayglobal.com.
July 2025: Boiron USA launched Arnica.com, a dedicated educational platform covering homeopathic Arnica montana and related wellness products. The digital initiative creates 1 centralized information destination, strengthening consumer education, product discovery, and brand engagement within the complementary medicine category. Source: boironusa.com.
February 2026: Herbalife announced Cristiano Ronaldo's $7.5 million investment for a 10% equity stake in its Pro2col technology subsidiary. The transaction supports development of personalized digital wellness services, strengthening Herbalife's technology ecosystem and differentiation beyond conventional nutritional supplement distribution. Source: herbalife.com.
The Complementary and Alternative Medicine Market Report evaluates industry developments, competitive positioning, and strategic opportunities between 2026 and 2033. Segmentation covers herbal medicine, traditional Chinese medicine, homeopathy, naturopathy, and mind-body interventions, alongside applications in musculoskeletal conditions, metabolic disorders, digestive health, and mental wellness. End-user analysis examines adults, seniors, hospitals, specialty clinics, wellness centers, and homecare consumers. Regional coverage includes North America, Europe, Asia-Pacific, South America, and the Middle East & Africa, with country-level assessments of healthcare integration and regulatory frameworks.
The report examines botanical extraction, AI-assisted wellness platforms, teleconsultation, and digital patient monitoring. U.S. adult complementary health approach participation reached 36.7% in 2022, illustrating established consumer engagement. Competitive analysis evaluates product standardization, practitioner accreditation, distribution partnerships, and clinical validation, supporting investment planning, market entry, portfolio diversification, and international expansion decisions.
| Report Attribute / Metric | Details |
|---|---|
| Market Revenue (2025) | USD 2,226.2 Million |
| Market Revenue (2033) | USD 114,505.8 Million |
| CAGR (2026–2033) | 26.4% |
| Base Year | 2025 |
| Forecast Period | 2026–2033 |
| Historic Period | 2021–2025 |
| Segments Covered |
By Type
By Application
By End-User
|
| Key Report Deliverables | Revenue Forecast; Market Trends; Growth Drivers & Restraints; Technology Insights; Segmentation Analysis; Regional Insights; Competitive Landscape; Regulatory & ESG Overview; Recent Developments |
| Regions Covered | North America; Europe; Asia-Pacific; South America; Middle East & Africa |
| Key Players Analyzed | Dabur India Limited; Himalaya Wellness Company; Patanjali Ayurved Limited; Schwabe Group; Bionorica SE; Herbalife Ltd.; Amway Corporation; Nature's Way Brands, LLC; Gaia Herbs, Inc.; Boiron SA; Emami Limited; Organic India Private Limited; TCM Healthcare (London) Limited; Health & Happiness (H&H) Group |
| Customization & Pricing | Available on Request (10% Customization Free) |




